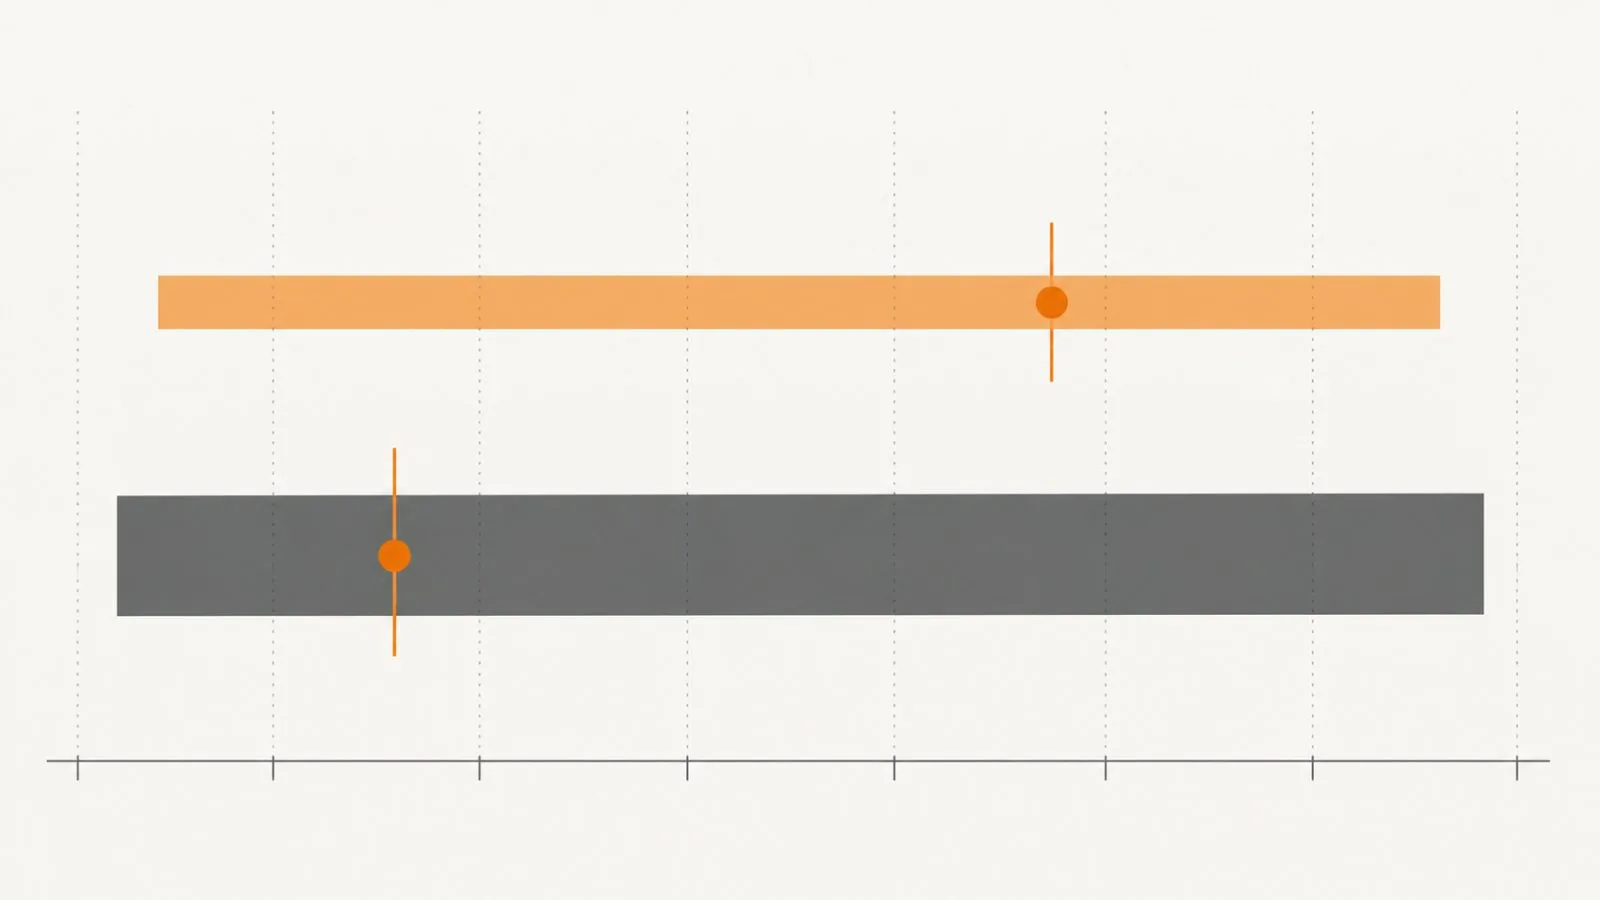
A gap of about 18 percentage points separated two Bitcoin (BTC) volatility gauges on Oct. 20, but their different price inputs and time frames limit what the comparison shows.
At 8 a.m. ET (12:00 UTC), Deribit’s DVOL index read 38.28% annualized. An estimate based on the exchange’s perpetual futures closing prices over 14 days put annualized realized volatility at 20.2%.
DVOL draws on options prices to estimate the scale of Bitcoin’s potential price moves over 30 days. The futures calculation describes price changes in an earlier period. Subtracting one annualized reading from the other produces a difference of 18.08 percentage points, but it does not show that observed volatility increased by that amount. Neither reading indicates which direction Bitcoin’s price will move.
The Daily Digits put DVOL’s Oct. 19 close at 37.33, as noted in earlier EconoTimes DVOL coverage. That daily close and the Oct. 20 morning reading were taken at different times.
Deribit’s next monthly Bitcoin options expiry is set for 4 a.m. ET (08:00 UTC) on Oct. 30. DVOL’s 30-day period reaches beyond that date.