Eternal Limited reported higher year-over-year profit for the September quarter, while ICICI Securities kept its Buy rating and ₹425 target, citing a stronger second-half outlook for food delivery and quick commerce.
The unaudited filing for the quarter ended Sept. 30 showed consolidated revenue from operations of ₹24,138 crore, compared with ₹13,590 crore in the same period a year earlier. Net profit was ₹125 crore, up from ₹65 crore. Deloitte Haskins & Sells conducted a limited review, the filing said.
Eternal’s Q2 FY27 results page also reported adjusted revenue of ₹24,621 crore, up 76% year over year, and adjusted EBITDA of ₹666 crore, up 197%. The company presents these as adjusted measures, separately from revenue from operations in its filing. ICICI’s results discussion cited a separate EBITDA figure of ₹750 crore.
In its Oct. 22 report, ICICI maintained the rating and target using a three-stage discounted cash flow model. The brokerage said revenue of about ₹24,140 crore was in line with its estimate and its EBITDA figure was 4.9% above forecast. The ₹425 target is about 36% above Eternal’s ₹312.35 close on the National Stock Exchange of India on Oct. 21, a comparison calculated from those prices.
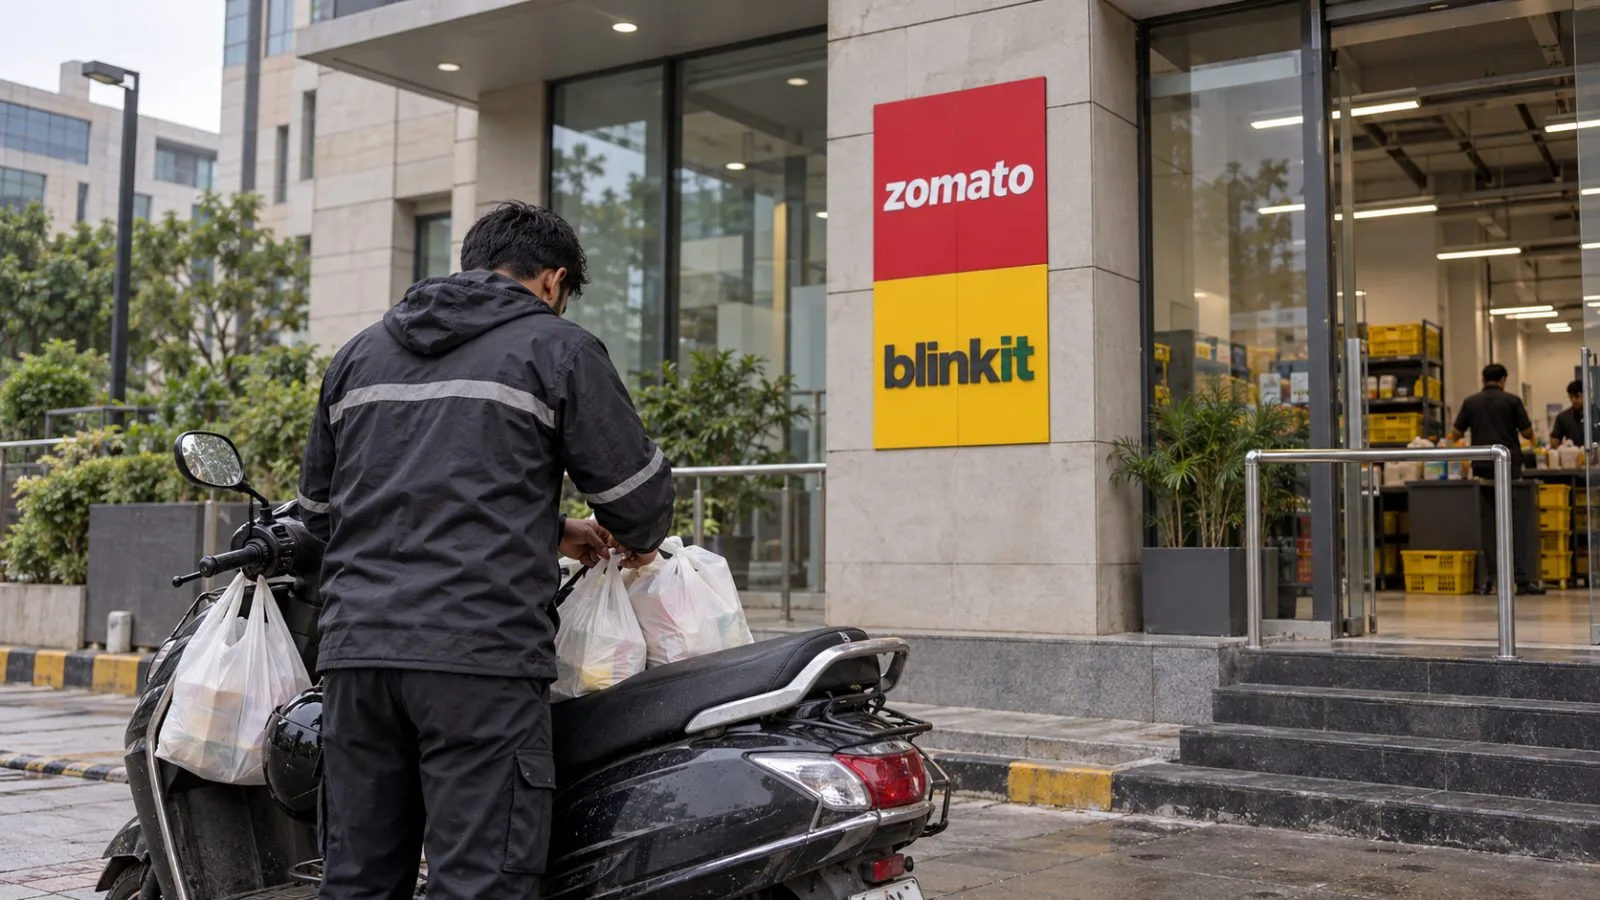
For H2 FY27, ICICI saw improved prospects for quick commerce and food delivery. It linked its quick-commerce view to a later festive season and said management planned to put surplus cash flow back into food delivery. The report cited management guidance for about 5,000 quick-commerce stores by FY28, with most new locations expected in smaller cities. ICICI said its positive view of Dark.AI reflected Eternal’s record of putting capital to work. It listed slower discretionary spending and operational disruptions from external factors among the risks, and pointed to second-half trading and store expansion as indicators for its outlook.