


 ECB May Stop Rate Hikes After December, Capital Economics Says
 RBI Raises Repo Rate to 5.50% in Hawkish Shift on Inflation Risks
 Oil Prices Dip Slightly Amid Focus on Russian Sanctions and U.S. Inflation Data
 Gold Prices Slide as Rate Cut Prospects Diminish; Copper Gains on China Stimulus Hopes
 FxWirePro- Major Crypto levels and bias summary
 FxWirePro- Major Pair levels and bias summary
 FxWirePro: NZD/USD attracts selling interest, vulnerable to more downside
 FxWirePro: EUR/AUD recovers some ground but outlook is bearish
 European Stocks Rally on Chinese Growth and Mining Merger Speculation
 2025 Market Outlook: Key January Events to Watch
 AUD/JPY Holds Above 110.00: Buying the Dip for a Potential Rally Toward 112.00
 Yen Sinks as BOJ Rate Hike Fails to Impress Markets
 FxWirePro: GBP/NZD bulls loosen their grip a bit, dips to be bought
 RBA Set for September Rate Hike as Inflation Stays High
 Wall Street Analysts Weigh in on Latest NFP Data
 Fed’s Hammack Says Bond Yield Surge Is Not Driven by Inflation Fears


 Add as a preferred source on Google
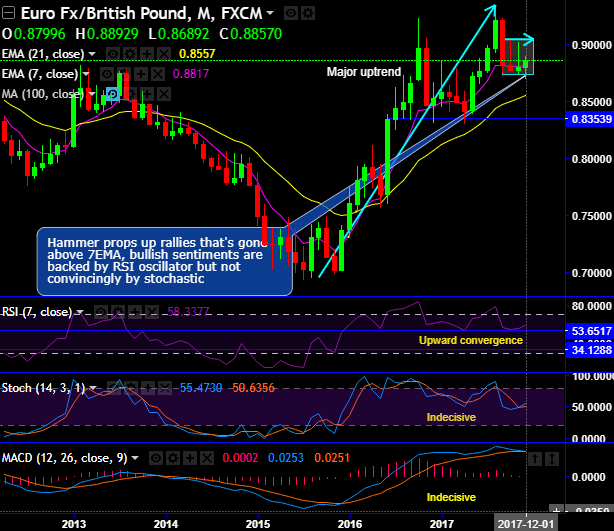
The sterling has continued its consolidation phase, so is the case with EURGBP but in a narrow range so far (0.9032 – 0.8689 range from last 3 months or so). In this the holiday period, we sit in the middle of this range approximately. Going forward, prevailing Brexit negotiations and central bank policy expectations are likely to remain the predominant driving forces of the currency pair.
As far as Brexit nego is concerned, the EU has determined that ‘sufficient progress’ has been made, such that discussion can now transform on to the future trading relationship between the bloc and the UK and any potential transition period.
Comments from Brexit Secretary David Davis and EU Chief Negotiator Michel Barnier have reinforced the challenges both sides face in coming to a comprehensive agreement.
On the interest rate front, we expect the Bank of England (BoE) to proceed cautiously, following its 25bp hike in November. We anticipate the next hike in UK Bank rate to be in August 2018.
In contrast, we see the European Central Bank (ECB) leaving interest rates unchanged next year, although it is likely to wind down its asset purchase programme. The market also needs to be wary of the Italian election, which represents a key political risk. Polls currently suggest a hung parliament is most likely.
Contemplating all these factors, we could foresee the cross retains a mild bull bias for a gradual but choppy move towards the 0.8950-0.9025 range highs. Currently, pair pops up with bearish patterns such as shooting stars on monthly plotting.
A decline back through 0.8850/0.8800 would negate this bias and risk a return to retest support in the 0.8725/0.8690 region. Medium term, the 0.8250 to 0.9415 range remains in play.
Long term, we still risk a re-test and break of the 2008 highs at 0.9802. The decline through 0.9300 and 0.8500 decreased that risk, leaving us in the middle of the medium-term range.
OTC outlook and options strategy:
The implied volatility of ATM contracts for near month expiries of EURGBP is spiking at around 6.25-7.31% for 1-3m tenors, while risk reversal signals bullish risk sentiments remain intact. During lower IV environment among G10 FX space, call option holders of lengthier tenors bidding bullish neutral risk reversals are interpreted as the optimal hedging strategic approach to arrest upside risks over the period of time. Simultaneously, capitalizing on lower IVs and any abrupt price dips, writing overpriced OTM calls with narrowed tenors is a smart move in order to hedging cost.
While the current IVs of ATM contracts are at higher levels but likely to be steady in the long run that would divulge pair’s gain contemplating risk reversal arrangements.
Hence, considering above OTC market reasoning and fundamental factors we think upside risks are on the cards, accordingly, we advocate deploying 3m ATM call option with delta being at around +0.51, while writing 1m 1% OTM calls in hedging strategies.







