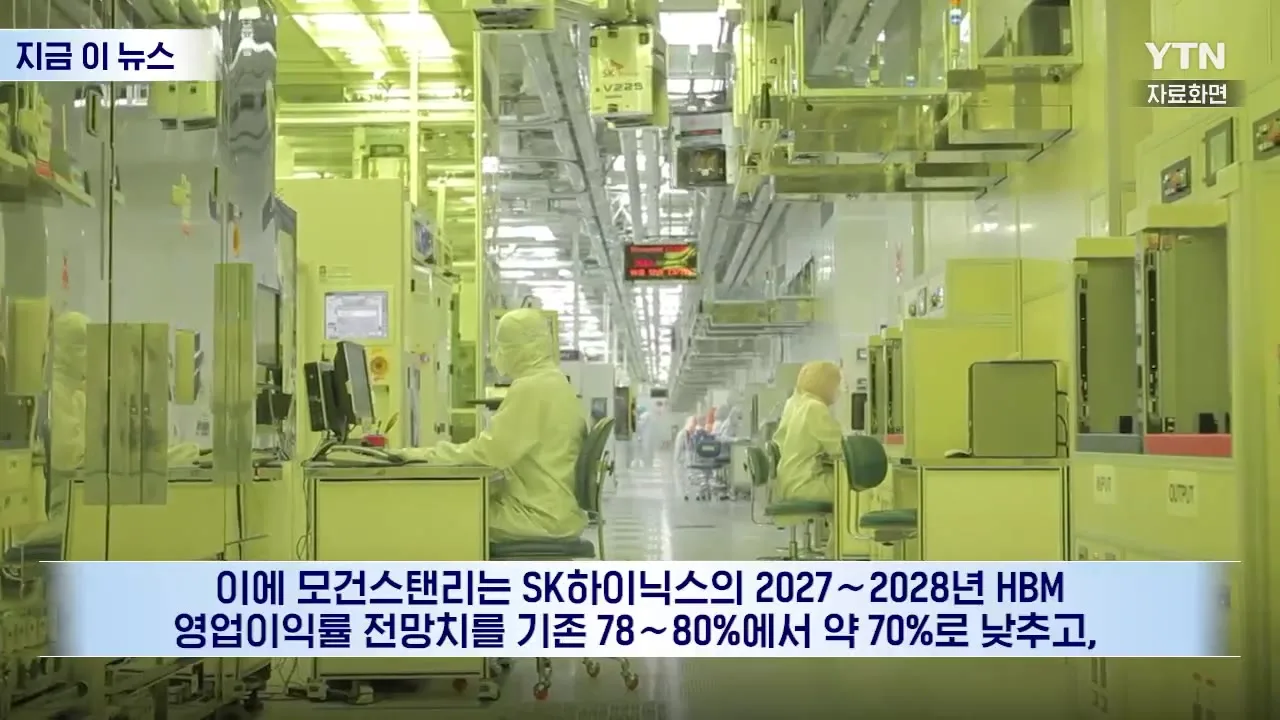
Morgan Stanley cut its target share price for SK Hynix by 38% in research released on Nov. 9, citing risks to longer-term memory chip profitability, YTN reported.
The bank raised its earnings forecasts for next year but expects new factories to increase supply as artificial intelligence data centre construction slows. It kept its Overweight investment recommendation on both SK Hynix and Samsung Electronics.
The bank lowered its SK Hynix target to 1.6 million won from 2.6 million won. It cut Samsung Electronics' target by 19% to 309,000 won from 381,000 won, and its preferred share target to 247,200 won from 304,800 won.
John Kim, an analyst at Morgan Stanley who wrote the research, focused on whether memory chip earnings could avoid a sharp fall in 2028. YTN's Now News programme carried the findings on Nov. 10.
Kim previously raised the prospect of a chip market downturn in August 2021 research titled “Memory Winter Is Coming,” translated from the supplied transcript. In September 2024, he cut SK Hynix's target by 54% and Samsung Electronics' by 28%, citing possible memory oversupply.
The current concern centres on earnings growth beyond 2028 rather than next year's profits. New production facilities are expected to start operating from late 2027, while the bank expects the pace of AI data centre construction to slow.
Morgan Stanley forecast that projects with about 5 gigawatts of capacity scheduled to start operating in 2028 would slip to 2029. Its forecast allowed for construction delays following the U.S. midterm elections.
The bank lowered its forecast for growth in new global data centre installations in 2028 to 9% from 21%. It expects growth to recover to 20% in 2029.
More memory chip supply alongside delayed data centres could ease the current shortage and push chip prices lower. Expanding Chinese production and greater competition in high-bandwidth memory, chips that move large amounts of data quickly, also threaten longer-term profitability.
The bank cut its forecast for SK Hynix's high-bandwidth memory operating profit margin in 2027–2028 to about 70% from 78%–80%. It lowered Samsung Electronics' corresponding forecast to 65%–72% from about 80%.
For next year, Morgan Stanley raised its Samsung Electronics operating profit forecast by 9% to about 688 trillion won. It increased its SK Hynix forecast by 13% to about 468 trillion won.
The lower share price targets reflected the bank's expectation that memory chip profit margins would return to historical averages after 2029. It cut its forecast for SK Hynix's average operating profit margin over 2029–2035 to 28% from 53%.
The bank said share prices anticipate changes in business performance and already reflect the risk of earnings forecast cuts over the next few years. Supply catching up with demand and slower AI infrastructure construction underpin that risk.
Samsung Electronics replaced Samsung Electro-Mechanics as the bank's preferred semiconductor industry investment. The bank judged Samsung Electronics better placed for a slowdown because it is recovering high-bandwidth memory market share and earns profits outside semiconductors.
The timing of factory openings and data centre completions remains central to the outlook. The projected delays, future margins and earnings are forecasts, leaving the eventual balance between chip supply and demand unresolved.