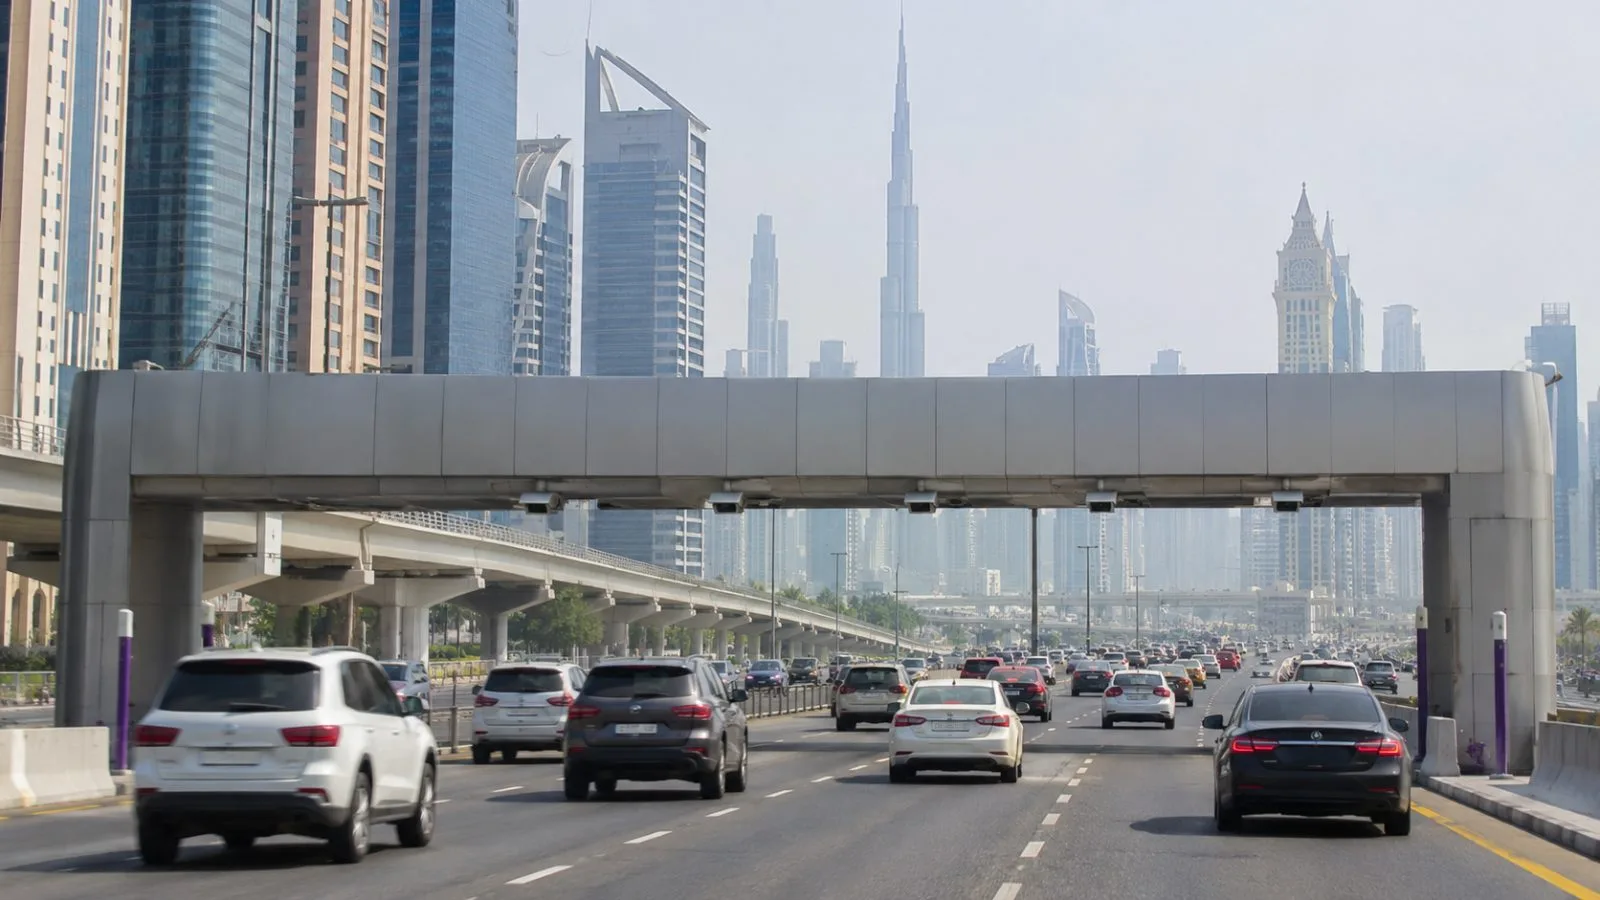
Salik reported that its toll network handled 194 million trips in the third quarter, up 4% from Q2, while nine-month profit fell 8.6%.
Salik said net profit for the nine months through Sept. 30 totaled Dh1.04 billion and revenue was Dh2,117.3 million. Compared with the year-earlier period, those figures were lower by 8.6% and 6.9%, respectively. No month since February had more trips than September. Peak-hour trips across the nine-month period were 2% higher than a year earlier.
Core toll usage fees brought in Dh1.809 billion, down 10.1% over the nine months. Fines generated Dh220.1 million, up 6.5%. Tag activation fees rose 8.5% to Dh37.7 million, and ancillary revenue increased 82.5% to Dh26.5 million, Salik reported.
Quarterly revenue reached Dh705.3 million, 3.2% above Q2 but 5.7% below the same quarter in 2025, according to Salik’s Nov. 13 results announcement. Net profit for Q3 was Dh341.1 million, 1.9% higher than in Q2. EBITDA rose 1.2% between quarters to Dh474.0 million.
Salik’s EBITDA margin was 67.2% in Q3, compared with 69.4% a year earlier. Salik cited a 23.1% concession fee, along with higher operating, maintenance and staff costs, software expenses and provider commissions. Salik said those costs were spread across a smaller revenue base.
Salik said its 2027 outlook calls for revenue growth of 6% to 8%, an EBITDA margin of 69.5% to 70.5% and a net profit margin of 50.5% to 51.5%. The company expects an inflation protection mechanism to reduce its concession fee, with inflation-related cost increases offsetting part of that reduction.
Salik said it plans cash dividends equal to all net profit, subject to a board recommendation and approval at its annual general meeting.