Tata Steel has reported higher India deliveries as the July-September earnings season begins, while PL Capital expects cost and price pressures to produce uneven EBITDA results among the metals producers it covers.
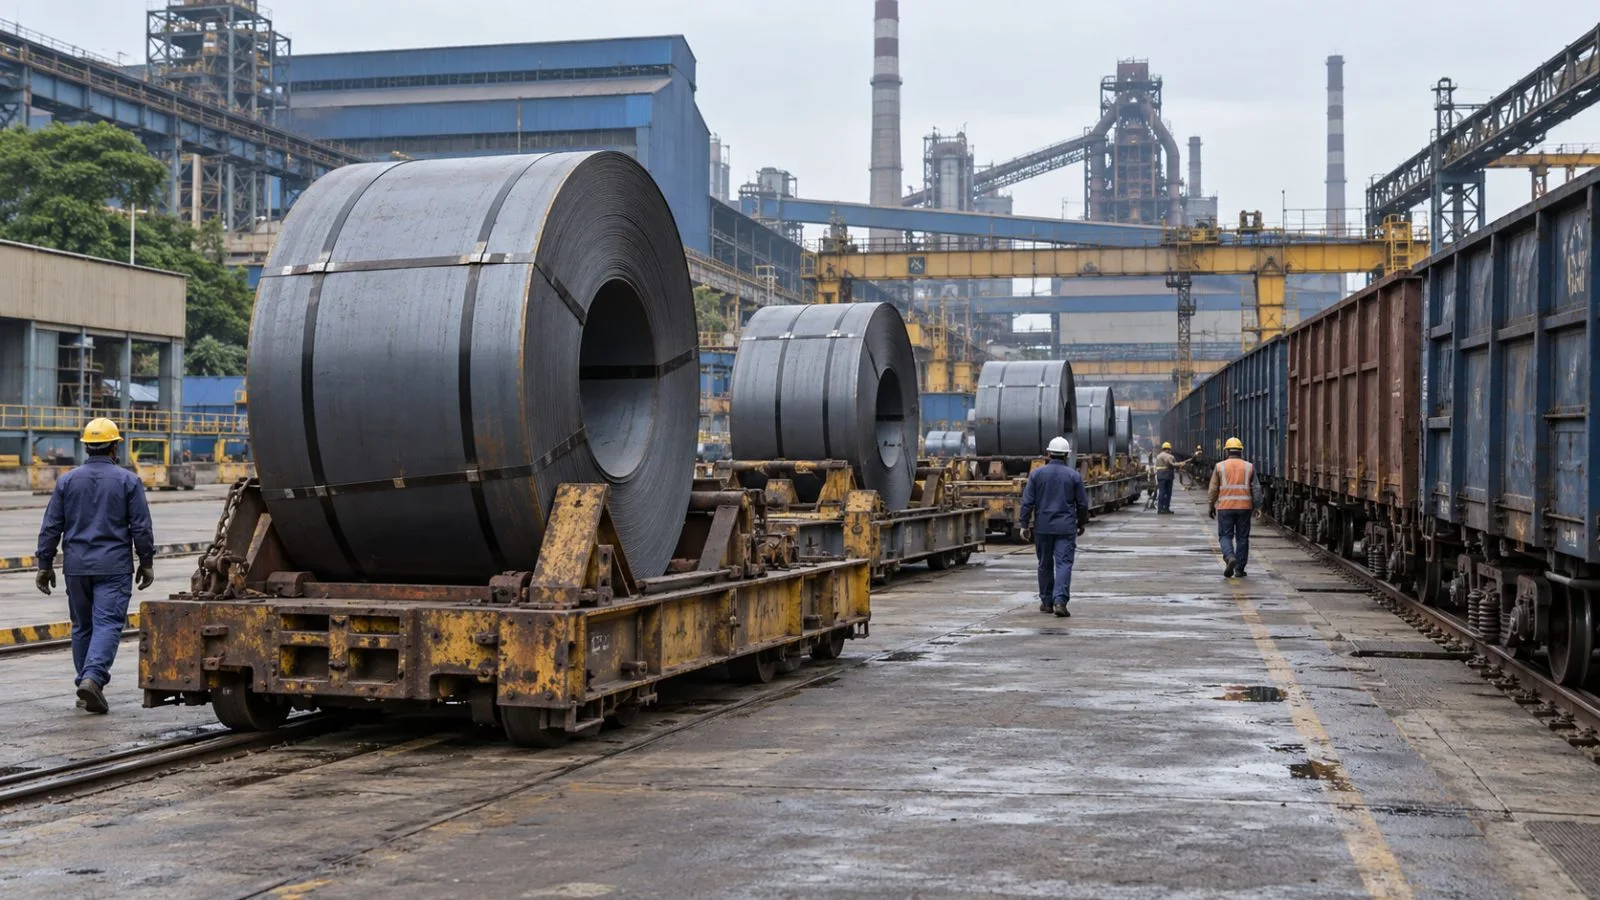
Tata Steel reported provisional India deliveries of 5.97 million tons in July-September, up 15% from April-June and 7% from a year earlier. Its India crude steel production rose 8% sequentially to 6.21 million tons. The company linked lower April-June output and deliveries to maintenance work at its Meramandali and Kalinganagar sites.
Provisional data from India’s Ministry of Steel put September finished-steel consumption at 14.4 million tonnes, 8% higher than a year earlier. Consumption for April-September reached 84.9 million tonnes, up 7.5% from the same period a year earlier.
PL Capital forecasts quarter-on-quarter consolidated EBITDA growth of 5% at Tata Steel and 3.4% at JSW Steel, while it expects a 17.2% decline at Jindal Steel. The brokerage projects standalone EBITDA at Steel Authority of India to fall 5.1%. It cites higher coking-coal costs and weaker rebar prices as pressures on steelmakers’ EBITDA per tonne. Its forecasts use consolidated figures for Tata Steel, JSW Steel and Jindal Steel, and standalone figures for Steel Authority of India. The spread in projections shows that stronger shipments do not ensure sequential EBITDA growth across the sector.
For aluminium, PL Capital estimates the London Metal Exchange average price at $3,228 per tonne for July-September, about 9% below April-June. It forecasts consolidated EBITDA down 13.5% at Hindalco Industries and standalone EBITDA down 5.6% at National Aluminium Co. The brokerage linked some of the price pressure to easing supply concerns and increased supply.
The EBITDA figures for the companies are PL Capital forecasts, not reported results. JSW Steel said its board will meet Oct. 23 to consider unaudited results for the three-month and six-month periods that ended Sept. 30.