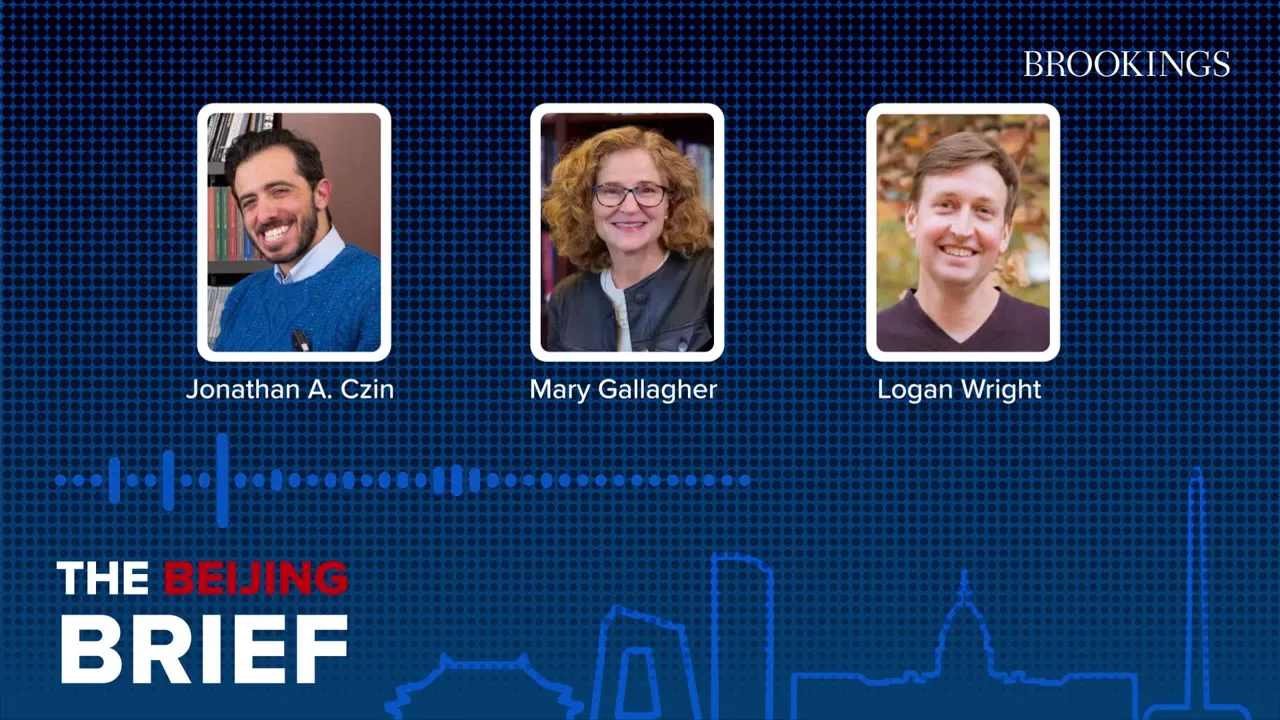
China’s borrowing boom has weakened its ability to revive growth through government spending and lending, Logan Wright, a partner at Rhodium Group who leads its China markets research, said.
Fixing the damage would require accepting slower growth while reducing the value of past investments and deciding who absorbs losses. Wright described the problem as deeper than the slowdown that economies normally experience as they mature.
Wright spoke on Brookings Institution’s The Beijing Brief podcast, in an episode titled “Is China’s economy broken?” published Nov. 3.
He rated the economy at about two on a scale of one to 10. He estimated Beijing privately sees it at roughly five while publicly presenting it as seven or eight.
Weak demand and deflation, a decline in prices across the economy, threaten its health. Past investment mistakes and bad debts have restricted the government’s ability to support activity.
Rather than allowing more businesses to fail, authorities continued lending to state-owned companies and financing companies used by local governments. Falling revenue tied to investment has spread the strain to government finances.
“There hasn’t been a rebalancing of the economy toward domestic consumption,” Wright said. That leaves China with less room to increase budget deficits or expand lending to counter a downturn.
Mary Gallagher, a Brookings nonresident senior fellow and dean of the University of Notre Dame’s Keough School of Global Affairs, described people in China as subdued and less optimistic.
She said the economy fell short of expectations, although China was not experiencing hyperinflation or bank runs. The government probably recognises its problems but projects greater confidence publicly.
Gallagher traced the difficulties to China’s response to the global financial crisis. Recessions in the United States and Europe brought export-sector layoffs, and China turned to heavy investment for another source of growth.
While living in China in 2012 and 2013, she saw a property boom support construction, furniture, home design and household spending. Reducing dependence on property therefore affected both investment and consumption.
Xi Jinping’s administration began in 2013 and addressed that dependence during its second term. Gallagher identified 2021, when the property sector came under strain, as a turning point.
Xi also launched his Common Prosperity campaign that year. Gallagher said it delivered little on social insurance but changed wealthy entrepreneurs’ view of the government and made them feel less secure.
Wright traced concerns about excessive construction, bad loans and a credit bubble to May and June 2009. Leaders nevertheless favoured stronger short-term growth and confidence, expecting to manage any damage later.
That choice gave local governments greater influence because unfinished bridges, tunnels and subway systems created pressure for continued funding. Lending also kept unprofitable businesses operating and avoided job losses.
Wright said local political interests helped sustain the investment-led model. Proposals from the Communist Party’s 2013 Third Plenum reform agenda had begun fading or being reversed by 2015.
He argued that Beijing had opportunities to change course earlier. His remarks left unresolved how authorities would distribute losses among borrowers, lenders and governments, or when they would allow more unprofitable businesses to fail.