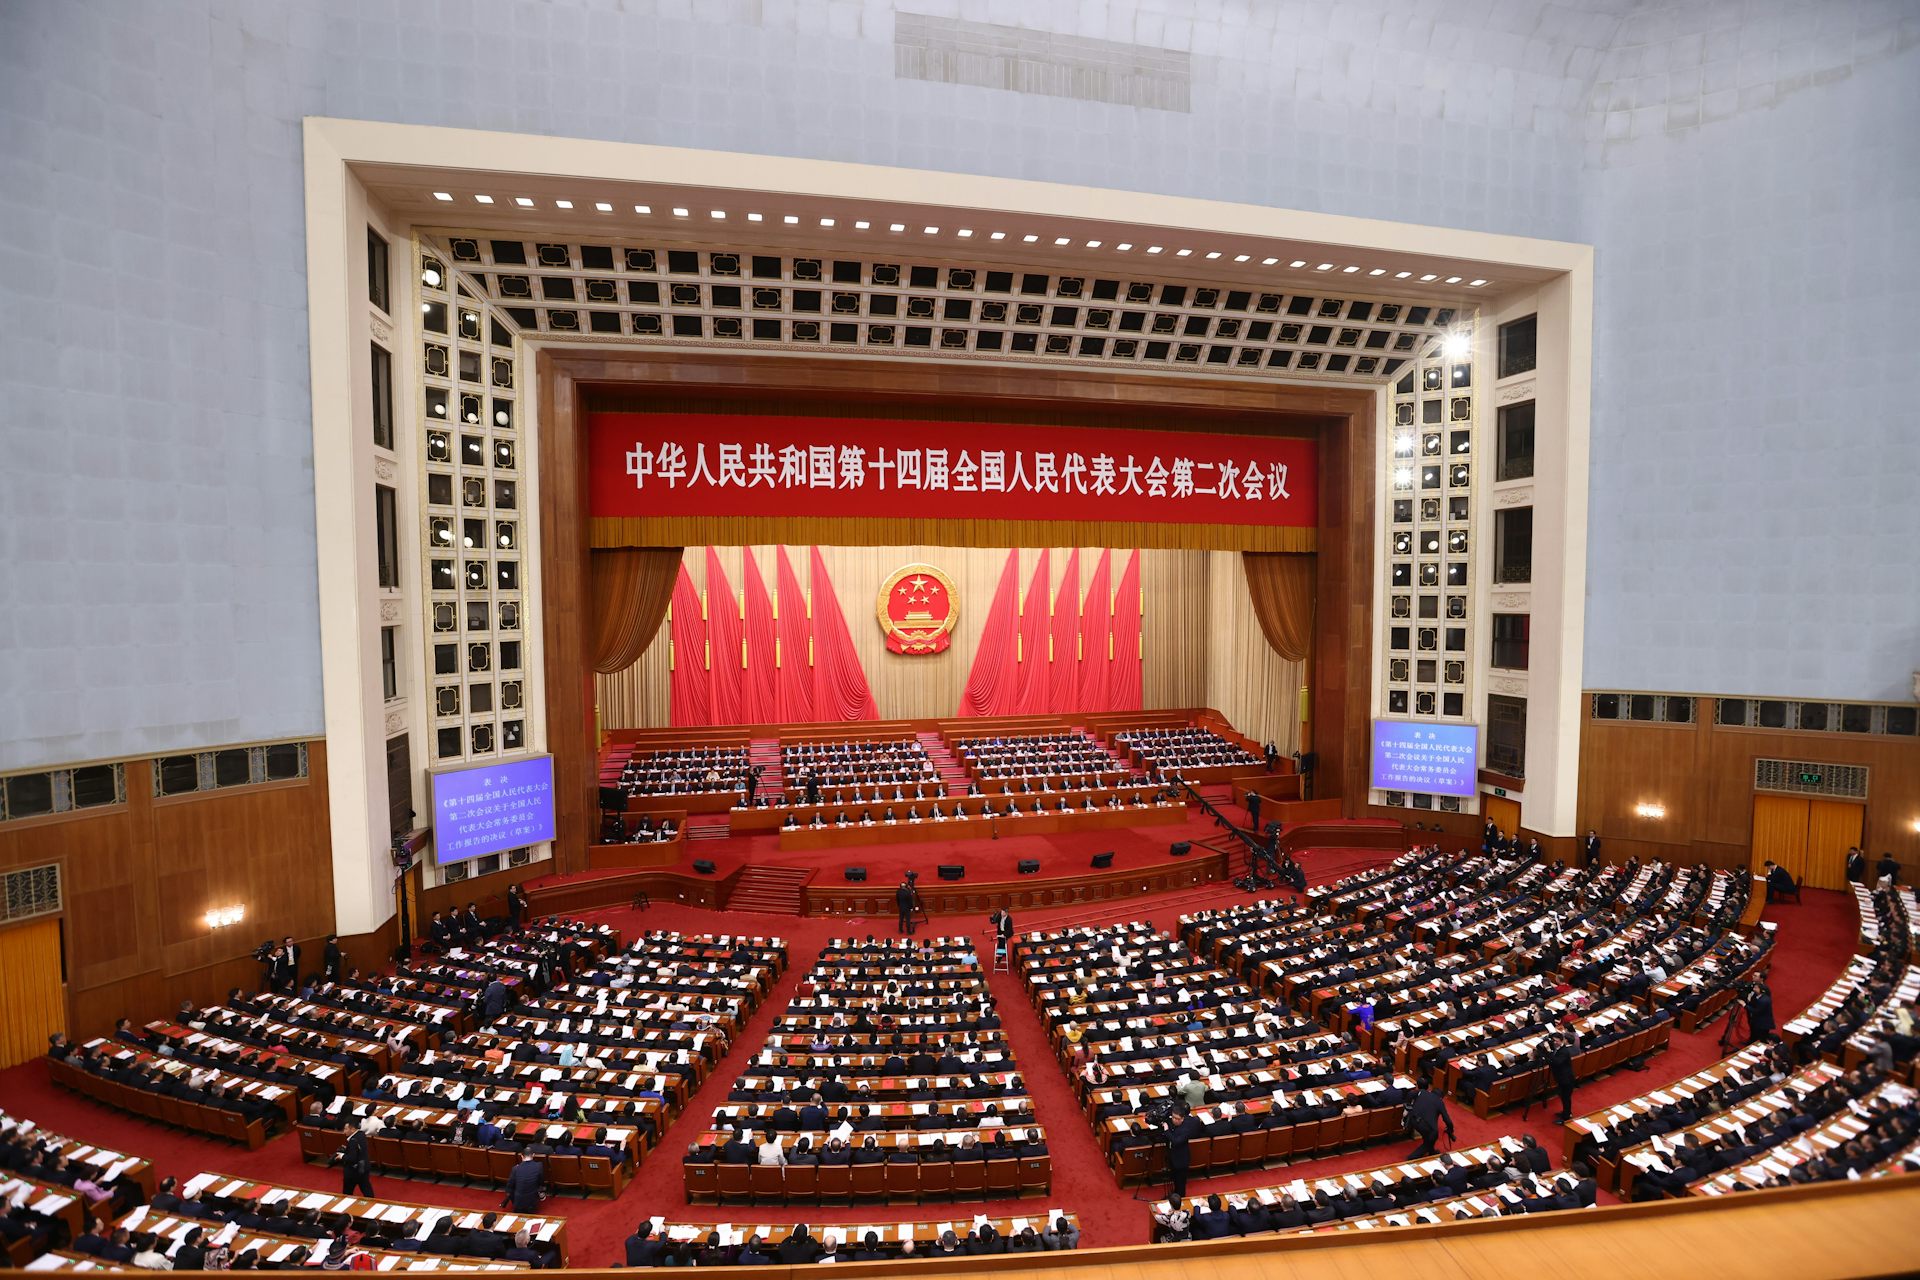
China’s annual parliamentary meetings in Beijing came to a close on March 11. They were conducted under great pressure: a weak economy and high expectations from both the domestic public and international observers as to what the government can do to get the economy out of the woods.
The country’s leaders did not shy away from mentioning all of the economic problems facing China. But they also attempted to boost the morale of the Chinese public by outlining how the country would march into the next chapter of the Chinese story – mainly by striving to become a global leader in technology.
The government used the meetings to declare that it was targeting GDP growth of 5% in 2024. This is lower than the 5.2% growth rate that was achieved in 2023 but higher than the International Monetary Fund’s forecast of 4.6%. The Chinese government did not detail how this target will be achieved, but the target itself is indicative of the leadership’s confidence about the future.
Over the past four decades, China’s rapid economic growth has been attributed to market incentives, cheap labour, infrastructure investment, exports and foreign direct investment. But at the time of writing, none of these drivers are working effectively.
Market activities are intertwined with greater state intervention. A declining population has weakened the labour supply. And uncertainty surrounding China’s economy and intensified geopolitical tensions have together driven foreign investment out of China. By January 2024, inward foreign direct investment in China was less than 10% of the US$344 billion (£270 billion) it received in 2021.
Property crisis
Many of the risks facing China’s economy stem from its ailing real estate sector. For decades, China’s economy was dependent on a booming property market driven by speculative investment returns. However, this growth was largely driven by debt. To maximise their profits, developers even began selling houses before they had been built.
China’s economy started to slow and, in 2020, Chinese regulators cracked down on reckless borrowing. Beijing imposed widespread lending curbs on property developers, meaning they could not borrow more money to pay back their existing debts.
A crisis followed. In early 2024, Evergrande – the world’s most heavily indebted real estate developer – went bust. And other large property developers are in trouble. Country Garden has defaulted and Vanke is struggling to find the new loans it needs to stay alive.
The government confirmed its determination to deflate the property bubble in its annual meeting. It did not highlight how to protect more property developers from defaulting, and only hinted at giving some help to allow developers to complete property projects.
The current weak consumer demand in China’s economy is closely related to the real estate crisis. The value of houses is much lower today than it was two years ago, creating fear about the future value of personal wealth. This has prompted more precautionary saving and less consumption in the face of weak social protection, leading to a general decline in the price of goods and services.
Demand for Chinese goods from abroad has also been declining due to trade restrictions imposed by the US and the EU, geopolitical concerns and shocks to global supply chains. This explains why throughout its annual meetings the government explicitly emphasised the need to strengthen the self-reliance of the Chinese economy.
New drivers of growth
The most eye-catching phrase to come out of the annual meetings was “new quality productive forces”. There are varying interpretations of the term, but they all focus on technology and innovation.
Chinese officials explicitly highlighted the need for China to strive to invent more products related to Artificial Intelligence (AI). The government envisions applications such as AI-powered travel agents and salespeople.
China has, up to this point, been better known for applying AI technologies. Beijing, Shanghai and Shenzhen are all smart cities, where advanced technologies such as AI, cloud computing and big data are used in various areas including transport, urban planning and public security.
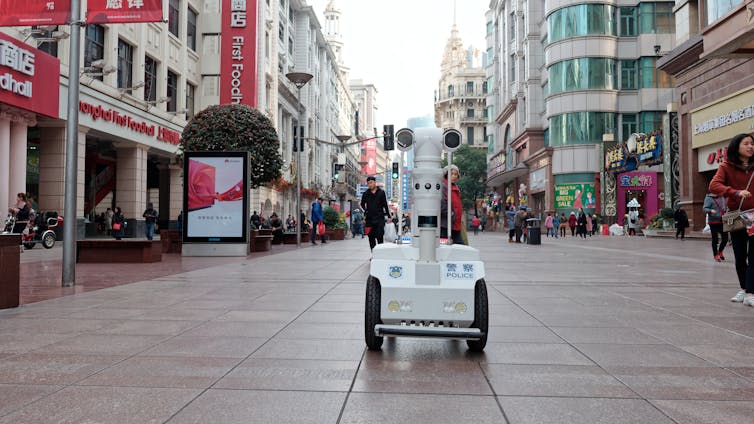
Shanghai’s first robot police officer patrolling the streets in 2019. atiger/Shutterstock
However, transforming China’s economy from one that is driven by investment and fuelled by debt to one that is driven by innovation and technology will bring some fresh challenges.
First, innovation requires incentives and an institutional guarantee to reward risk-taking. Hence, the private sector needs to grow faster. Research has found that the share of China’s private sector among the 100 largest listed companies in China dropped to 36.8% at the end of 2023 from 55.4% in mid-2021.
Second, innovation requires more highly skilled human capital. A report by the OECD in 2021 concluded that the application of AI technology increases the demand for skilled employees, despite replacing low-skilled labour. This will pose a challenge for China as, up to this point, the country’s growth has been spurred by low-skilled labour.
Third, high-tech industries such as AI and digital services are energy intensive. China has already taken steps to diversify its energy supply, but securing energy supply chains will be essential in the longer term.
Heightened geopolitical tensions and revamped global supply chains may well reduce exports of energy and other natural resources to China in the future. Many of these resources come from developing economies that have exchanged their resources for China’s infrastructure investment in the past. This unlikely to be the case in the future.