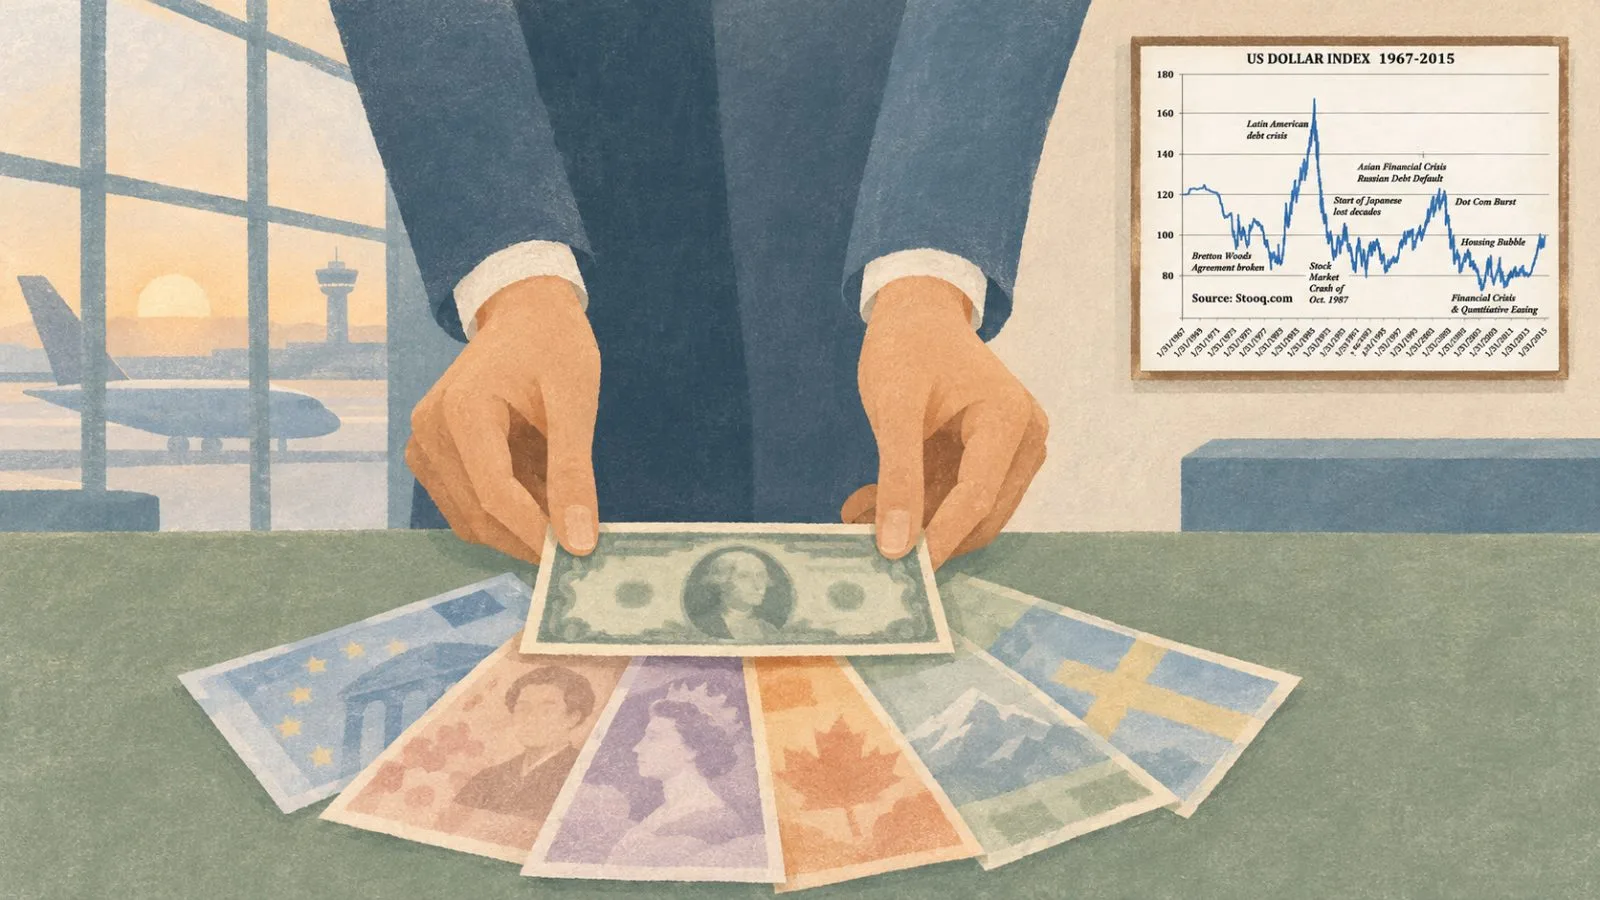
The U.S. dollar index was at 101.88 on Monday, Reuters reported, as Tuesday’s U.S. inflation release approached and MUFG Research analyst Lee Hardman linked stronger hiring to inflation concerns.
Hardman’s Nov. 9 note described an earlier move above 102 overnight, after the index touched 101.10 on Nov. 4 following U.S. midterm election results. Reuters reported that its Monday reading had fallen 0.3%.
Hardman argued that the dollar’s rise had outpaced short-term yield spreads and that a hawkish inflation surprise might be needed to sustain its strength. He said stronger employment growth had made upside inflation risks a greater consideration for the Federal Reserve. That was Hardman’s analysis, not a statement from the central bank.
The Bureau of Labor Statistics (BLS) reported that nonfarm payrolls grew by 165,000 in October. The unemployment rate was 4.1%, and average monthly job growth over the preceding 12 months was 48,000. Revisions lifted August and September payroll gains by a combined 84,000.
Average hourly earnings for private-sector workers rose 14 cents to $38 in October, a 0.4% increase for the month and 3.1% over the year. Hardman said labor-force growth and the annual wage pace suggested that pressure in the labor market remained contained despite stronger hiring and economic activity.
The BLS is scheduled to release October’s Consumer Price Index (CPI) report on Tuesday, Nov. 10, at 8:30 a.m. ET. MUFG cited a consensus estimate for core CPI to rise 0.2% from the previous month. In September, headline CPI increased 0.6% for the month and 3.7% over 12 months; core CPI rose 0.3% monthly and 2.6% annually.