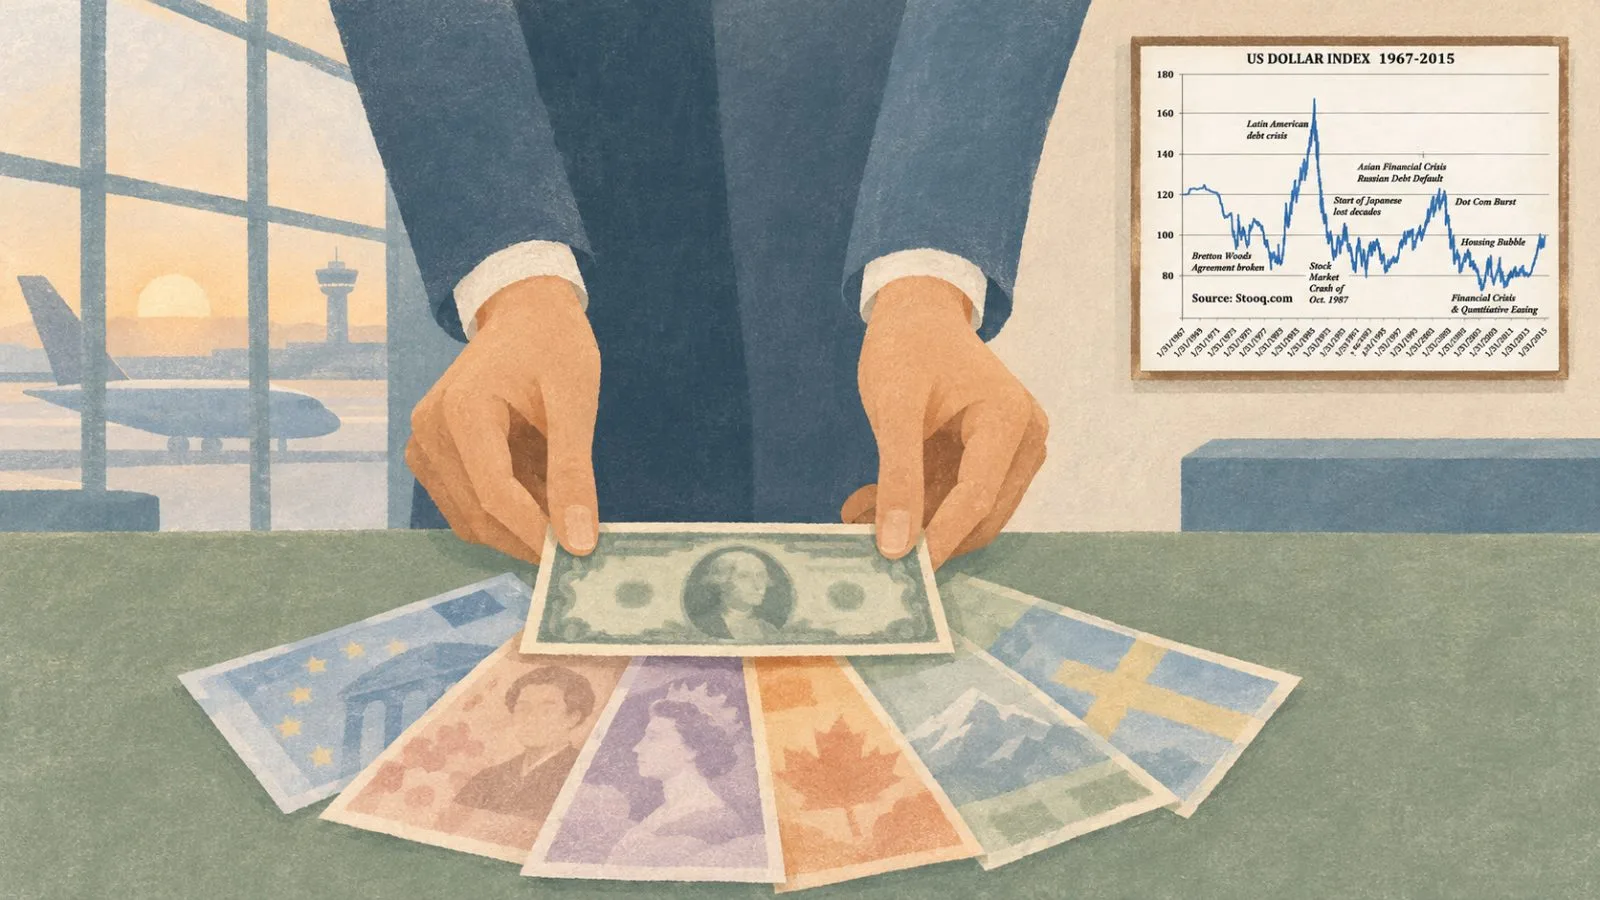
The U.S. Dollar Index (DXY) fell below 103 on Nov. 12 after FXStreet reported an earlier 103.08 high, putting the dollar’s recent gains and the Federal Reserve’s December rate outlook in focus.
FXStreet’s update at 5:25 a.m. ET (10:25 UTC) put the index near 102.80. Reuters reported a separate earlier high of 102.88, followed by a reading near 102.80; the outlet described its reported high as the strongest since April 2025.
Reuters linked the dollar’s earlier gains to a more hawkish market reassessment of Federal Reserve policy after inflation data, alongside a sharp rise in short-dated U.S. Treasury yields. FXStreet also cited Commerzbank analysts who pointed to rising U.S. equities and semiconductor shares, amid renewed optimism about artificial intelligence, as support for the dollar.
The index had traded near 102.20 in Asian trading Wednesday, as EconoTimes previously reported in its coverage of dollar gains and Fed rate expectations.
The U.S. Bureau of Labor Statistics (BLS) said consumer prices rose 0.4% in October from September, after a 0.6% increase the previous month. The core measure, which excludes food and energy, recorded a 0.3% monthly increase for a third consecutive month.
Before the CPI release, Federal Reserve Governor Christopher J. Waller said he leaned toward a 25-basis-point increase at the December meeting. He said officials should consider a 50-basis-point increase if October CPI data resembled the prior two months, with core inflation around 0.3% or higher. October’s core reading was 0.3%.
The Federal Open Market Committee’s next scheduled meeting is Dec. 8-9. BLS has scheduled its November CPI release for Dec. 10 at 8:30 a.m. ET.