


 Trump’s "Shock and Awe" Agenda: Executive Orders from Day One
 US Gas Market Poised for Supercycle: Bernstein Analysts
 U.S. Stocks vs. Bonds: Are Diverging Valuations Signaling a Shift?
 Oil Prices Dip Slightly Amid Focus on Russian Sanctions and U.S. Inflation Data
 Bank of America Posts Strong Q4 2024 Results, Shares Rise
 Moody's Upgrades Argentina's Credit Rating Amid Economic Reforms
 Wall Street Analysts Weigh in on Latest NFP Data
 UBS Projects Mixed Market Outlook for 2025 Amid Trump Policy Uncertainty
 Moldova Criticizes Russia Amid Transdniestria Energy Crisis
 Indonesia Surprises Markets with Interest Rate Cut Amid Currency Pressure
 China's Refining Industry Faces Major Shakeup Amid Challenges
 Global Markets React to Strong U.S. Jobs Data and Rising Yields
 U.S. Treasury Yields Expected to Decline Amid Cooling Economic Pressures
 S&P 500 Relies on Tech for Growth in Q4 2024, Says Barclays
 UBS Predicts Potential Fed Rate Cut Amid Strong US Economic Data
 US Futures Rise as Investors Eye Earnings, Inflation Data, and Wildfire Impacts
 Lithium Market Poised for Recovery Amid Supply Cuts and Rising Demand


 Add as a preferred source on Google
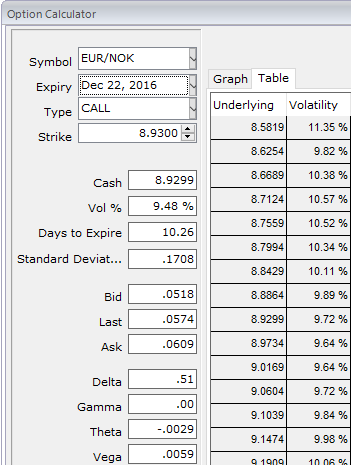
In the Scandi FX sphere, EURNOK to get an extra impetus as the major focus for this week would be the Norges Bank (NB) meeting on Thursday after recent OPEC's booster, where we expect NB to lower its rate path for 2017 by 10-15bp and thereby imply almost a 100% probability of a rate cut next year.
We do not expect NB to cut further and we think that a dovish rate path along with the usual worsening of the liquidity situation going into end year could lead to some temporary upside support in EURNOK – especially after the past couple of days’ decline on the back of the OPEC deal.
All these factors leave us structurally bullish on NOK which we are positioned for outright via short EURNOK outright.
This week the central bank confirmed that it will keep rates on hold. The key sentence from the Norges Bank’s statement is that ‘overall developments since September do not differ substantially from the projections in the September MPR’.
This was a relief for NOK as it indicates that the central bank is not over-reacting to the decline in inflation (core is 0.35% lower than the NB had expected). The key risk for NOK will now be the OPEC meetings and the currency has underperformed this week amid lower oil prices.
In terms of EURNOK, we now see good chances of challenging the countertrend rally target at 9.6100/9.6275.
10D EURSEK ATM implied volatility are spiking considerably on account recent ECB’s monetary policy announcement and ahead of Swedish inflation data, it is just a tad below 9.5% which is quite conducive for both option writers and holders as we could see short-term upswing possibilities and medium term bearish risks.
We know that the option contracts with a higher IVs would be expensive. This is intuitive due to the higher likelihood of the market ‘swinging’ in your favor. If IV increases and you are holding an option, this is good. Unfortunately, if you have sold an option, it is bad. Option writer wants IV to shrink so the premium falls. You should also note short-dated options are less sensitive to IV, while long-dated are more sensitive.
Hence, we advocate diagonal credit put spreads to monitor swings on either way, to execute this option strategy one can short 1W (1%) ITM put while buying 1M (0.5%) OTM put option; the strategy could be executed at a net credit.







