


 RBNZ Raises Interest Rate to 2.75%, Kiwi Dollar Slides
 JPMorgan Sees ECB Raising Rates to 2.75% in December
 Gold Surges Past $4400 on Crude Oil Rally; Bullish Trend Dominates
 Bank of Korea Raises Rates to 3% as Inflation Stays Sticky
 Citi Sees Signs of Shift in Global Currency Policy
 ECB Rate Hike Bets Rise as Inflation Risks Persist
 Yen Extends Gains as BOJ Rate Hike Bets Rise
 Central Banks Could Buy 20,000 Tonnes of Gold: BofA
 Bank of England Sees Surge in Higher-Risk Collateral


 Add as a preferred source on Google
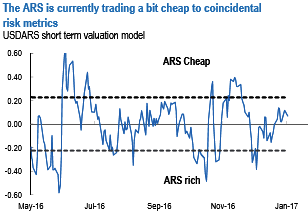
We encourage holding longs in ARS, short USDARS. The peso is currently trading a bit cheap to coincidental risk metrics (refer above chart), helped by soy prices, the positive real rate enforced by the Central Bank to prevent further inflation expectations de-anchoring, and high agricultural export proceeds for the season of the year.
The trade balance posted a US$2.1bn surplus in 2016, a sharp turnaround from the US$3.0bn deficit in 2015.
Imports contracted US$4.1bn last year, explaining 81% of the swing in the trade balance.
2016 primary fiscal deficit (ex.-tax amnesty fiscal inflows) was 6.0% of GDP, well above our 5.0% forecast.
Short USDARS, we remain constructive on ARS and continue to recommend selling 3m and up to 6m USDARS NDF as one of the few carry trades where we expect the positive total return.
The recent macro news supports this outlook, as our nowcaster suggests that Q4’16 GDP expanded by 5% QoQ SAAR, materially better than our prior 3.2% forecast.
Stay short in USDARS via 6-month NDF (sell at 15.86).







