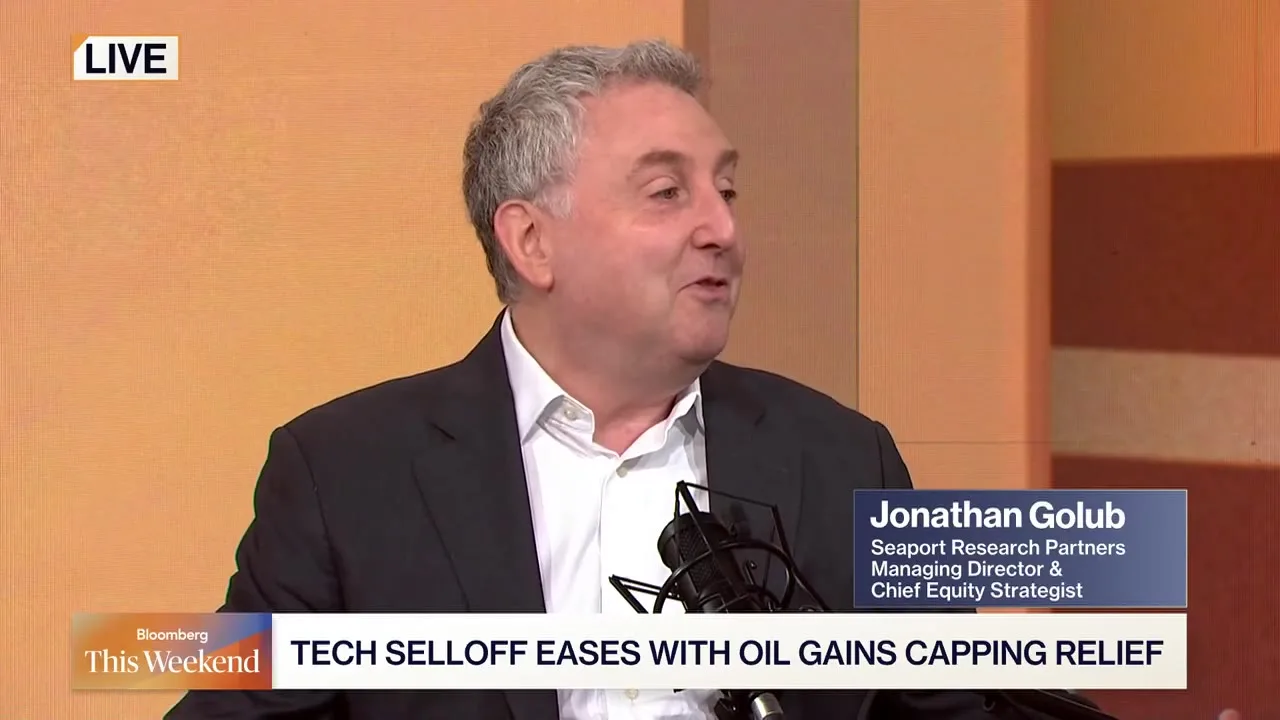
Oil prices will stay elevated as prolonged US involvement around Iran feeds inflation and eventually forces a Federal Reserve response, Seaport Research Partners chief equity strategist Jonathan Golub said.
That outlook challenges expectations that cheaper oil will reduce energy companies’ profits next year. Golub argued that higher fuel costs also reach consumers through prices for goods, extending their effect beyond petrol purchases.
In an interview on Bloomberg Television published Oct. 24 under the title “Persistent Oil Prices Threaten Inflation Outlook,” he also rejected suggestions that stocks were in a bubble.
“We're not in a bubble,” Golub said, estimating that S&P 500 earnings had risen 32% to 33% this year while its valuation multiple had fallen about 18%. That multiple measures the price investors pay for a dollar of earnings.
Higher interest rates made stocks less attractive, while investors questioned whether recent investment trends could last. Falling multiples showed that investors were paying less for earnings despite rising share prices.
The broad market’s roughly flat performance for the month concealed much larger shifts between industries. A retail investor might see a loss of only a quarter of a percent, while professional investors confronted a 15% semiconductor decline.
Healthcare and consumer staples had risen sharply, while industrial and materials companies, whose businesses benefit from economic growth, had performed less well. Those shifts were creating concern among professional investors.
Samsung and Micron traded below 10 times earnings, illustrating skepticism toward memory-chip companies despite their share gains. Greater optimism would put such valuations at 30 times earnings, in his comparison.
Technology, broadly defined, accounted for about half the S&P 500. Adding power suppliers, data-centre builders and companies mining copper for components put the share connected to artificial intelligence at roughly 70%, by his estimate.
He estimated that those businesses accounted for about 95% of the index’s daily fluctuations. That made artificial intelligence far more dominant in the stock market than in everyday economic activity.
On cryptocurrency, he questioned its practical uses beyond trading and declined to offer a bitcoin outlook. He described himself as the wrong person to assess that market.
Turning to energy, he expected prolonged US involvement around Iran even without extensive shooting between the countries. A US departure could lead Iran to close the straits again, in his assessment.
Energy companies’ earnings were growing more than 100%, benefiting the broader index even as consumers paid more for fuel. Expectations of falling profits next year rested on assumptions that oil would become cheaper.
Higher diesel costs also raised delivery expenses for products such as furniture. Manufacturers could absorb those costs initially and pass them to customers later, keeping oil’s effects in underlying inflation even when direct energy prices are excluded.
Recent inflation readings had exceeded expectations, while the extra interest investors demanded to hold riskier corporate debt had widened over the past month or six weeks. He interpreted that gap as concern about eventual monetary tightening.
He expected tighter borrowing conditions to strain households and cause small-business defaults. He gave no timetable or size for a Federal Reserve response, leaving the policy path open.