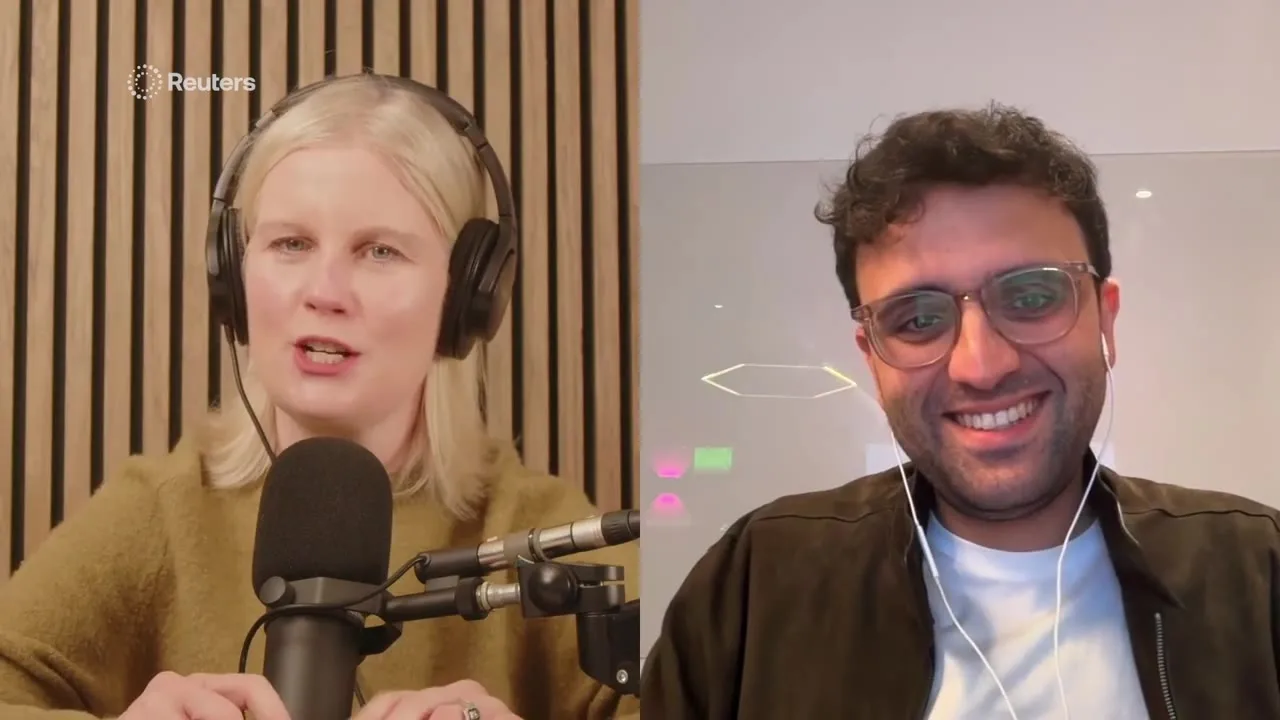
Kalshi's co-founder and chief executive said prediction markets give people an incentive to gather information and help manage financial risks, in a Reuters Econ World interview published Oct. 21.
He defended contracts on entertainment and sports alongside those on economic events, saying their usefulness extends beyond speculation. His remarks presented the platform operator's case for its own business.
The chief executive traced the idea behind Kalshi to his internship at Goldman Sachs in 2016. He said clients wanted to trade on events such as Britain's vote to leave the European Union and the U.S. presidential election.
Investors used conventional financial assets to express those views, he said, but those assets did not always move as expected when the predicted event happened.
He described investors who correctly anticipated Donald Trump's election victory but lost money betting that U.S. stocks would fall. He said such trades were indirect, their pricing was opaque and access was limited.
Kalshi's alternative was an exchange where buyers and sellers could trade directly on whether an event would happen, he said. The questions could cover weather, economics, politics or sports.
The chief executive said the economic argument rests on markets' ability to combine knowledge held by many people. Traders bring information into prices when they buy or sell based on their expectations.
“They give an incentive for people to go out there in the wild and do research or acquire knowledge,” he said. He described the resulting information as a public benefit.
Asked how contracts on celebrity appearances or television competitions served that purpose, he said trading offered people a way to resolve disagreements about outcomes.
“I think trading is a much more objective rational way to resolve these questions,” he said.
He acknowledged that some contracts have a clearer economic purpose and affect more people than others. Markets on inflation or hurricanes offered more obvious uses, he said.
Sports outcomes could also matter to advertisers and others whose investments depend on a team's progress, he said. Entertainment contests interested a smaller group of people who closely followed the results.
He said some participants speculate while others use contracts for hedging, taking positions to offset a financial risk. Speculators provide the other side of those trades, he said.
The supplied interview excerpt ended as a question began about public opposition to election betting. It contained no response to that question or answers on regulatory resistance and market manipulation, topics introduced at the programme's opening.