South Korea plans to require businesses to set aside retirement-benefit funds outside their companies, beginning with workplaces of 100 or more employees in 2028 and expanding in stages through 2030. The Ministry of Economy and Finance said.
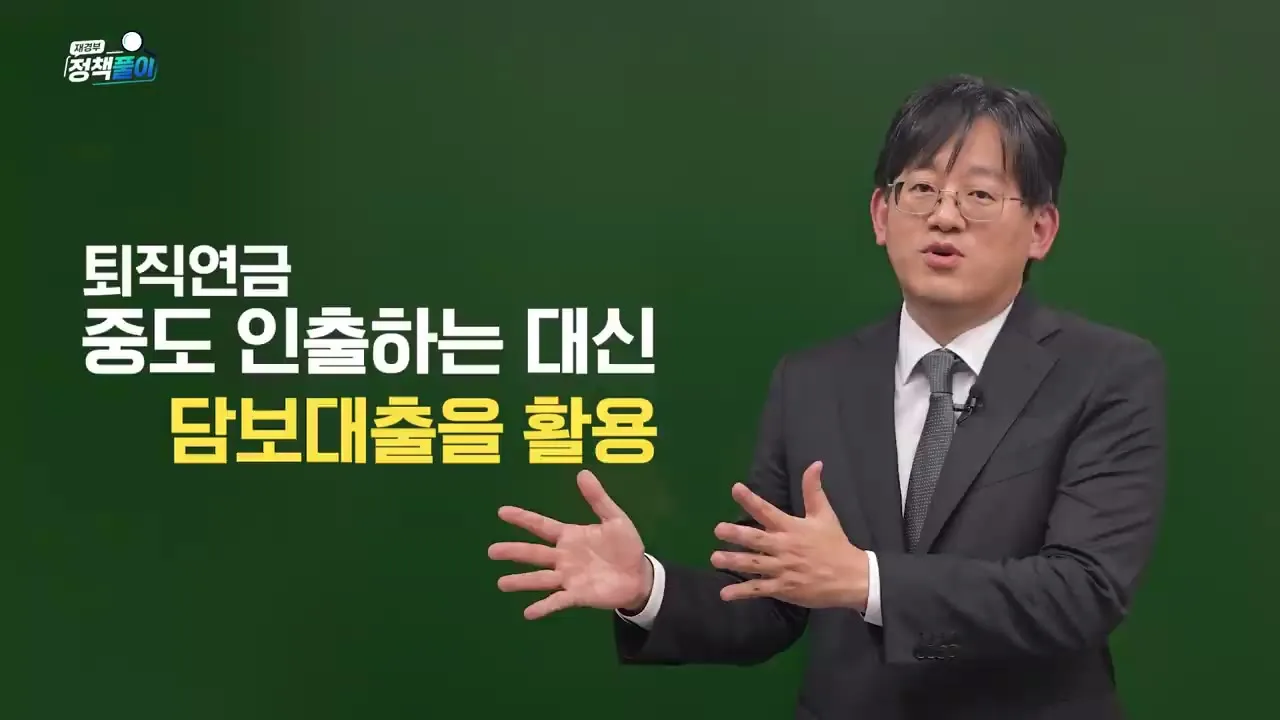
The ministry announced the plan in an episode of its policy programme, “How to reduce worries about unpaid severance pay,” published on Nov. 19. The measures require legal amendments and would apply to work periods beginning after each stage takes effect.
More than 800 billion won in severance pay went unpaid in 2025, the ministry said. Keeping retirement funds separate from company money is intended to reduce the risk that employees will not be paid when an employer faces financial trouble.
The programme explained that a severance-pay system requires a company to pay workers when they leave, while a retirement-pension system sets aside the money in advance with financial institutions. The ministry said all businesses would eventually have to fund retirement benefits outside the company.
The government also plans to expand fund-based retirement pensions, in which a professional institution manages pooled savings. The option would supplement direct investment choices for defined-contribution plans and individual retirement pension accounts, where workers must choose products themselves.
Professional management may improve returns, but it would not guarantee profits, the ministry said. Investment gains and losses would still belong to account holders. The planned framework would put members’ interests first, strengthen supervision and distinguish normal investment losses from losses caused by a manager’s breach of legal duties.
Lump-sum payments would remain available, although the government is considering a system that compares projected lump-sum and annuity payments in advance and pays an annuity unless a worker chooses a lump sum. In 2025, 83.5% of accounts receiving retirement benefits were paid in a lump sum.
The ministry is also pursuing legal changes allowing secured loans against retirement pensions instead of early withdrawals when workers need money for a home purchase or another large expense. Borrowers would need to compare interest and repayment terms once products become available.
Workers were advised to check whether their employer uses a severance-pay or retirement-pension system, whether a pension is defined-benefit or defined-contribution, and the products, returns and fees in defined-contribution or individual accounts. Those nearing retirement should compare lump-sum and annuity payments and check official guidance for implementation dates.