


 What is Zionism? The different meanings of a contested term
 Gold Slides to $4,262 as Hawkish Fed Rate Hike Triggers Technical Breakdown
 ‘Buy now, pay later’ doesn’t feel like debt. For young people, that can be a big problem
 China’s robots can run faster than Usain Bolt – now they are being prepared for war
 Big AI wants to slow down AI research. Is it a safety pause or a strategic retreat?
 Europe can’t achieve space sovereignty alone. Here’s why
 Who should own the knowledge that underpins AI technology?
 Synthetic data could ease people’s concerns about privacy breaches. But who gets to create it?
 AI is supercharging money scams – here’s what you can do to protect yourself


 Add as a preferred source on Google
The timing of a rise in interest rate has been a double-crossing theme. Yet bond sell-offs arise, badly hurting fixed income and global macro portfolios.
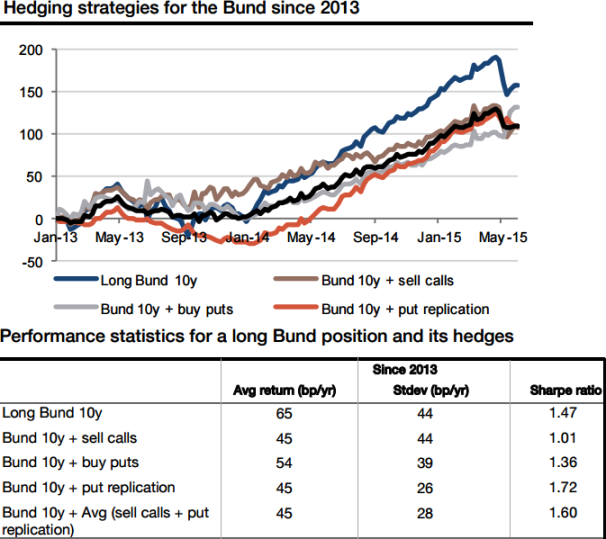
What relief can be found in systematic strategies? To what extent does the premium paid for insurance against interest rate rises erode a fixed income portfolio performance?
The option market maker who sells options and hedges position on a regular basis as the trend follower is in the same position.
When the asset deviates from the strike and when the delta of its position increases, the option hedger will buy more of the underlying asset.
The graph demonstrates the total performance in bps equivalent (i.e. the gain in basis points) of an outright long position in 10y German Treasuries and the combination of this long position in 10y German Treasuries and one of the three systematic strategies given in the nutshell.
The black line indicates the performance for a long position in German Treasuries, combined with a put replication strategy and a programme selling receivers on 10y rates.
Here, in German bond market case, Gap risks such as the one witnessed in April/May will remain unhedged as the German bond yields have been performing well.
But the traders who are risk averse can still prefer any of the combined strategies according to the circumstances.

- News

- Economy

- Central Banks
- Investing
- Research
- Roundups
- Digital Currency
- Insights
- Technical Analysis
- Technology
- Business
- Law
- Health
- Nature
- Fintech
- Science
- Topic
- Opinions
- ©Econometrics LLC . All Rights Reserved.
Trade laggards can deploy momentum strategies on German treasury bonds
Wednesday, June 10, 2015 6:53 AM UTC
Editor's Picks



- Market Data
Most Popular




