


 Oil Prices Rise as Hormuz Risks Offset IEA Stock Release
 US Dollar Rises for Fourth Week as Fed Rate Hike Bets Grow
 Asian Currencies Steady as Dollar Eyes Fourth Weekly Gain
 Mike Rogers Calls for End to US-Canada Tariff War
 FxWirePro: Daily Commodity Tracker - 21st March, 2022
 Asian Stocks Mixed as OpenAI Revenue Concerns Hit Chipmakers
 Best Gold Stocks to Buy Now: AABB, GOLD, GDX
 Oil Prices Rise as Gulf Hurricane and Middle East Supply Risks Mount
 US Dollar Near 18-Month High Ahead of Inflation Data
 Trump Calls for Zelenskyy Replacement Amid Russian Diesel Deal
 US, EU Push for Action Against Asia’s Excess Factory Capacity


 Add as a preferred source on Google
International developments moved to the back seat this week, as the risks stemming from Greek debt crisis and China’s equity market eased off for now. However, renewed weakness in commodity sector and concerns over corporate profitability weighed on market sentiment.
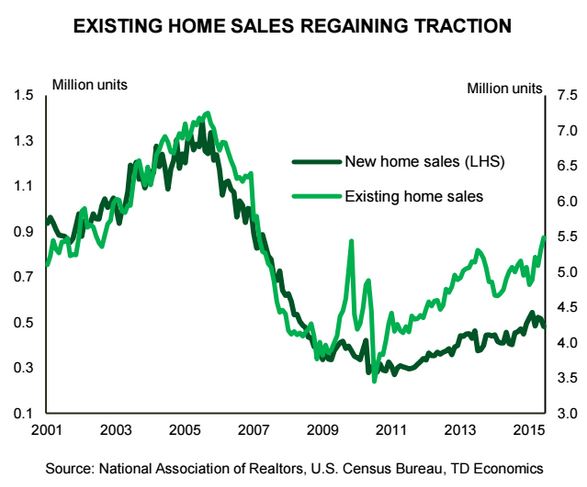
The domestic data flow remained relatively upbeat. Initial jobless claims fell to a multi-decade low. Existing home sales rose by 3.2% in June to a new cycle high. New home sales disappointed, declining by 6.8% in June, however they were still up 18% relative to a year ago.
Next week should bring further evidence of a rebounding economy, with second quarter GDP reading expected to show a 2.5% gain. The upturn in economic data is likely to be recognized in the Fed’s July interest rate announcement, which we expect to set the stage for September rate liftoff.







