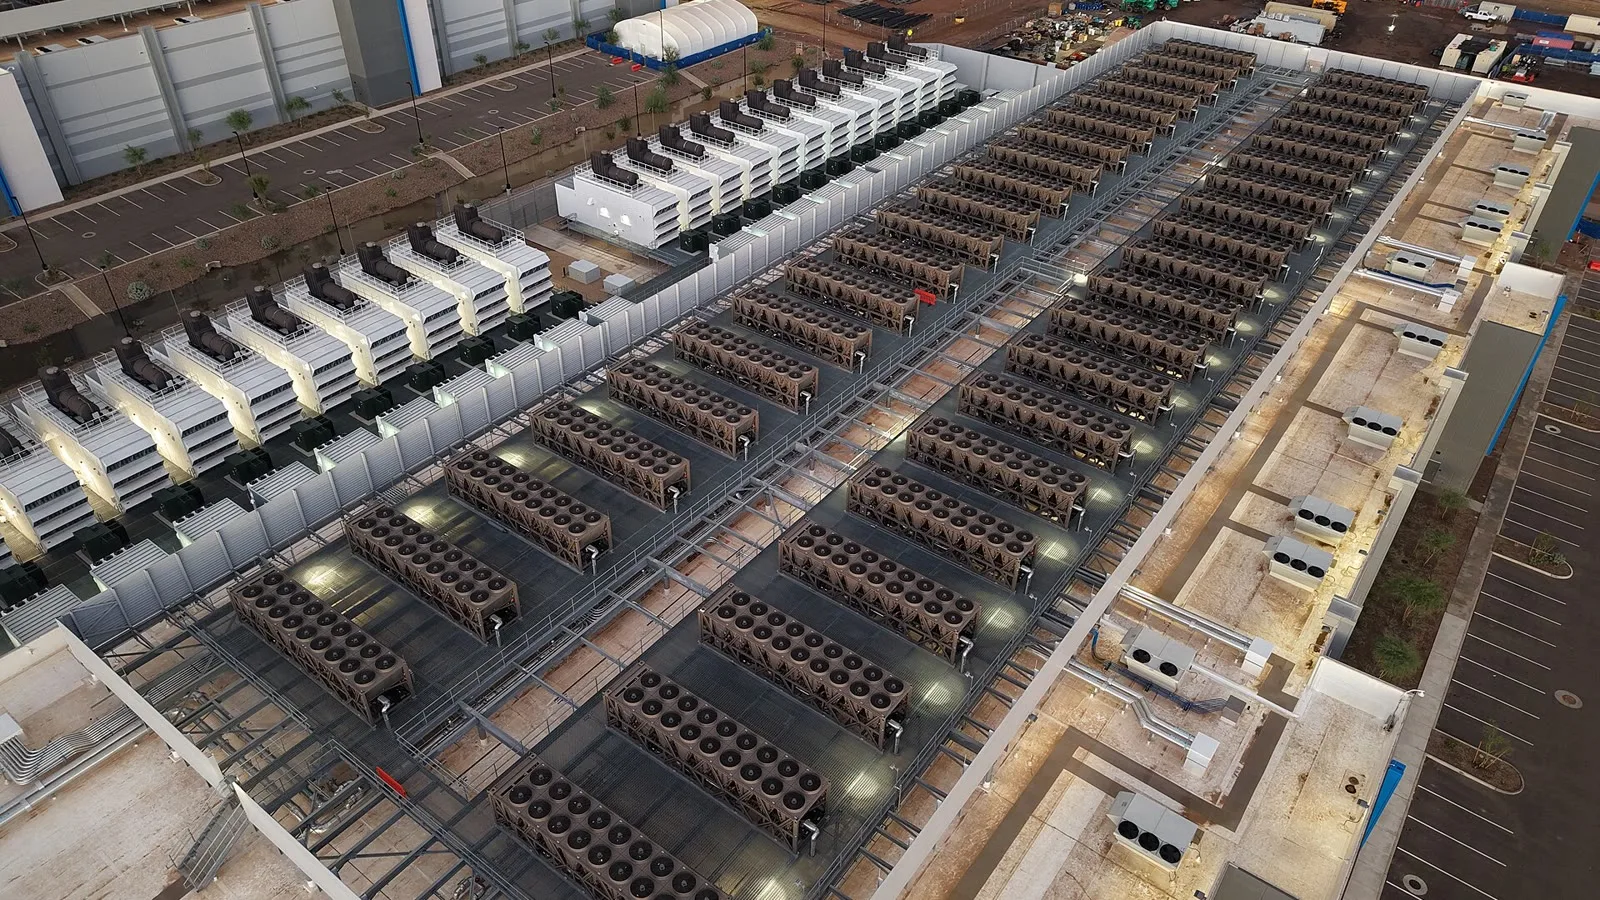
Data center builders are relying more on debt as their artificial intelligence investment nearly matches operating cash flow, a Federal Reserve Bank of St. Louis paper said.
The paper, “Hyperscalers’ Financing of the AI Investment Boom,” published Nov. 19 in the bank’s On the Economy series, examined 10 large U.S. technology companies from 2018 through early 2026. The authors found that data center builders and semiconductor producers financed the AI expansion in sharply different ways.
The study covered Alphabet, Amazon.com, Apple, Broadcom, Intel, International Business Machines, Meta Platforms, Microsoft, Nvidia and Oracle. It used “hyperscalers” broadly to include chip suppliers as well as cloud and data center operators.
Data center builders’ investment averaged $196.38 billion per quarter in the period from the fourth quarter of 2024 through the second quarter of 2026, nearly matching operating cash flow of $197.52 billion, the authors found. Net debt issuance rose to $30.17 billion per quarter from $3.23 billion in the pre-ChatGPT period from the first quarter of 2012 through the fourth quarter of 2018.
Their shareholder payouts fell to 13.6% of operating cash flow from 27.1%, while cash accumulation slipped to 2.2% from 2.7%. Both payouts and cash holdings increased in dollar terms, but more slowly than operating cash flow and investment, the paper said.
Semiconductor producers followed a different pattern. Operating cash flow reached $40.98 billion per quarter against investment of $22.68 billion. Operating cash flow grew 288.3% between the two periods, while investment rose 165.4%.
Chipmakers shifted from net debt issuance of $1.10 billion per quarter to net repayments of $0.79 billion. Their shareholder payouts rose to 34.4% of operating cash flow from 28.1%, and cash accumulation increased to 5.7% from 0.5%.
Across the full group, hyperscalers’ debt-to-assets ratio fell to roughly 25% in early 2026 from nearly 30% in 2023, while the ratio for other publicly traded U.S. companies stayed near 34%. The authors said this meant debt had grown more slowly than hyperscalers’ assets.
Hyperscalers’ shareholder payout ratio also fell to about 2% from about 4% in 2022, while operating income relative to assets rose to 25% from about 21% in 2023. The ratio for other firms remained near 13%.
The authors said the findings showed data center builders had less room to fund investment from operating cash flow and would depend more on profitability, retained earnings and external financing. The analysis excluded off-balance-sheet commitments such as future lease and purchase obligations.