


 Oil Prices Dip Slightly Amid Focus on Russian Sanctions and U.S. Inflation Data
 Fed’s Hammack Says More Data Needed Before Next Rate Move
 BOJ Set for 25-Basis-Point Rate Hike as Yen Weakness Fuels Inflation
 U.S. Treasury Yields Expected to Decline Amid Cooling Economic Pressures
 Evernorth XRPN Nasdaq Listing Delayed to October 12
 China's Refining Industry Faces Major Shakeup Amid Challenges
 Energy Sector Outlook 2025: AI's Role and Market Dynamics
 Gold Prices Fall Amid Rate Jitters; Copper Steady as China Stimulus Eyed
 Kazakhstan and Tether Explore Tenge Stablecoin and RWA Tokenization
 RBA Says ASX Still Falls Short on Governance and Risk Controls
 Goldman Predicts 50% Odds of 10% U.S. Tariff on Copper by Q1 Close
 Trump Demands Powell Resign Over Fed Renovation Cost Overruns
 Fed’s Logan Signals 50 Basis Points More in Rate Hikes
 China’s Growth Faces Structural Challenges Amid Doubts Over Data
 Kalshi Withdraws PEPE Perpetual Futures Filing


 Add as a preferred source on Google
As USDCNY breached a key support at 6.4772 levels recently, the market seems to be curious whether Chinese central bank would step up an effort to prevent its currency from appreciating too drastically.
China, with a mere 1.3% GDP surplus, has a FEER-consistent exchange rate that is 6.32 not that far from the current rate, really. Hence, PIIE agreement with Treasury Secretary Mnuchin’s conclusion that China is not manipulating its currency. In our opinion, CNY is not an outlier given the backdrop of broad USD weakness.
In this case, there is no emergency for the authorities to conduct a directional intervention. Over the foreseeable future, the PBoC would continue to anchor its currency to the currency basket.
It is highlighted that elevated carry/vol ratios near multi-year highs represented the single most noteworthy thematic dislocation in FX options. This is a result of rising interest rates intersecting with über-depressed financial market volatility and enables earning the leveraged carry in an upbeat global growth environment with low option premium spend and defined maximum loss.
The pro-risk sleeve of our options portfolio is accordingly composed of ATMF vs. ATMS call spreads in two EM currency pairs, EURCNH and EURRUB; the former because of its loose correlation to the CNY TWI that is expected to remain stable in coming months, and the latter as a play on oil price strength with additional macro support from a positive current account.
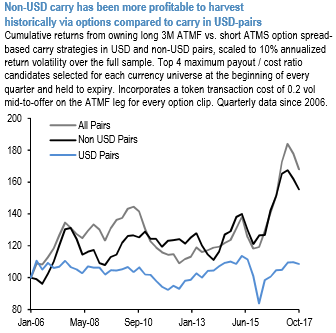
Both pairs have been chosen to dodge outright exposure to the broad dollar, which has been in line with the anticipation of moderate USD strength through 1Q’18 at the time of writing, and is also the historically more profitable approach to carry trading – 1st chart illustrates a selection of the best four carry/vol currency pairs bought in ATMF/ATMS option spread format and held-to-expiry fared considerably better for the non-USD currencies than in USD pairs over the past decade.
Stability in EURCNH and EURRUB spot last month fully justifies their selection as pure carry candidates, though in hindsight, swifter delta gains would have resulted from simply owning USD puts. At the current market, the best value within the option-based carry universe resides in TWD/INR, EURTRY, and EURCNH (refer 2nd chart). Courtesy: JPM







