


 Goldman Sachs Forecasts Fed Rate Hike as Inflation Risks Rise
 Unsustainable – or manageable? We don’t yet know how data centres will impact Australia’s environment
 ‘Buy now, pay later’ doesn’t feel like debt. For young people, that can be a big problem
 Synthetic data could ease people’s concerns about privacy breaches. But who gets to create it?
 Banking scandal rocks Brazil’s politics and the country’s presidential election in October
 China’s robots can run faster than Usain Bolt – now they are being prepared for war
 Big AI wants to slow down AI research. Is it a safety pause or a strategic retreat?
 Gold Slides to $4,262 as Hawkish Fed Rate Hike Triggers Technical Breakdown
 Physicists zoom into the birth of cosmic rainstorms with new CERN study


 Add as a preferred source on Google
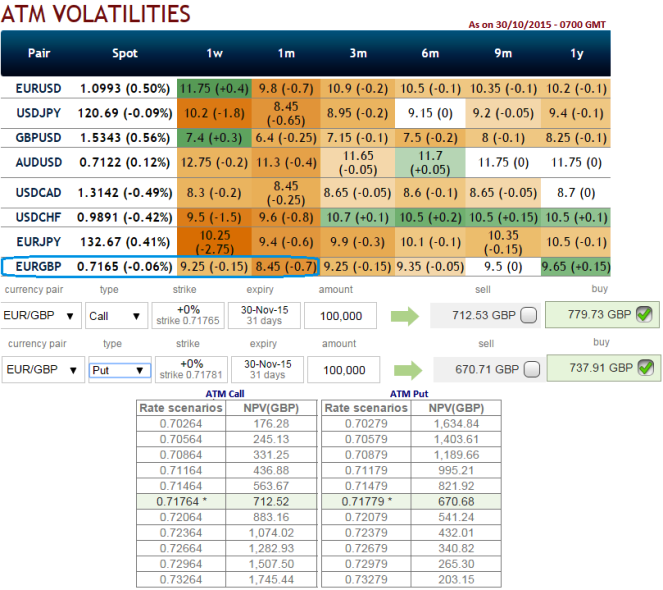
The implied volatility of ATM contracts is at 9.25% and it is expected to reduce at around 8.5% for near month expiries of this the pair.
NPV of 1m ATM call is at 712.52 while the Premiums trading above 9.40% at GBP 779.73 for lot size 100,000 units.
NPV of ATM put is at 670.68 while Premiums trading above 10.02% at GBP 737.91 for lot size 100,000 units.
Thereby, comparing this difference in options premiums and NPV with implied volatility in market sentiments we think the hedging cost would not be economical on downside deploying ATM put instruments.
But we cannot afford to get stuck in this riddle without hedging, so what's the alternative, in forwards markets at least..?
Subsequently, here comes the strategy arbitrage strategy in which options trading that can be performed for a riskless profit as EURGBP ATM call options are overpriced relative to the underlying exchange rate of EURGBP.
To perform this conversion, the hedger holds the underlying spot FX and offset it with an equivalent synthetic short spot FX (long put + short call) position.
Profit is locked in immediately when the conversion is done, the profit would be strike price of call/put - purchase price of underlying + call premium - put premium.

- News

- Economy

- Central Banks
- Investing
- Research
- Roundups
- Digital Currency
- Insights
- Technical Analysis
- Technology
- Business
- Law
- Health
- Nature
- Fintech
- Science
- Topic
- Opinions
- ©Econometrics LLC . All Rights Reserved.
FxWirePro: EUR/GBP ATM puts seem costlier, option arbitration in lieu of shorts on reducing IV
Friday, October 30, 2015 1:30 PM UTC
Editor's Picks



- Market Data
Most Popular




