


 Gold Surges Past $4400 on Crude Oil Rally; Bullish Trend Dominates
 Moody's Upgrades Argentina's Credit Rating Amid Economic Reforms
 Goldman Predicts 50% Odds of 10% U.S. Tariff on Copper by Q1 Close
 Bank of America Posts Strong Q4 2024 Results, Shares Rise
 European Stocks Rally on Chinese Growth and Mining Merger Speculation
 Citi Sees Signs of Shift in Global Currency Policy
 JPMorgan Sees ECB Raising Rates to 2.75% in December
 Gold Prices Fall Amid Rate Jitters; Copper Steady as China Stimulus Eyed
 US Gas Market Poised for Supercycle: Bernstein Analysts
 S&P 500 Relies on Tech for Growth in Q4 2024, Says Barclays
 Oil Prices Dip Slightly Amid Focus on Russian Sanctions and U.S. Inflation Data
 Hormuz Shipping Slows as Iran Threats Lift Oil Risks
 UBS Projects Mixed Market Outlook for 2025 Amid Trump Policy Uncertainty


 Add as a preferred source on Google
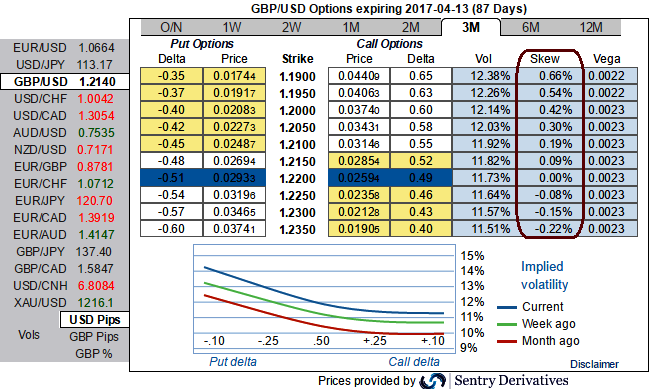
After Brexit apprehensions, GBPUSD recoupled with short-term rates, which are unlikely to trend in H1’17. The Brexit formalities would not be soft but seem unlikely to bring in large surprises or any dramatic movements in GBP over the next six months. Settling dust and the cable’s future range make GBP volatility a Sell.
Trimming GBP forecasts by 2% on heightened political risk of a hard Brexit: In the 2017 FX Outlook we articulated a modestly negative set of GBP forecasts, but stressed that our conviction level in these was low and that GBP could rise or fall by 5-10% depending on the strategic objectives the government eventually set for Brexit.
In other words, the forecast was a probability-weighted average of two extreme binary outcomes -a hard Brexit that prioritizes migration and sacrifices single market access, or a soft Brexit which maintains trade tries at the expense of migration control.
On the other hand, a lot of hazardous news is already priced in and digested by the market, preventing it from being overly bearish. Brexit caused two Sterling debacles, first in June with the vote and then after the summer when PM May suggested a hard exit.
Cable lost about 15% over a quarter and it now seems the dust has settled. In the process, volatility fell but remained relatively high on a historical basis.
Cable neither up nor down: The forecasts suggest the cable in the upcoming months to remain in its new range above 1.20, but not rise as high as 1.29, in fact, convictions for around 1.18 levels seems quite prudent.
Assuming a medium-term range in cable and that negative surprises are no longer market tail risks, the GBPUSD volatility is a Sell. Please be noted that the IV skews are still signaling downside risks, 3m positively skewed IVs signifies the hedgers’ interest in deep OTM Put strikes. While risk reversals are still bids for the bearish risks.







