


 ECB May Stop Rate Hikes After December, Capital Economics Says
 RBA Says ASX Still Falls Short on Governance and Risk Controls
 BOJ Signals Faster Rate Hikes as Inflation Risks Grow
 Geopolitical Shocks That Could Reshape Financial Markets in 2025
 Bank of America Posts Strong Q4 2024 Results, Shares Rise
 Goldman Predicts 50% Odds of 10% U.S. Tariff on Copper by Q1 Close
 Trump’s "Shock and Awe" Agenda: Executive Orders from Day One
 BOJ Flags Import Costs and Yen Shocks as Persistent Inflation Risks
 Indonesia Surprises Markets with Interest Rate Cut Amid Currency Pressure
 Oil Prices Dip Slightly Amid Focus on Russian Sanctions and U.S. Inflation Data
 Fed Rate Hike Threatens Housing as U.S. Growth Leans on AI, Citi Says
 Fed’s Hammack Says Bond Yield Surge Is Not Driven by Inflation Fears
 S&P 500 Relies on Tech for Growth in Q4 2024, Says Barclays
 Energy Sector Outlook 2025: AI's Role and Market Dynamics


 Add as a preferred source on Google
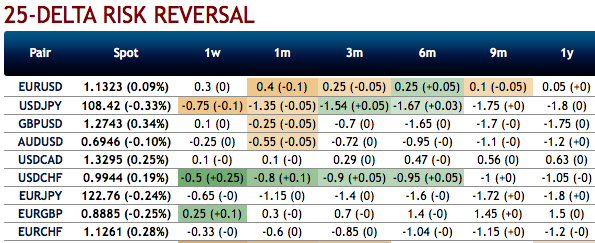
This has been a year of lower vols, especially among FX space. Just glance at the OTC FX markets, shrinking implied volatilities (IVs) are luring options writers. Please observe USDCHF, EURCHF, and GBPCHF are showing lower IVs despite the schedule of SNB’s monetary policy event for this week.
This may be because the Swiss National Bank (SNB’s) has been maintaining the status quo in its monetary policy to leave everything unchanged (kept libor rate at -0.75%). Consequently, the development of CHF over the past weeks did not seem to have provided any reason to tighten the monetary policy reins after all. With lingering uncertainty over the Italian budget conflict and Brexit, CHF seems to be much more in demand again recently. During such a circumstance that the SNB does not want to give the FX market any other arguments for trading the franc at stronger levels, which would put pressure on the inflation outlook and domestic exports.
The medium-term fundamental factors which support CHF are still intact in our opinion, even if they comprise relatively slow-moving, structural forces which may not be observable day to day. Chief amongst these is Switzerland’s structural balance of payments disequilibrium, by which we mean the combination of an excessive current account surplus and inadequate private sector capital outflows to recycle the surplus. This disequilibrium has become more acute over the past year resulting in upside pressure on the franc.
Please be noted that EURCHF’s major downtrend remains intact (refer above chart), technically, although you see some mild rallies in the short run, downswings are likely to extend after sliding below 21EMA on the occurrence of bearish engulfing pattern, both trend & momentum oscillators on the bearish bias.
OTC updates and trade recommendations: (Short in EURCHF via ITM put options, spot reference: 1.1204 levels).
EURCHF bearish neutral risk reversal numbers and positively skewed of implied volatilities of 3m tenors signify the bearish risks to prevail further (refer 1stand 2ndexhibits). 25-delta risk reversals indicate the difference in volatility, and therefore price, between puts and calls on the most liquid out-of-the-money (OTM) options quoted on the OTC market. Negative bids indicate puts are more expensive than calls (downside protection is relatively more expensive).
Accordingly, we advocate 2m (1%) in the money -0.79 delta put options, the rationale for choosing such derivative instrument is that the in the money put with a strong delta would move in tandem with the underlying downward moves. Courtesy: Sentrix, Saxo & JPM
Currency Strength Index: FxWirePro's hourly EUR spot index is inching towards -23 levels (which is mildly bearish), while hourly CHF spot index was at 26 (mildly bullish) while articulating (at 11:54 GMT).
For more details on the index, please refer below weblink: http://www.fxwirepro.com/currencyindex







