


 DeFi Development Adds 22,070 SOL to Solana Treasury
 Hong Kong’s Second Solana ETF Launches With Lower Fees
 US Futures Rise as Investors Eye Earnings, Inflation Data, and Wildfire Impacts
 U.S. Banks Report Strong Q4 Profits Amid Investment Banking Surge
 Monero Price Holds $515 Support as XMR Eyes $545 Breakout
 Urban studies: Doing research when every city is different
 Ethereum Foundation-Linked Wallets Move $11.13M in ETH to Kraken
 Ripple Mints 19.6 Million RLUSD Amid Banking Expansion
 Crypto Derivatives Dashboard: Bulls Retain Control Amid $488M Liquidation Flush
 Most Americans Oppose Election Betting on Prediction Markets, Poll Finds
 US Gas Market Poised for Supercycle: Bernstein Analysts
 Bitcoin Price Drops as US Dollar Hits 18-Month High
 Trump’s "Shock and Awe" Agenda: Executive Orders from Day One
 Goldman Predicts 50% Odds of 10% U.S. Tariff on Copper by Q1 Close
 Moody's Upgrades Argentina's Credit Rating Amid Economic Reforms
 Navigating the Crypto Pulse: Weekly Market Resilience and Institutional Inflows


 Add as a preferred source on Google
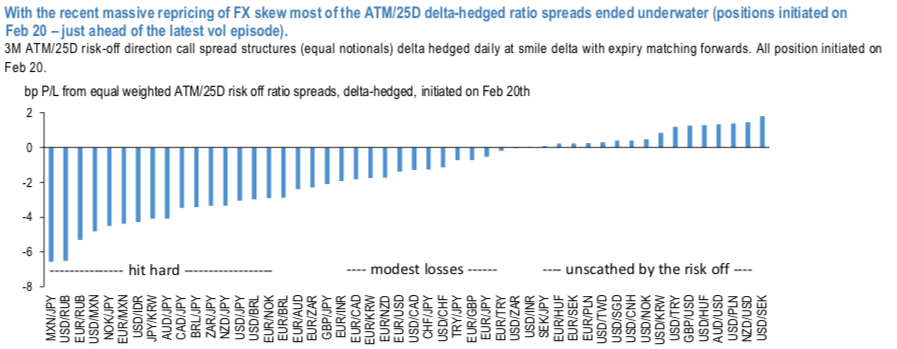
The entire global market sentiment has been driving strictly defensive positioning we think that it is prudent to keep an eye on historic skew dislocations their theta-scalping via risk off ratio spreads (delta-hedged). Those are a class of structures that can efficiently monetize excessive risk premia in vol smiles. While ratios can be struck for both calls and puts, the recent vol episode pushed the pricing of risk of OTM strikes into uncharted territory and made of particular interest the structures where the short notional is placed on the “risk-off” side, i.e. selling risk-reversals. While such structures are quicker in collecting premium, exposure to left tail is notable.
The brutal sell-off in crude oil prices as occurred over the past weekend led to a sharp repricing of vols and skews of oil-exporting currencies, most notably, RUB, NOK and CAD. A closer inspection reveals that outside of the EM petro-currencies and yen high beta crosses, the losses in risk-off ratio spreads were moderate (refer 1st chart). This is encouraging as the currently elevated levels of skew pricing should provide a buffer from incurring further losses if spot- vol correlation picks up again.
USDCAD vols risk-off call ratio spread is an outlier that dominates 2nd chart where currency pairs are screened based on 3-year Sharpe (a medium term performance horizon) of risk off ratio vol spread structures and 1y z-score of skew / ATM vol ratio.
3M USDCAD delta-hedged ATM/25D call spread @9.8/10.3indic vs 12.7ch, equal notionals to keep the structure net long vega.
An alternative way for benefiting from elevated skew, while offering at the same time risk-off exposure, is via directional (not delta-hedged) call spreads. Especially in the case of CAD, a regression analysis finds that the latest move in Oil well justifies the changes in vol and skew, but that there is further room for spot to move higher (about +3% of upside based on the past 3m change in Oil prices).
Consider: 3M USDCAD 1.40/1.4280 strikes (40D/30D) call spread (live, no delta-hedge) costs @55bps USD (spot ref. 1.3860), 3.5X max payout / cost ratio. Courtesy: JPM







