


 S&P 500 Relies on Tech for Growth in Q4 2024, Says Barclays
 Ripple-Backed Evernorth Set for Nasdaq Debut With 473 Million XRP
 Crypto Derivatives Dashboard: Bulls Retain Control Amid $488M Liquidation Flush
 Ethereum Foundation-Linked Wallets Move $11.13M in ETH to Kraken
 Goldman Predicts 50% Odds of 10% U.S. Tariff on Copper by Q1 Close
 Ripple Mints 19.6 Million RLUSD Amid Banking Expansion
 US Futures Rise as Investors Eye Earnings, Inflation Data, and Wildfire Impacts
 Trump’s "Shock and Awe" Agenda: Executive Orders from Day One
 Bitcoin Price Drops as US Dollar Hits 18-Month High
 Bank of America Posts Strong Q4 2024 Results, Shares Rise
 XRP Price Holds $1.35 Support as Bears Target $1.25
 Navigating the Crypto Pulse: Weekly Market Resilience and Institutional Inflows
 Arthur Hayes Announces FLOP Testnet Launch Within Weeks
 Zcash Price Drops 30% as ZEC Tests Critical $1,120 Support
 Gold Prices Slide as Rate Cut Prospects Diminish; Copper Gains on China Stimulus Hopes
 Wall Street Analysts Weigh in on Latest NFP Data
 Binance to Shut Down Crypto Mining Pool Services on November 10


 Add as a preferred source on Google
Over the weekend, the price of precious yellow metal has taken a halt from the vigorous rallies at the peaks of $1,738 levels. Gold, for the first time ever, punched through the R1m a kilogram price level. Though trading below its 2012 peak of $1,772.25 an ounce in dollar terms, the stiff resistance is observed at $1,750 areas. Gold (in the bullion market) gains considerably from the last couple of days, especially after gold testing the strong support at $1,445 - $1,455 levels).
Since March 19 when the front-end gold vols peaked the normalization has flattened the vol curve and halved the March vol spike. The fundamental analysts see gold price staying on a relatively muted glide path, modestly lifted by real yields only but starved of more explosive drivers. Amid such a backdrop, we reiterate from our previous posts that realized vol should be contained but the risk posed by daily spot gyrations even absent a drift keeps us more interested in fwd vols as a safer place to position for further normalization.
We feel cautiously optimistic that the worst is behind us as the gamma trade timing framework that were suggested in our recent posts, takes a U-turn from being the most defensive in the decade to being neutral. While the level of uncertainty about the overall economic impact and the path forward remains high the more upbeat sentiment amid an improved COVID-19 backdrop is continuing to put downside pressure on the gold vol curve. In this write-up, we emphasize the area for exploiting the precious metals backdrop.
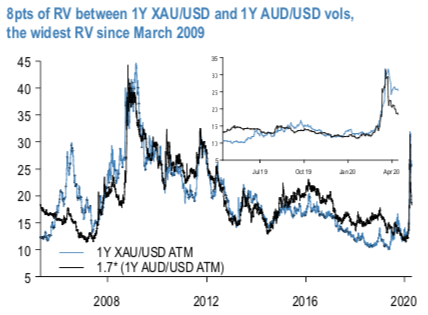
Well, AUD retraced 75% of the March spike gold vol has materially lagged completing only about 30% of the retracement. Accounting for the difference in the vol beta and correspondingly scaling up AUD vols (e.g. for 1Y tenor by 1.7X) results in nearly identical Feb-March vol spike (1-yr chart in the above chart).
That indicates AUD vols to have been an effective hedge during the recent vol episode. Even accounting for b/o the current XAUUSD – 1.7*AUDUSD vol spread of 7-vol pts and risk/reward of > 2X make the RV attractive for participating in a continued normalization. One risk is that the disparity in pace of normalization between gold and AUD vols could persist and keep the spread elevated.
Historically, narrowing of the spread tended to occur rapidly and in fairly monotonic fashion once normalization took hold in gold vols, the vol backdrop that we see now. 1Y tenor is a sweet spot both on gold and AUD vol curve and appeals as largely insulated from gold spot gyrations that would plague front tenors.
We recommend: Short 1Y XAUUSD delta-hedged straddles @24.25/25.5vols indicative hedged with long 1Y AUDUSD delta-hedged straddles @10.5/11.1vols indicative, in 1:1.7 notionals. Courtesy: JPM







