European government borrowing costs rose about 100 basis points after the Middle East war began, the International Monetary Fund's European department director said, calling for action on public finances.
The increase affected 10-year government bonds in the four largest euro area economies and Britain. Higher borrowing costs reduce governments' room to spend, adding to strains from ageing populations and defence needs.
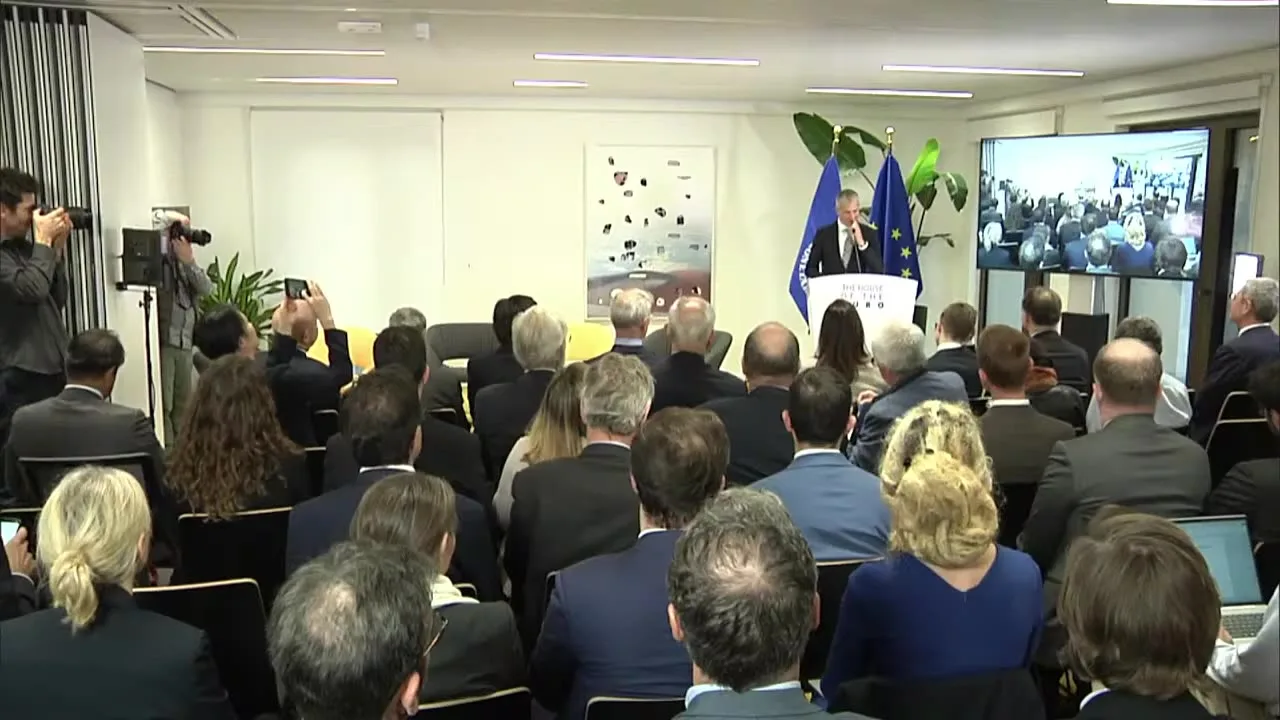
The director presented the assessment at the House of the Euro in Brussels in “Choosing Growth: IMF Regional Economic Outlook for Europe,” published on Nov. 13.
Global factors, including the energy shock and interest rate increases, accounted for most of the rise. But debt levels, fiscal prospects and political uncertainty also influenced borrowing costs.
A temporary increase lasting another year, followed by a return to pre-war yields in 2027, would carry an average cost of about 0.2%. The remarks did not specify the measure underlying that percentage.
France's extra borrowing costs would exceed its projected increase in defence spending. A longer-lasting rise would increase the burden, although financial conditions across the wider economy had tightened only slightly.
Europe weathered the energy shock better than the department expected in April. Growth remained weaker than projected in January, while underlying price increases stayed contained despite higher inflation.
Energy changes made in 2022 helped Europe withstand the shock. Monetary policy also helped prevent higher energy costs from spreading more widely through prices.
The department's growth forecasts for 2027 broadly matched the economy's sustainable growth rate, estimated at just 1.1% to 1.2%. Growth in central and southeastern Europe would fall below its average over past decades.
Euro area inflation would remain above target until 2028, and longer in central and southeastern Europe. The forecasts assumed gradually declining energy prices, leaving risks of weaker growth and more persistent inflation.
The forecasts also assumed another European Central Bank rate increase of 25 basis points this year, possibly followed by another in 2027. Other European central banks might need to hold rates higher for longer or raise them.
Government budget balances excluding interest payments would worsen only slightly in 2026. Energy relief remained relatively small and temporary, but often failed to concentrate help on those needing it or preserve incentives to save energy.
Public debt already exceeded levels of the 2010s in many countries. Unchanged policies would raise debt relative to annual economic output by 50 percentage points in advanced Europe and more than 80 in central and southeastern Europe. No time horizon was specified.
“Europe is still not making enough of its talent, assets, savings, single market,” the director said. Faster growth would reduce the budget adjustments needed to address longer-term spending demands.
Closer energy market links and more renewable investment could lower prices and volatility. The Nemo electricity connection between Belgium and Britain had reduced both in Belgium.
Over the past 10 years, intangible activities, including artificial intelligence, contributed only a third as much to EU labour productivity growth as in the United States. Reforms should help businesses expand, adopt technology and shrink when ventures fail.
Central and southeastern Europe also faced wages rising faster than productivity, loose budgets and emerging external deficits. EU accession could increase prospective members' output per person by 30% to 35%, conditional on appropriate policies and productivity gains.