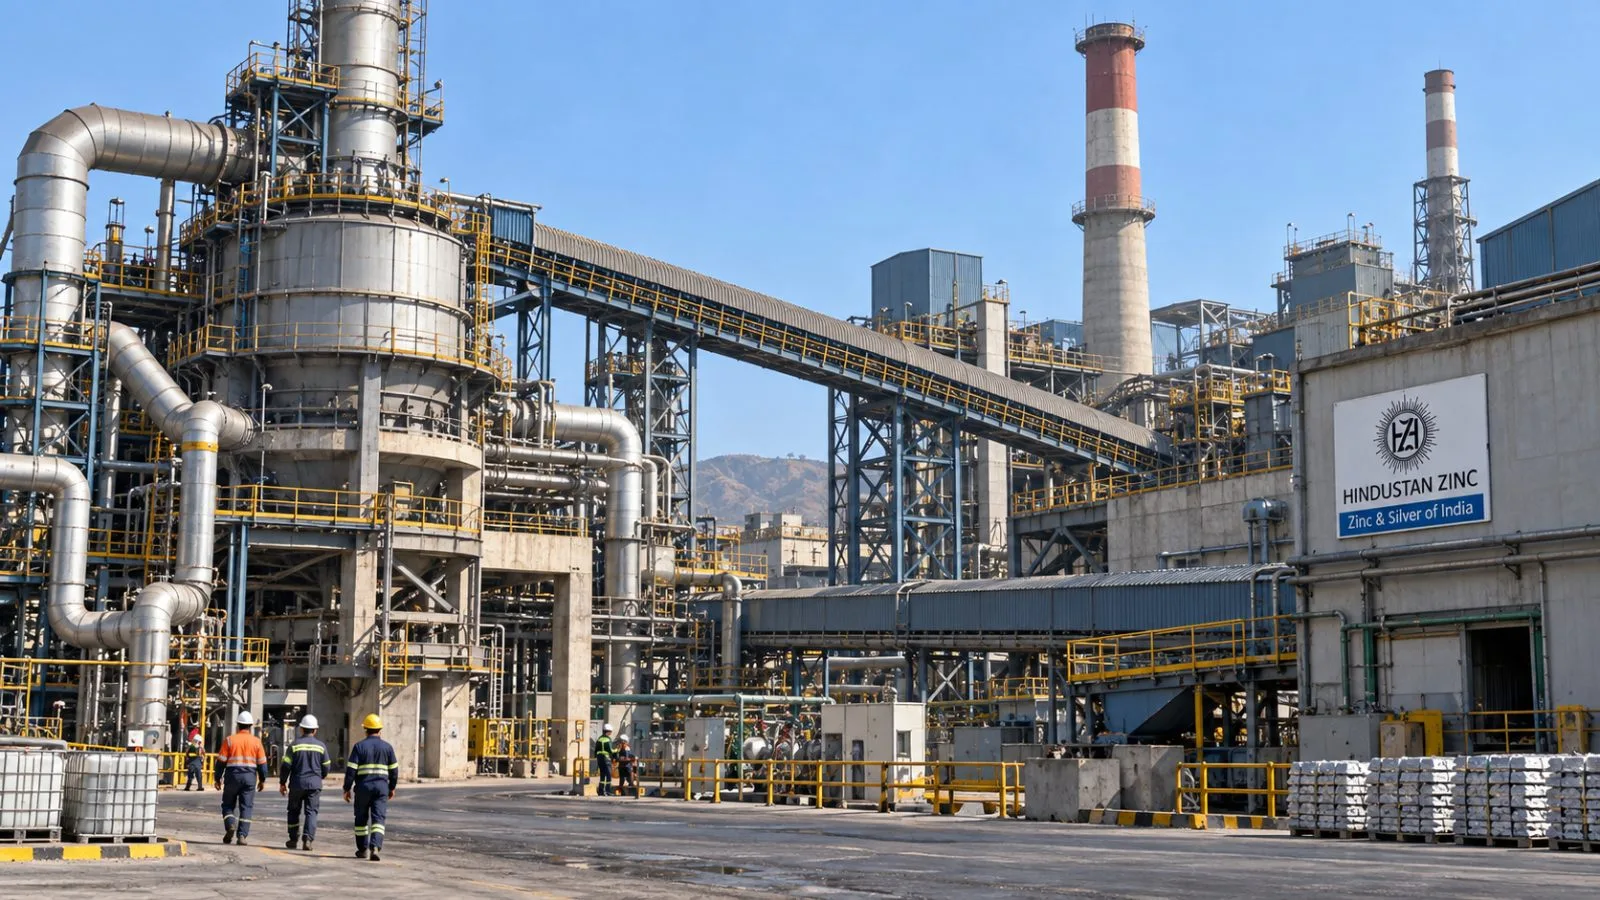
Systematix Institutional Equities raised its price target for Hindustan Zinc Limited to ₹677 after the miner lowered its annual zinc cost forecast, adding to the brokerage’s case for higher earnings.
Systematix kept its “Buy” rating and lifted the target from ₹669. NDTV Profit published the brokerage’s research on Oct. 21. Systematix increased its estimates for earnings before interest, taxes, depreciation and amortization by 23% for fiscal 2027 and 9% for fiscal 2028. Those figures are the brokerage’s forecasts.
The revised outlook follows a cut in Hindustan Zinc’s expected production costs. On its Oct. 19 earnings call, the company lowered its fiscal 2027 forecast for zinc production costs excluding royalties to $825 to $850 per tonne from $975 to $1,000. Its reported cost for the three months ended Sept. 30, 2026, was $703 per tonne; the revised range applies to the full fiscal year.
Hindustan Zinc Chief Financial Officer Amit Gupta said proceeds from sulfuric acid, a byproduct, contributed to the cost reduction. The company sells it at auction and does not issue a price forecast for it, he said. Gupta also said geopolitical pressures added about $50 per tonne to costs.
The company’s results provide context for the target change. Hindustan Zinc said its quarterly net profit rose 142% from a year earlier to $671 million. Revenue from operations increased 77% to $1.579 billion, while earnings before interest, taxes, depreciation and amortization rose 108% to $972 million.
Silver output reached 173 tonnes, up 20% from a year earlier. Hindustan Zinc retained its fiscal 2027 silver production target of 680 tonnes. Systematix expects zinc and silver supplies to remain tight, but identified geopolitical developments, energy costs and currency movements as risks to near-term prices.