


 Stock Futures Dip as Investors Await Key Payrolls Data
 Fed Rate Hike Threatens Housing as U.S. Growth Leans on AI, Citi Says
 Bank of America Posts Strong Q4 2024 Results, Shares Rise
 Gold Prices Fall Amid Rate Jitters; Copper Steady as China Stimulus Eyed
 RBI Rate Hike Bets Surge as Inflation Rises
 Zcash Mining Profits Surge as Liquidity Risks Grow
 Goldman Predicts 50% Odds of 10% U.S. Tariff on Copper by Q1 Close
 Evernorth XRPN Nasdaq Listing Delayed to October 12
 Peter Brandt Flags Key XRP Breakout at $1.6572
 Cardano ADA Jumps 10% as RealFi and Dijkstra Upgrade Fuel Rally
 Fed Unveils Stablecoin Rules Under GENIUS Act
 BOJ Set for 25-Basis-Point Rate Hike as Yen Weakness Fuels Inflation
 Strategy’s STRC Nears $100, Raising Prospects for Major Bitcoin Buys
 Bitcoin Nears $87K as Crypto Market Gains
 Clearpool Expands to XRP Ledger, Plans CLEAR Token Migration


 Add as a preferred source on Google
We have BoE scheduled for its monetary policy announcement in this week, we take a look a look at the policy outlook and the implications for the economy. The MPC is not anticipated to publish any inflation forecast at the two-year horizon that is much different from the 0.1ppt overshoot of the 2% CPI target presented in August.
In August, the Bank Rate of BoE was lifted to 0.75%. The market does not expect that the Bank Rate would be hiked until late next year, even though there seems to be high uncertainty about the exact timing of the hike, the right-hand chart below. This corresponds well with our long-held forecast, pointing to a hike in November 2019. We anticipate that the present guidance; i.e. that hikes will continue at a gradual pace and to a limited extent, will be maintained at this meeting. In addition, the BoE may indicate how monetary policy could respond to a no-deal Brexit.
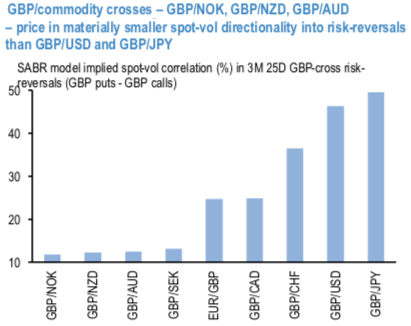
The 1stand 2ndchartsexhibit that even if one were to completely shun non-mainstream GBP-crosses, a conventional pair like EURGBP is still available as a better priced risk-reversal alternative to GBPUSD. The simple reason is that option markets remain loath to de- price Italian risks out of Euro-crosses, with the implication that EUR puts/GBP puts are better bid vis-à- vis EUR calls/GBP puts than would have been the case otherwise.
Onto other crosses.
3rdchartplots monthly return betas of GBP put options across G10 vis-à-vis those of GBP puts/USD calls over two sub-samples: a) all months when GBPUSD put returns were positive, and b) May- June of 2016 around the Brexit referendum. As anticipated, GBPCHF and GBPJPY have the highest median betas to GBPUSD (and even then, less than 1); GBPCAD and GBPNZD are interesting mid-table entries that rank ahead of even a liquid GBP-cross such as EURGBP. The even more noteworthy numbers are the return betas around the Brexit referendum event: GBPNZD, GBPAUD and to a lesser extent GBPCAD puts were the standout performers on that occasion, in part because GBP-weakness remained a localized event without broader risk market spillovers, and partly due to benign option pricing, ostensibly for similar reasons that their riskies are subdued today. Courtesy: JPM
Currency Strength Index: FxWirePro's hourly EUR spot index is inching towards -101 levels (which is bearish), while hourly GBP spot index was at -71 (bearish) while articulating (at 14:07 GMT). For more details on the index, please refer below weblink:







