


 Citi Sees Signs of Shift in Global Currency Policy
 Trump’s "Shock and Awe" Agenda: Executive Orders from Day One
 US Futures Rise as Investors Eye Earnings, Inflation Data, and Wildfire Impacts
 Geopolitical Shocks That Could Reshape Financial Markets in 2025
 Indonesia Surprises Markets with Interest Rate Cut Amid Currency Pressure
 UBS Projects Mixed Market Outlook for 2025 Amid Trump Policy Uncertainty
 Gold Prices Slide as Rate Cut Prospects Diminish; Copper Gains on China Stimulus Hopes
 Hormuz Shipping Slows as Iran Threats Lift Oil Risks
 Stock Futures Dip as Investors Await Key Payrolls Data
 Wall Street Analysts Weigh in on Latest NFP Data


 Add as a preferred source on Google
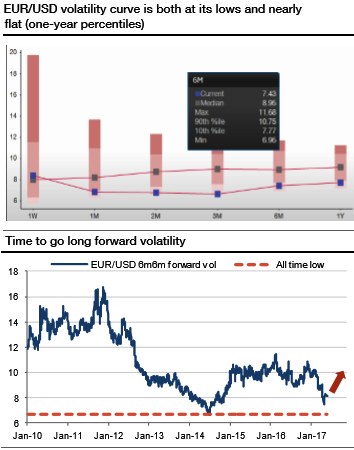
After the French presidential election, the EURUSD volatility curve aggressively sold off, reaching its lowest level since 2014. Since then, implied vols have bounced only very timidly and are still very close to their recent lows (refer above graph). Interestingly, the curve is usually quite steep when vol is globally low, and conversely, it tends to flatten or even invert when vol rises. The current configuration – a nearly flat curve combined with low volatility – looks like an anomaly, as the vega part should include a term premium when the front end is very low.
Curves are usually driven by the front end, and the risk priced there is then diffused towards the longer tenors. But even if short-term volatility remains subdued, we can contemplate the steepening being driven by the vega part of the curve in a context where the market is not shaken by near-term fears but starts discounting the medium-term outlook. EURUSD 6m volatility in six months offers a great opportunity, as it is trading only about one volatility point above its all-time low (refer above graph).
The uncertain and reflationary environment should involve a premium in vega vols, with the flat curve making forward volatility very attractive to buy. We recommend going long an EURUSD 6m6m forward volatility agreement at 7.8.







