


 Ethereum Foundation-Linked Wallets Move $11.13M in ETH to Kraken
 Bank of America Posts Strong Q4 2024 Results, Shares Rise
 Nasdaq Faces Pullback to 26,225 Despite Bullish Outlook, UBS Says
 UBS Projects Mixed Market Outlook for 2025 Amid Trump Policy Uncertainty
 S&P 500 Relies on Tech for Growth in Q4 2024, Says Barclays
 XRP Ledger Foundation Confirms 100B Supply Safe After Security Fix
 Arthur Hayes Announces FLOP Testnet Launch Within Weeks
 Moldova Criticizes Russia Amid Transdniestria Energy Crisis
 2025 Market Outlook: Key January Events to Watch
 Ripple Mints 19.6 Million RLUSD Amid Banking Expansion
 Binance to Shut Down Crypto Mining Pool Services on November 10
 US Futures Rise as Investors Eye Earnings, Inflation Data, and Wildfire Impacts
 Urban studies: Doing research when every city is different
 Trump’s "Shock and Awe" Agenda: Executive Orders from Day One
 China's Refining Industry Faces Major Shakeup Amid Challenges


 Add as a preferred source on Google
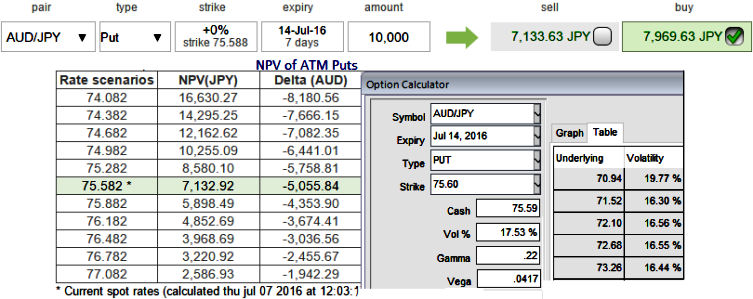
This pair has been tumbling after Brexit event as the buying momentum is reduced and the long-term downtrend seems to be intact for now as the massive volumes are convincing this bearish environment on monthly charts.
While IVs of ATM contracts of 1w and 1m tenors are trending above 17.53% as we have flurry data announcements in Japan, namely, current account balance for today.
Upper house elections are slated during this weekend. Preliminary and core machinery orders, PPI, and industrial production are scheduled for the next week.
These volatilities have been justified by historical volatilities in spot FX fluctuations.
On the flip side, ATM premiums of 1w expiries are trading at shy below 11.75% and there exists the disparity between IVs and option premiums which we perceive this as an under-priced option.
Traders tend to view the put ratio back spread as a bear strategy because it employs puts. However, it is actually a volatility strategy. The implied volatility of 1M ATM put contract is at 17.44% and it is quite higher side when long-term trend is bearish and spikes in previous rallies for the short term which is a good sign for option writers. Thus, in such higher vols situation, the under-priced options are luring factor in any option strategies.
Traders tend to view the put ratio back spread as a bear strategy because it employs puts. However, it is actually a volatility strategy which we’ve formulated as below.
Options with a higher IV cost more. This is intuitive due to the higher likelihood of the market 'swinging' in your favor but in AUDJPY case we have a very rare opportunity in under-priced puts. If IV increases and you are holding an option, this is good. You should also note short-dated options are less sensitive to IV, while long-dated are more sensitive.
As we expect the underlying currency exchange rate of AUDJPY to make a larger move on the downside. As shown in the figure purchase 1M 2 lots of At-The-Money -0.52 delta puts and sell 1W one lot of (1%) In-The-Money put option.
So far we all know that the position uses long and short puts in the ratio, such as 2:1 or 3:2 and so on to maximize returns depending upon risk appetite and returns expectations.







