


 Global Markets React to Strong U.S. Jobs Data and Rising Yields
 Moldova Criticizes Russia Amid Transdniestria Energy Crisis
 Wall Street Analysts Weigh in on Latest NFP Data
 Gold Prices Slide as Rate Cut Prospects Diminish; Copper Gains on China Stimulus Hopes
 Fed May Resume Rate Hikes: BofA Analysts Outline Key Scenarios
 Moody's Upgrades Argentina's Credit Rating Amid Economic Reforms
 Geopolitical Shocks That Could Reshape Financial Markets in 2025
 UBS Predicts Potential Fed Rate Cut Amid Strong US Economic Data
 2025 Market Outlook: Key January Events to Watch
 U.S. Treasury Yields Expected to Decline Amid Cooling Economic Pressures
 S&P 500 Relies on Tech for Growth in Q4 2024, Says Barclays
 Energy Sector Outlook 2025: AI's Role and Market Dynamics
 European Stocks Rally on Chinese Growth and Mining Merger Speculation
 US Gas Market Poised for Supercycle: Bernstein Analysts
 Mexico's Undervalued Equity Market Offers Long-Term Investment Potential
 US Futures Rise as Investors Eye Earnings, Inflation Data, and Wildfire Impacts
 U.S. Banks Report Strong Q4 Profits Amid Investment Banking Surge


 Add as a preferred source on Google
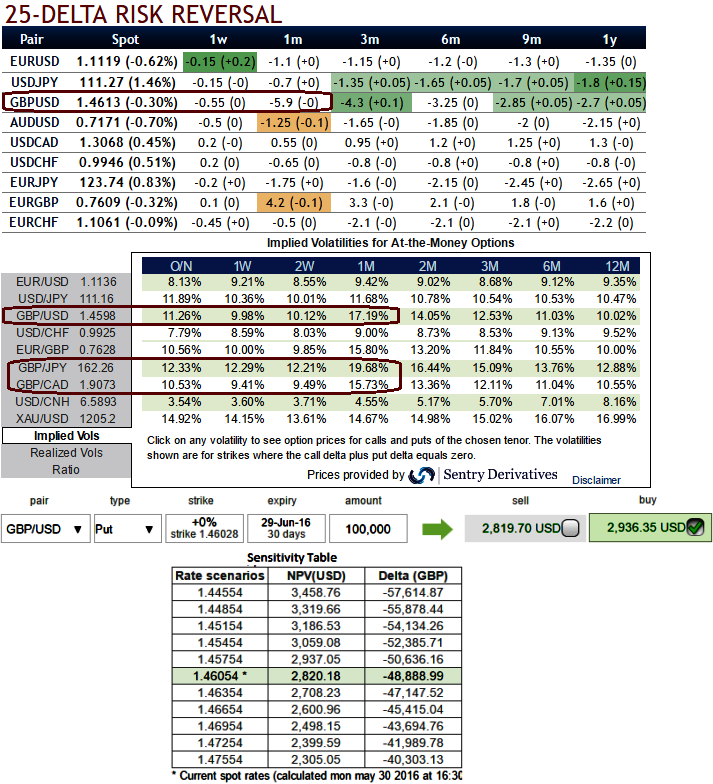
After previous monetary policies from ECB, Fed and BoE, the euro and sterling OTC market turbulence was cooling off, as the hedging sentiments for certain currency pairs have been losing the traction.
The focus this week turns to the ECB and the Fed. The ECB will not take any fresh action but the press conference will be interesting for views on its reaction function as inflation forecasts start rising.
The ECB may also consider reinstating the collateral waiver on Greece. In the US, we expect a weak non-farm payrolls number for May which would increase the hurdle for the Fed to hike in June.
Ahead of UK's PMIs in this week, sterling gained against the majors except Euro, GBPUSD was up almost 0.13% at 1.4607 from the lows of 1.4587 earlier European session.
In this month, GBPUSD with BoE's unchanged bank rates at 0.5% were already factored in as it was much anticipated move that kept sterling away from much of hedging activities.
But for now, the implied volatilities flashed screaming off as the sterling crosses surged because UK PMIs are likely to indicate prospects of their economic health - businesses react quickly to market conditions and Fed is on the focus during mid June. UK referendum is on the other corner that appends sizeable risks to sterling.
1m IVs of GBP crosses are observed to have spiked massively considering above event risks, highest among G10 currency space.
While, risk reversal numbers are also flashing highest values that indicates the hedging instruments getting expensive in OTC markets anticipating downside risks.
We stated in our previous write up as well that the vols in OTC are likely to pick up rapidly again in 1-3M tenors as these tenors encompasses all significant data events.
The above table ranks in rising implied volatility among G10 currency crosses, sterling overreacting due to upcoming economic events but likely to tumble and stabilize at 12.5% in coming months. IV and risk reversal readings of GBPUSD have been the best buys on for selecting put options.
Hedging bets:
Let's now consider ATM GBPUSD put options of 1m tenors, they are trading at just shy above 4.11%.
While delta risk reversals are still flashing up progressively with positive numbers that favours bulls and indicates they are willing to pay OTM strikes in higher vols.
Since, IVs of ATM contracts are at higher levels with negative risk reversals would mean that puts have been underpriced relatively to the calls.
During Brexit scenario, at spot FX of GBPUSD is trading at 1.4603, and is anticipated to tumble moderately in the months to come, so it is better to use near month at the money puts with 50% delta in any hedging strategies.







