


 U.S. Treasury Yields Expected to Decline Amid Cooling Economic Pressures
 S&P 500 Relies on Tech for Growth in Q4 2024, Says Barclays
 Moody's Upgrades Argentina's Credit Rating Amid Economic Reforms
 UBS Predicts Potential Fed Rate Cut Amid Strong US Economic Data
 Gold Prices Fall Amid Rate Jitters; Copper Steady as China Stimulus Eyed
 China’s Growth Faces Structural Challenges Amid Doubts Over Data
 European Stocks Rally on Chinese Growth and Mining Merger Speculation
 UBS Projects Mixed Market Outlook for 2025 Amid Trump Policy Uncertainty
 Stock Futures Dip as Investors Await Key Payrolls Data
 Trump’s "Shock and Awe" Agenda: Executive Orders from Day One
 US Gas Market Poised for Supercycle: Bernstein Analysts
 2025 Market Outlook: Key January Events to Watch
 Moldova Criticizes Russia Amid Transdniestria Energy Crisis
 U.S. Stocks vs. Bonds: Are Diverging Valuations Signaling a Shift?
 Bank of America Posts Strong Q4 2024 Results, Shares Rise
 US Futures Rise as Investors Eye Earnings, Inflation Data, and Wildfire Impacts
 Goldman Predicts 50% Odds of 10% U.S. Tariff on Copper by Q1 Close


 Add as a preferred source on Google
A no-deal Brexit is off the agenda - for the end of October anyway. But unless a final decision on Brexit is taken, either for or against it, or with or without a deal, we consider the current quiet on the markets to be fragile; in particular as things are beginning to move a little again. Prime Minister Boris Johnson has now suggested holding general elections on 12th December, literally at the earliest possible date. He will propose this motion to Parliament on Monday.
But as was the case with his withdrawal agreement, this idea too is meeting opposition. The Labour Party for example is insisting that the extension of the Brexit deadline should initially be finalised before they can agree to elections. The markets are likely to watch with interest who is going to cave in this time. Johnson’s record so far suggests that it is going to be him.
Well, if elections really are going to be held by the end of the year we would expect to see increased volatility in the GBP exchange rates in the run-up, in particular a renewed rise in implied 1-2 month volatilities seems almost a given.
This double-header of favourable political developments (the US-China trade sentiments in addition to a Brexit deal) in the near future could herald a tactical turn for the better in the general risk climate.
Hence, our defensive stance in EURGBP has been dictated by the receding global economic tide, but we cannot ignore that political risk has been an instrumental factor in these worse macro outturns. This warrants a tactical reduction in our defensive exposure but we uphold our hedging portfolios via 3-way straddles.
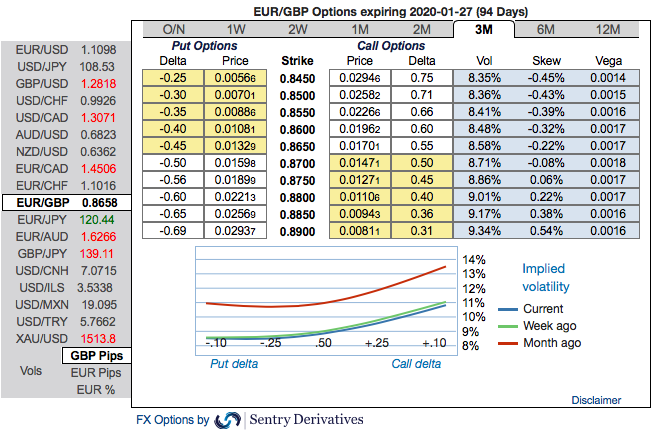
The passively skewed IVs of 3m tenors are stretched are indicating upside risks, more bids are observed for OTM call strikes up to 0.89 level.
While EURGBP risk reversals of the existing bullish setup remain intact with mild bearish shift, you see minor negative risk reversal numbers in the shorter tenor, but it should not be perceived as the bearish scenario changer. Instead, below options strategy could be deployed amid the expected turbulent condition. According to the OTC FX surface, 3-way options straddle versus ITM calls are advocated seem to be the most suitable strategy for EURGBP contemplating some OTC sentiments and geopolitical aspects.
Options Strategy: The strategy comprises of at the money +0.51 delta call and at the money -0.49 delta put options of 2m tenors, simultaneously, short (1%) ITM calls of 1w tenors. The strategy could be executed at net debit but with a reduced trading cost.
Hence, on hedging as well as trading grounds, initiate above positions with a view of arresting potential FX risks on either side but slightly favoring short-term bearish risks. Courtesy: Sentrix, Saxo & Commerzbank







