FxWirePro: USDCHF low implied volatility portrays hedging with condor spreads
Since the implied volatility of USDCHF is perceived to be minimal, so here comes a multiple leg of option strategy for regular traders of this currency cross when there is little IV. A total of 4 legs are involved in the…
Since the implied volatility of USDCHF is perceived to be minimal, so here comes a multiple leg of option strategy for regular traders of this currency cross when there is little IV. A total of 4 legs are involved in the condor options strategy and a net debit is required to establish the position.
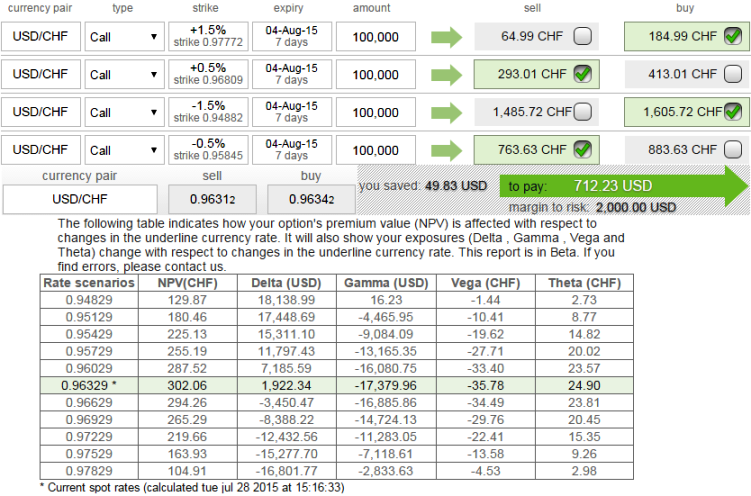
The trader can construct a long condor option spread as follows, as shown in the figure; the trader can implement this strategy using call options with similar maturities.
So strategy goes this way, writing 7D (-0.5%) In-The-Money call and buying deep striking (-1.5%) 0.84 delta In-The-Money call, writing a higher strike (0.5%) Out-Of-The-Money calls and buying another deep striking (1.5%) Out-Of-The-Money 0.17 delta call for a net debit.
Maximum returns for this strategy is achievable only when the exchange rate of USDCHF falls between the 2 middle strikes at maturity. It can be derived that the maximum profit is equal to the difference in strike price of the 2 lower striking calls less the initial debit taken to enter the trade.
Australia's September 2026 labour report shocked to the negative: unemployment climbed to 4.7% from 4.6% and employment dropped by 39,300 against expectations for a 20,000 increase. Part-time work dropped by 73,700, whic…
UNCX Network, a cryptocurrency token vesting platform formerly known as UniCrypt, suffered a security exploit on Wednesday that drained approximately $86,000 from its shared Ethereum token pool. Blockchain security firm …
Solana is preparing to introduce its highly anticipated Alpenglow consensus upgrade on October 21, 2026, marking one of the blockchain's biggest technological changes since its launch in 2020. The upgrade aims to signifi…