


 BOJ Set for 25-Basis-Point Rate Hike as Yen Weakness Fuels Inflation
 Banking scandal rocks Brazil’s politics and the country’s presidential election in October
 ECB Rate Hike in Focus as Oil Tops $100
 Yen Extends Gains as BOJ Rate Hike Bets Rise
 UAE Central Bank Probes Banque Misr Over Iran Links
 Physicists zoom into the birth of cosmic rainstorms with new CERN study
 1 in 3 uni students experience serious financial hardship. Could concession cards for all help?
 Bank of England Sees Surge in Higher-Risk Collateral
 China Boosts Gold Reserves by 650,000 Ounces as Prices Rally


 Add as a preferred source on Google
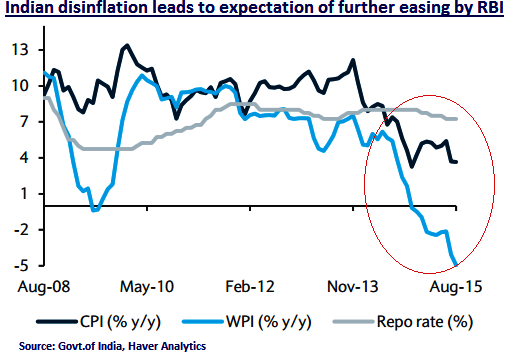
Strong disinflation opens room for further RBI easing, the disinflation in India has been strong and broad-based since H2 2014, reflecting markedly better food price management, sustained idle industrial capacity, lower commodity prices and a largely stable INR.
We expect retail inflation (CPI) to average 5% during FY 15-16, considerably lower than the central bank's early 2016 target of 6% and the long-term (15- year) average of 7.3%.
Disinflation has been even stronger at the wholesale price (WPI) level, which has contracted on y/y basis in every month since November 2014 and is currently near a four-decade low (August 2015: -5.0% y/y).
The renewed weakness in commodity prices in Q3 15 should help keep inflation 'lower for longer'. Despite stronger GDP prints under the 'new' series, we see little sign of demand-driven inflation.
Such rapid disinflation allowed the Reserve Bank of India (RBI) to cut the repo rate by 75 bps during H1 15. We look ahead to the central bank to cut the repo rate another 25 bps in H2-15, likely in its policy meeting scheduled for tomorrow.
What are market participants expecting from tomorrow's policy?
According to Bloomberg Survey of 49 analysts, 41 expect a repo rate cut and 8 expect no change in the RBI's stance on the interest rate. Our expectation is also of a 25 basis point cut in the benchmark repo rate. SLR and CRR are expected to remain unchanged.

- News

- Economy

- Central Banks
- Investing
- Research
- Roundups
- Digital Currency
- Insights
- Technical Analysis
- Technology
- Business
- Law
- Health
- Nature
- Fintech
- Science
- Topic
- Opinions
- ©Econometrics LLC . All Rights Reserved.
Indian disinflation leads pressures on RBI easing
Monday, September 28, 2015 12:46 PM UTC
Editor's Picks



- Market Data
Most Popular




