


 RBA Says ASX Still Falls Short on Governance and Risk Controls
 RBA Hikes Interest Rate to 4.60% as Inflation Risks Rise
 Fed’s Hammack Says More Data Needed Before Next Rate Move
 RBI Raises Repo Rate to 5.50% in Hawkish Shift on Inflation Risks
 Yen Sinks as BOJ Rate Hike Fails to Impress Markets
 Fed Unveils Stablecoin Rules Under GENIUS Act
 Fed’s Williams Signals One More Rate Hike Before Year-End


 Add as a preferred source on Google
Although demand for defensive assets is rising due to a global equity rout brought by the decline in Chinese stocks and sudden devaluation of the CNY, the JGB market is relatively stable at this point. It is because JGBs are already priced high under the BOJ's ongoing large-scale JGB purchase and investors have not taken and cannot take an aggressive position on either side.
"Participants may remain in this stance until the US jobs data are announced on 4 September and/or until the FOMC meeting on 16-17 September to watch for whether the Fed hikes rates. But the market needs to be careful of rising volatility with liquidity declining", says Bank of America.
Investors' wait-and-see stance pushed down trading activities, and according to the JSDA, private-sector financial institutions trading volume in couponbearing JGBs only totaled ¥19.8tn in July, the lowest since the data started being kept in April 2004.
"In September, a tightening of supply-demandis expected to push yields lower and flatten the curve, because of a large amount of redemptions scheduled in September and concerns over disinflation brought by declining oil prices", added Bank of America.
If global stock markets continue weakening and markets remain in risk-off mode, there is a possibility of significant demand from investors who were unable to buy enough JGBs as planned due to low yields will increase prior to end-1H FY15. Aggressive JGB buyers cannot be found other than the BOJ at this point, but sellers seem to be fading at the same time, and then it is likely to get harder for the BOJ to maintain QQE.

- News

- Economy

- Central Banks
- Investing
- Research
- Roundups
- Digital Currency
- Insights
- Technical Analysis
- Technology
- Business
- Law
- Health
- Nature
- Fintech
- Science
- Topic
- Opinions
- ©Econometrics LLC . All Rights Reserved.
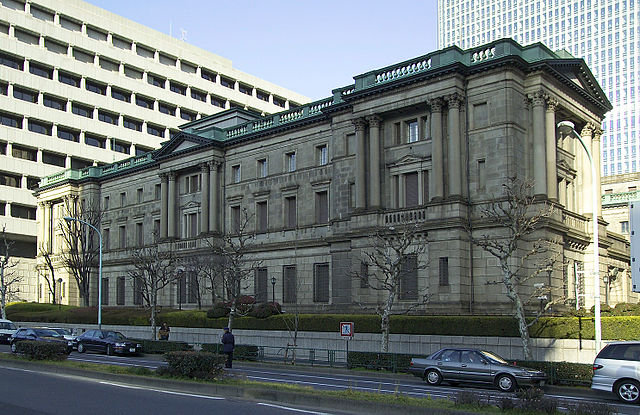
It is likely to get harder for BOJ to maintain QQE
Tuesday, September 1, 2015 5:24 AM UTC
Editor's Picks



- Market Data
Most Popular




