


 AI is supercharging money scams – here’s what you can do to protect yourself
 Unsustainable – or manageable? We don’t yet know how data centres will impact Australia’s environment
 Banking scandal rocks Brazil’s politics and the country’s presidential election in October
 Europe can’t achieve space sovereignty alone. Here’s why
 Physicists zoom into the birth of cosmic rainstorms with new CERN study
 Goldman Sachs Forecasts Fed Rate Hike as Inflation Risks Rise
 Synthetic data could ease people’s concerns about privacy breaches. But who gets to create it?
 1 in 3 uni students experience serious financial hardship. Could concession cards for all help?
 Big AI wants to slow down AI research. Is it a safety pause or a strategic retreat?
 China’s robots can run faster than Usain Bolt – now they are being prepared for war


 Add as a preferred source on Google
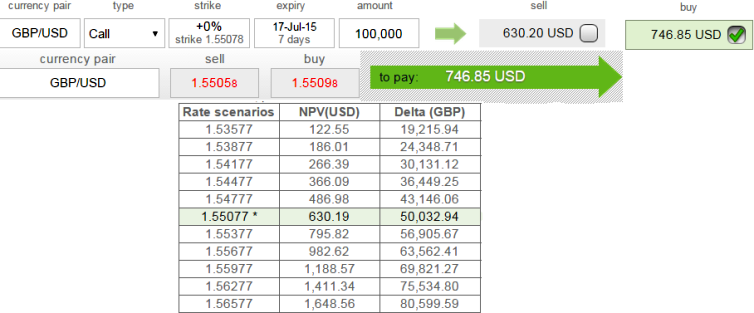
Delta signifies the equivalent FX spot outrights of a given position. This is the sensitivity of a position's value with respect to the spot rate.
This is useful to monitor directional risks so you may know how much your option's value will increase or diminish as the underlying market moves.
A higher delta value is desirable for an option holder, whilst a delta close to zero is desirable for the option writer; a buyer wants their option to become more valuable whilst a seller wants the option to become less valuable.
For an instance, as we can see in the chart that overall position in GBPUSD behaves as if it was long 50,032.94 GBPUSD spot.
But in real terms, if at all GBPUSD spot were to move up by one pip then the relative sensitivity in option premium would be USD 0.5003. To hedge a call, one would invest the option price proceeds into Δt∗St+Bt=ct (where Δ=delta).
These terms may seem quite strange to you but nothing rocket science hidden in it, we would run you through these blackscholes in upcoming articles.

- News

- Economy

- Central Banks
- Investing
- Research
- Roundups
- Digital Currency
- Insights
- Technical Analysis
- Technology
- Business
- Law
- Health
- Nature
- Fintech
- Science
- Topic
- Opinions
- ©Econometrics LLC . All Rights Reserved.
Why delta is crucial in option strategy
Friday, July 10, 2015 1:59 PM UTC
Editor's Picks



- Market Data
Most Popular




