


 Banking scandal rocks Brazil’s politics and the country’s presidential election in October
 Guterres Urges Stronger Global AI Safeguards Ahead of UN Assembly
 What is Zionism? The different meanings of a contested term
 US Confirms Weapons in Orbit as Space Tensions Rise
 Sweden Election: Centre-Left Holds Narrow Lead
 Philippines Holds Historic Bangsamoro Election Amid Tight Security
 Kim Jong Un Pledges Deeper Russia Cooperation
 Judge Blocks Trump Rule Limiting Foreign Student Visas
 Nvidia CEO Jensen Huang Expected at Trump-Xi State Dinner
 Rodrigo Duterte Makes First Public Appearance at ICC in 18 Months
 China’s Global Times Slams Anthropic CEO’s AI Slowdown Plan as ‘Cold War’ Strategy
 Global Poll Shows Rising Trust in Institutions as US-China Leadership Support Falls
 U.S. Imposes New Visa Restrictions Over South Africa Policies
 Trump Rejects Calls for Tougher AI Regulation
 Vietnam, U.S. Firms Plan 29 Deals Across Energy, Tech and Aviation
 Ukraine Tests New Anti-Drone Weapon After Successful Shahed Intercept


 Add as a preferred source on Google
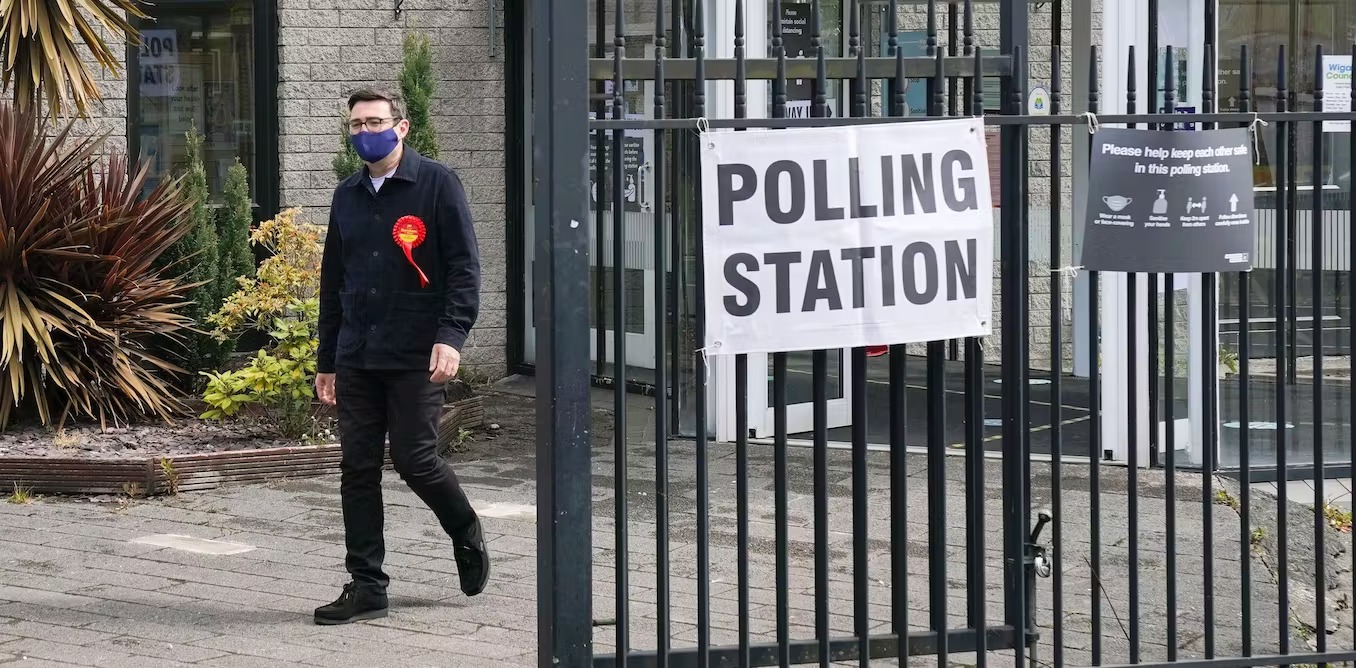
Andy Burnham’s recent victory in the Makerfield by-election has sparked speculation about a potential future challenge to U.K. Prime Minister Keir Starmer, raising questions about the outlook for U.K. government bonds, gilt yields, and British equities.
According to a research note from Citi, economists believe any leadership transition within the Labour Party is more likely to occur later this summer, although a quicker path to a Burnham-led government cannot be ruled out. Financial markets are already assessing how such a political shift could affect fiscal policy, government borrowing, and key sectors of the U.K. stock market.
A rapid leadership change could provide short-term support for gilt markets by reducing political uncertainty. However, a prolonged leadership contest may keep investor attention focused on the government’s fiscal position, potentially increasing pressure on U.K. government bonds.
Market participants are particularly concerned about the possibility of higher public spending under a Burnham administration. Even if existing fiscal rules remain unchanged, investors may focus on the prospect of increased government debt issuance. This could drive 10-year gilt yields back toward recent highs in the 5% to 5.25% range.
While Burnham has offered limited details on his broader economic agenda, he has previously supported reforms to property taxation and advocated public ownership of essential services, including water utilities.
Higher bond yields could have significant implications for U.K. equities. Historically, the FTSE 250 has been more vulnerable to rising interest rates and has often underperformed the globally focused FTSE 100 during periods of elevated yields. Analysts suggest this trend could continue if borrowing costs move higher.
Sector performance may also diverge. Real estate and utility stocks typically struggle when bond yields rise, while financials, energy companies, and basic resources tend to benefit. Banks, healthcare firms, and commodity-related stocks remain among the preferred investment areas in this environment.
Corporate earnings trends further support large-cap U.K. stocks. Profit expectations for the FTSE 250 have weakened this year, while forecasts for the FTSE 100 have improved, largely due to stronger earnings prospects in the energy sector.
Based on historical market behavior, a return of 10-year gilt yields to recent highs could trigger an additional 5% to 10% decline in rate-sensitive stocks, reinforcing the relative attractiveness of large-cap U.K. equities over mid-cap counterparts.







