


 Goldman Predicts 50% Odds of 10% U.S. Tariff on Copper by Q1 Close
 UNCX Network Hack Drains $86K From Ethereum Token Pool
 Most Americans Oppose Election Betting on Prediction Markets, Poll Finds
 China's Refining Industry Faces Major Shakeup Amid Challenges
 2025 Market Outlook: Key January Events to Watch
 Ripple-Backed Evernorth Set for Nasdaq Debut With 473 Million XRP
 Fed May Resume Rate Hikes: BofA Analysts Outline Key Scenarios
 Moldova Criticizes Russia Amid Transdniestria Energy Crisis
 U.S. Treasury Yields Expected to Decline Amid Cooling Economic Pressures
 Stock Futures Dip as Investors Await Key Payrolls Data
 Geopolitical Shocks That Could Reshape Financial Markets in 2025
 Mexico's Undervalued Equity Market Offers Long-Term Investment Potential
 Zcash Price Drops 30% as ZEC Tests Critical $1,120 Support
 Ripple Partners With DriveWealth to Expand RLUSD Settlements
 Gold's Tug-of-War: Geopolitical De-escalation Fights Falling Yields as Markets Eye US CPI


 Add as a preferred source on Google
Gold price seems to be the consistent standout under an investor positioning mean reversion rule with a success ratio of over 60% over the last five years and modest average monthly returns, albeit with a low information ratio.
As our trade moved into the money, we tightened our stop to avoid a loss. Prices moved below this level on June 23 and we closed at a profit.
Yellow metal prices kept sliding and now is on the verge of two-and-a-half month lows today and were on track to post a third straight session of losses as a recovery in the dollar hit investor demand for the precious metal.
Comex gold futures were at $1,234.67 a troy ounce by 10.58 GMT, down $7.63, or around 0.62%. It was the lowest level since May 16.
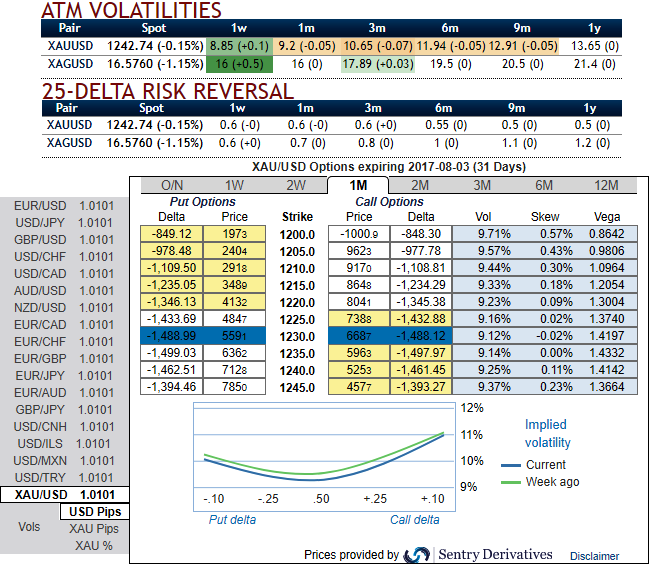
In our recent write-up, we had advocated 3-way straddles versus OTM Calls, the short leg on call has worked out so far. For now, we would like to reshuffle the option strategy as shown below.
Option Strategy: 3-Way Options straddle versus put
Spread ratio: (Long 1: Long 1: Short 1)
The execution: Initiate long in XAUUSD 1M at the money vega put, long 1M at the money vega call and simultaneously, Short theta in 1m (1%) out of the money put with positive theta or closer to zero.Theta is positive; time decay is bad for a buyer, but good for an option writer.
Rationale: The nutshell showing delta risk reversals above explains that hedgers’ interests have been neutral but upside risks are lingering, however, no new shift in sentiments is observed. While positively skewed IVs are also well balanced to signal the swings likely to oscillate on either direction. You could now again observe ETF positions have also surged in the last quarter.
As a result, we don’t see much traction OTM calls. While 1m – 1y IVs trending lower towards 9.2% to 13.65%. A seller wants IV to shrink away so the premium falls. You should also note short-dated options are less sensitive to IV, while long-dated are more sensitive.
Hence, we encourage vega longs and short thetas in the non-directional trending pair but slightly favors bearish strategy as the vega signifies the sensitivity of an option’s value owing to a shift in volatility. It is usually expressed as the change in premium value per 1% change in implied volatility.







