


 Global Markets React to Strong U.S. Jobs Data and Rising Yields
 Fairshake Backs 32 Pro-Crypto House Candidates
 U.S. Treasury Yields Expected to Decline Amid Cooling Economic Pressures
 Moody's Upgrades Argentina's Credit Rating Amid Economic Reforms
 Fed’s Hammack Says Bond Yield Surge Is Not Driven by Inflation Fears
 US Gas Market Poised for Supercycle: Bernstein Analysts
 Urban studies: Doing research when every city is different
 Ethereum Price Drops Below $2,600 as Long Liquidations Hit 4-Month High
 Bitcoin Bull Cycle Still Early as XRP, NEAR Consolidate
 Bitmine to Stop Ethereum Buying After Reaching 5% ETH Supply
 Solana User Growth Jumps 33%, Outpacing Ethereum and Chainlink
 Gold Prices Slide as Rate Cut Prospects Diminish; Copper Gains on China Stimulus Hopes
 DogecoinVM Makes DOGE Transactions 300x Faster
 Bank of America Posts Strong Q4 2024 Results, Shares Rise


 Add as a preferred source on Google
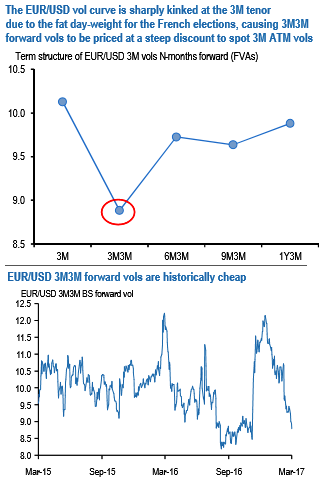
The European election-distorted EUR/EUR-cross vol curves: The risk premium for the French elections has distorted EUR-and EUR-cross vol surfaces. 3M-1M vol curves have steepened enormously due to the boost to 3M expiries from the fat day-weight associated with the second round vote on May 7th; post-3M vol curve segments are inverted however as the event effect fades in longer tenors (refer above chart).
The inversion of the 6M-3M segment and the resulting steep discount of 3M3M forward volatility (FVAs) to 3M ATMs has sparked interest in buying EURUSD 3M3M FVAs as an asymmetric election hedge at levels that appear historically favorable, especially after the sharp sell-off in vols this week (refer above chart).
It seems instinctive enough that 3M3M forward vol should deliver substantial positive returns in the event of an unexpected Le Penn victory, yet the dynamics of implied vols around a binary event can be a little murky since the shock of a tail outcome intersects with the offsetting effect of implied vols collapsing as a large day-weight rolls off the option expiry window (note: no such conflict with realized vols/gamma which explode when spot reacts violently to a shock result). Where this tension eventually re-sets implied vols after the event is difficult to quantify ex-ante, but we can at least look back at the two major political disruptions last year to judge how much merit there was in buying FVAs.
We examine the performance of 3M3M FVAs in GBPUSD around the Brexit referendum and USDMXN around the US elections initiated 2-months prior to event dates, roughly the time-to-event in the current instance. Initial conditions in terms of vol levels and curve slopes are not strictly comparable across episodes, but the consistency of outcomes across the (grand sample size of) two episodes is comforting.
Two key takeaways from chart 6 are: (a) in both cases, FVAs delivered 2.3-2.8 vols of peak P/L on mids and are able to monetize nearly the entire ex-ante static slide along the term structure, meaning that ATM vols do not roll down at all after a left tail outcome despite the passage of event risk; and (b) optimal entry timing into FVAs is 4-5 weeks before D-day when the pricing of event.







