


 UBS Projects Mixed Market Outlook for 2025 Amid Trump Policy Uncertainty
 Trump’s "Shock and Awe" Agenda: Executive Orders from Day One
 Gold Prices Fall Amid Rate Jitters; Copper Steady as China Stimulus Eyed
 Gold Surges Past $4400 on Crude Oil Rally; Bullish Trend Dominates
 Fed May Resume Rate Hikes: BofA Analysts Outline Key Scenarios
 U.S. Treasury Yields Expected to Decline Amid Cooling Economic Pressures
 Citi Sees Signs of Shift in Global Currency Policy
 Global Markets React to Strong U.S. Jobs Data and Rising Yields
 Stock Futures Dip as Investors Await Key Payrolls Data


 Add as a preferred source on Google
The acceleration in global growth towards 3% might even cause us to entertain the notion of adding some outright longs in cyclical currencies. What prevents us doing so is the caveat that these are not normal times politically speaking; in particular, we continue to believe that markets are overly complacent about the possibility of the President-elect acting on campaign pledges to address what it believes are unfair trade practices.
The Outlook discusses this issue in more detail, but the likelihood is that any action on trade following the inauguration would not sit easily with either risk markets or cyclical currencies.
Well, in our 2017 outlook, we included a number of protectionist hedges in G10 commodity currencies and we remain comfortable with both of these positions even though they are marginally in the red (short CAD/NOK in cash and short AUD/JPY through a 3Mx6M calendar spread of one-touch puts).
Stay long NOK vs EUR and CAD We continue to recommend NOK longs as an outright play on stronger oil prices and the ongoing improvement in the outlook for NOK rates (EUR/NOK) as well as an oil-neutral hedge to potential trade conflict under the incoming Trump Administration (CAD/NOK).
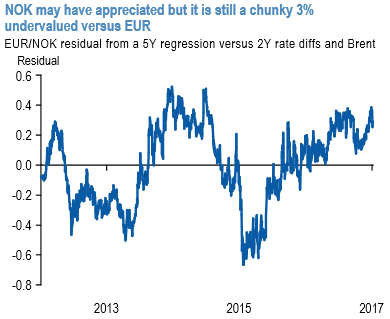
NOK is the second strongest performer in G10 since the last FXMWon December 16 (up 2.2% versus USD) yet it has plenty of headroom still to rally as it remains markedly undervalued relative to cyclical drivers.
Fair-value for EUR/NOK currently stands at 8.72; the resultant 3% undervaluation of NOK is amongst the more extreme of the last five years (this is a 1-sigma gap – refer above chart).
In addition, NOK TWI is 1.7% lower than the Norges Bank projects for Q1; hence there’s no suggestion the currency is close to levels that could start to undermine the interest rate outlook.







