


 Who should own the knowledge that underpins AI technology?
 Europe can’t achieve space sovereignty alone. Here’s why
 China’s robots can run faster than Usain Bolt – now they are being prepared for war
 1 in 3 uni students experience serious financial hardship. Could concession cards for all help?
 Banking scandal rocks Brazil’s politics and the country’s presidential election in October
 Unsustainable – or manageable? We don’t yet know how data centres will impact Australia’s environment
 Synthetic data could ease people’s concerns about privacy breaches. But who gets to create it?


 Add as a preferred source on Google
For those who don't like to accumulate either existing shorts on EUR positions or not longs dollar side with minimal delta terms, instead, better to take long term neutral positions such as option butterflies. We have some smart trading arrangements; these can even be utilized in our model the assortment of portfolio until the better clarity on how these global factors (especially Greece on euro side & Fed's decision on dollar side) will play out.
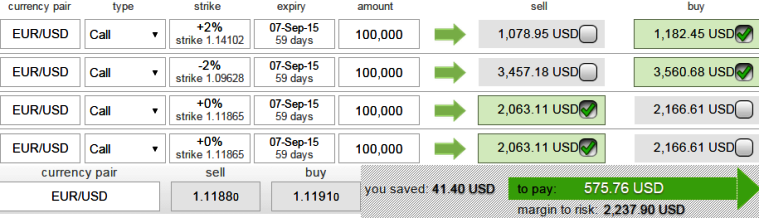
Therefore, buying 2M (+2%) Out-Of-The-Money (strikes at 1.1412) 0.34 delta call, buy another 2M (-2%) In-The-Money (strikes at 1.0964) 0.67 delta call and simultaneously sell 2 lots of 2M At-The-Money calls with positive theta values. All the positions should be early September maturities. As the delta on butterflies would usually be zero, this option combination should also be close to zero.
We reckon, this butterfly spread is best suitable and enables market laggards, risk averse traders, speculators who've been bias on both Fed's hike news and Grexit matters to participation in market turbulence as it brings in limited returns and limited risk.
Hedgers whose is neutral on irrespective market making matters but involved with their international business, this would arrests systematic risks.
Long butterfly spreads are entered when the investor thinks that the underlying exchange rate will not rise or fall much by expiration. One additional long position would result in net debit.

- News

- Economy

- Central Banks
- Investing
- Research
- Roundups
- Digital Currency
- Insights
- Technical Analysis
- Technology
- Business
- Law
- Health
- Nature
- Fintech
- Science
- Topic
- Opinions
- ©Econometrics LLC . All Rights Reserved.
FxWirePro: Laggards who expect Fed’s hike in September hedge EUR/USD using long butterfly
Friday, July 10, 2015 12:33 PM UTC
Editor's Picks



- Market Data
Most Popular




