


 Circle Stock Falls 4% as Crypto Selloff Overshadows SAP Pay Expansion
 Morgan Stanley Raises Coinbase Stock Price Target to $258 Ahead of Earnings
 Solana Price Drops 3% Despite Samsung USDC Partnership
 Bitcoin Rebounds to $82K as Crypto Market Faces Weekly Losses
 XRP Ledger Activates New Security Feature for Banks and Stablecoins
 Ethereum Price Drops Below $2,600 as Long Liquidations Hit 4-Month High
 Ledger Investigates Alleged $86 Million Crypto Wallet Theft
 Bitcoin Rebounds to $82K as Trump Eases Iran War Fears
 DWF Labs Sues BitGo for $114 Million Over Alleged Token Sales Breach
 Zcash Plans Quantum-Resistant Security Upgrade for January
 Chainlink Price Drops 3% Despite New CCIP Vault Launch
 XRP Whale Activity Drops 27% in Eight Days Amid Market Sell-Off
 Crypto Liquidation Flush: BTC & ETH at a Glance


 Add as a preferred source on Google
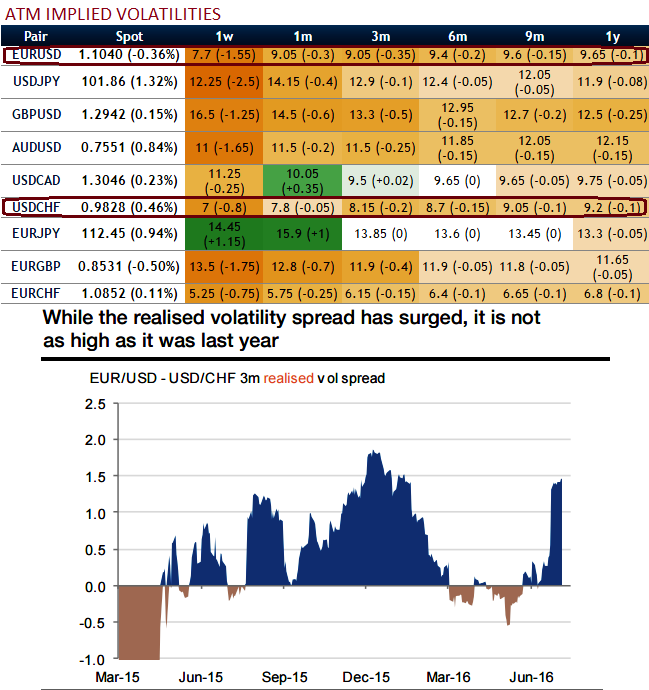
Further divergence between EUR/USD and USD/CHF volatility A spread of volatility swaps is exposed to the volatility differential between two currency pairs. Investors holding the position until the 3m expiry face unlimited losses if the realised volatility between EUR/USD and USD/CHF eventually exceeds 0.7 vols.
As we expect the vol spread to converge towards a flat level, it is advisable to go long in USD/CHF vs shorts in EUR/USD 3m volatility swaps, indicative bid: receive 0.7 vols.
However, past patterns suggest that the realised vol of the spread could exceed 0.7 vols (see above graph).
As such, we recommend unwinding the position before the expiry as soon as the net profit exceeds 0.5 vols.
Long/short of volatility swaps as a pure volatility trade, we recommend getting a pure volatility exposure via a long short of volatility swaps.
It allows for getting rid of systemic delta hedging and more generally of most of the gamma risks.
The pay-off of these instruments depends on realised volatility but their market to market (vega) is sensitive to implied volatility as well.







