


 BOJ Set for Rate Hike as Inflation and Yen Pressure Mount
 US Gas Market Poised for Supercycle: Bernstein Analysts
 Global Markets React to Strong U.S. Jobs Data and Rising Yields
 RBI Uses $10 Billion Currency Swaps to Drain Excess Rupee Liquidity
 BOJ Flags Import Costs and Yen Shocks as Persistent Inflation Risks
 Moldova Criticizes Russia Amid Transdniestria Energy Crisis
 2025 Market Outlook: Key January Events to Watch
 European Stocks Rally on Chinese Growth and Mining Merger Speculation
 Yen Sinks as BOJ Rate Hike Fails to Impress Markets
 Indonesia Surprises Markets with Interest Rate Cut Amid Currency Pressure
 Urban studies: Doing research when every city is different
 Fed Unveils Stablecoin Rules Under GENIUS Act
 Mexico's Undervalued Equity Market Offers Long-Term Investment Potential
 U.S. Stocks vs. Bonds: Are Diverging Valuations Signaling a Shift?


 Add as a preferred source on Google
As we described in the Outlook, EUR maintains a number of structural supports, including its status as a BoP surplus economy and its overall cheap valuation. We’ve designed our shorts to neutralize each of these. On the former, any benefit to EUR from its net lending status as the global backdrop continues to deteriorate should be more than offset by a similar dynamic for CHF, which has the strongest BoP position in G10 (CA +10%). JPY shares similar, if less robust, surplus status.
And on valuation, EUR may be due for some mean reversion but not more so than JPY, which screens inordinately cheap especially in relation to the current stage of the business cycle. We would expect the latter to significantly outperform as a result should the macro backdrop worsen considerably. By neutralizing two of these underlying pillars, the hurdle for our trades to underperform remains a material turnaround in the European growth narrative.
As described above, there seems to be no inflexion point insight; JPM economists have again revised down our expectations of German growth (now into contractionary territory for 2Q), underscoring that growth in the region cannot even manage to plateau, let alone improve.
Finally, while EUR may receive bouts of support from Pres. Trump’s increasing vociferousness on currencies and monetary policy, that will also preclude any CHF weakening from SNB intervention, which balances our risks there as well.
Stay short EURJPY in cash. Marked at 0.79%.
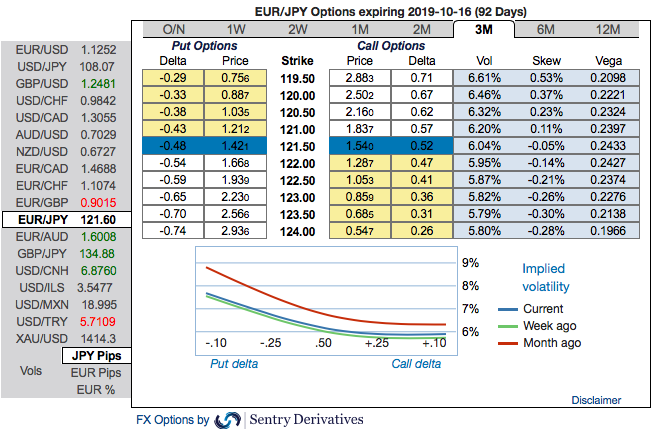
Please be noted that the positively skewed IVs of 3m EURJPY contracts that are also signifying the hedging interests for the bearish risks. The bids for OTM puts of these tenors expect that the underlying spot FX likely to break below 119.00 levels so that OTM instruments would expire in-the-money.
Most importantly, to substantiate the above indications, we could see some minor positive shifts in existing bearish risk reversal set-up of EURJPY that indicates the long-term hedging sentiments across all tenors are still substantiating bearish risks amid minor abrupt upswings in the short-term. Please be noted that 3m IVs are overall OTC barometer is a noteworthy size in the forex options market that can stimulate the underlying forex spot rate.
Hence, we’ve advocated buying 3m EURJPY (1%) ITM -0.79 delta puts for aggressive bears on hedging grounds as the mild abrupt upswings were contemplated earlier.
Alternatively, ahead of ECB monetary policy meeting, we advocated shorts in futures contracts of mid-month tenors with a view to arresting potential dips. We now wish to roll over these contracts for August month deliveries. Source: Sentrix and Saxobank







