


 Solana User Growth Jumps 33%, Outpacing Ethereum and Chainlink
 Fed Minutes Signal Another Rate Hike by Year-End
 Bitcoin Price Falls Below $83K as Liquidations Hit $697M
 RBA Says ASX Still Falls Short on Governance and Risk Controls
 Strategy’s STRC Nears $100, Raising Prospects for Major Bitcoin Buys
 Cardano Price Surges 10% as ADA Targets $0.30
 Circle Stock Falls 4% as Crypto Selloff Overshadows SAP Pay Expansion
 JPMorgan CEO Jamie Dimon Warns Mythos AI Raises Cyber Risk Tenfold
 Bitmine to Stop Ethereum Buying After Reaching 5% ETH Supply
 Zcash Privacy Demand Rises as AI Exposes Bitcoin Transactions
 Fed’s Hammack Says Bond Yield Surge Is Not Driven by Inflation Fears
 Litecoin Marks 15 Years as Grayscale Backs LTC ETF Push
 Kalshi Withdraws PEPE Perpetual Futures Filing


 Add as a preferred source on Google
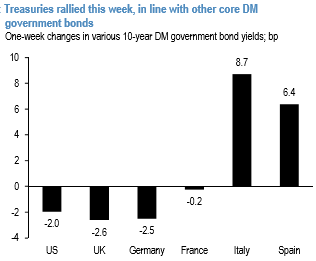
US Treasury yields moved 3-6bp higher over the first half of the week, as domestic producer prices and import prices came in higher than expectations, and the May refunding auctions all tailed amid weakening in end-user demand (refer above nutshell).
However, this more than fully reversed following Friday’s benign April CPI reading. Since our last publication, front-end and intermediate Treasury yields declined 1-4bp, and the US broadly outperformed other DM government bond markets (refer histogram chart).
But still, with the unemployment rate sitting at its lowest levels of the expansion, matching the 2006 lows, and below the Fed’s year-end and longer-run projections, we continue to expect that the tightness of labor markets will drive the Committee to raise rates by 25bp at the next policy meeting on June 13-14.
Certainly, OIS markets are pricing approximately two thirds odds the Fed will raise rates next month, suggesting limited room for very front-end rates to move higher over the near term, but cyclical dynamics suggest intermediate yields can rise over the next few weeks ahead of the FOMC meeting. The yields have consistently risen ahead of FOMC meetings which are accompanied by an SEP and a press conference.
The third ogive chart shows that over the past two years, 5-year Treasury yields have risen by an average 5bp in the month leading up to long-form FOMC meetings, and this has occurred prior to 7 of the last 8 meetings.
We are bullish on the Ultra 10-year (UXY) contract weighted calendar spread. Wildcard optionality is modest while asset managers are net short. Furthermore, this contract has consistently richened into the first notice date since its inception.
We are bearish on the 10-year note (TY) contract weighted calendar spread. Asset managers and central banks are again net long, whose positions have proven a reliable driver of price action through the roll. Beyond this, the calendar roll has exhibited a strong cyclical tendency to narrow into the first delivery date.







