


 Binance to Shut Down Crypto Mining Pool Services on November 10
 Geopolitical Shocks That Could Reshape Financial Markets in 2025
 Arthur Hayes Announces FLOP Testnet Launch Within Weeks
 Ripple Mints 19.6 Million RLUSD Amid Banking Expansion
 Dogecoin Price Rebounds as DOGE Defends $0.08 Support
 Indonesia Surprises Markets with Interest Rate Cut Amid Currency Pressure
 S&P 500 Relies on Tech for Growth in Q4 2024, Says Barclays
 Zcash Price Drops 30% as ZEC Tests Critical $1,120 Support
 Crypto Derivatives Dashboard: Bulls Retain Control Amid $488M Liquidation Flush
 Ripple-Backed Evernorth Set for Nasdaq Debut With 473 Million XRP
 China’s Growth Faces Structural Challenges Amid Doubts Over Data
 Stock Futures Dip as Investors Await Key Payrolls Data
 Energy Sector Outlook 2025: AI's Role and Market Dynamics
 2025 Market Outlook: Key January Events to Watch
 US Futures Rise as Investors Eye Earnings, Inflation Data, and Wildfire Impacts


 Add as a preferred source on Google
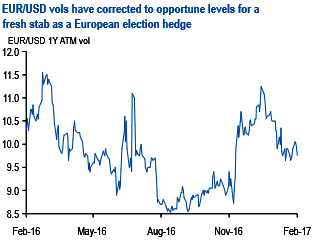
We believe that political risk into the French elections is priced more appropriately in bonds (but not in currencies) than going into the Brexit and US vote.
In the remote scenario of a Le Pen Presidency with supportive government and Parliament, 10Y Bunds could approach 0bp and 10Y France-Germany 200bp, with sharply wider Bund swap spreads (54bp), FRA/OIS (20bp) and EURUSD cross currency basis (-60bp), and higher volatility (Bund implied 6bp/day).
Less extreme scenarios of Le Pen Presidency but cohabitation or extreme left Presidency will likely result in considerably less extreme outcomes.
EURUSD vols do not reflect this increased anxiety however, having dipped 1.5 -2.0 vols across the curve from their December highs (refer above chart).
Even though the probability of a catastrophic electoral outcome in France is low in our mind, the fact that EURUSD carries little-to-no risk premium for a Le Penn shock - short-term fair value models indicate that the currency trades about three cents stronger than Euro-US rate differentials and sovereign spreads would justify – is disconcerting; nor is positioning extreme short enough to suggest sufficient investor preparedness for a tail result.
We prefer outright widener in FRA/OIS as valuations appear cheap by historical standard and we see limited risk of inversion of FRA/OIS (FRA/OIS on 3s curve trading persistently negative). However, given the negative carry of outright widener we currently hold FRA/OIS steepener between reds and greens. As we get closer to the French election we would be bias to roll the existing position into outright widener: we prefer the front end of the curve (like Sep17 of Dec17), where the negative slide is limited.
EURUSD cross currency basis in our view appears the least attractive way to position for funding stress under a Le Pen presidency with support from FN government and parliamentary majority. Current valuations in reds EURUSD cross currency basis are broadly in the middle of their range since QE started.
In vol, call skew in Bund options is currently not pricing the jump in implieds in a rally in Bund yields (discussed above). That is, OTM calls are cheaper compared to ATM calls indicating that market is still pricing a decline in implieds with yields. Therefore, as a hedge towards the tail risk, we would prefer buying Bund gamma via outright OTM call options.
For example, we recommend buying the 163 Apr Bund gamma via delta-hedged calls (implied vol around 3.8bp/day). The 163 strike corresponds to 10Y German benchmark Bund yield at around 15bp. Ideally, we would prefer options struck around 0% yield and with longer expiries (say the June options which expire in May).
However, on liquidity and gamma considerations we prefer the Apr Bund calls but note that we would roll these into May/June options as liquidity builds up in these contracts.
Buying only Apr Bund gamma outright is not advised but also versus selling maturity matched swaption gamma (Bund calls versus swaption receivers, delta-hedged). As swap spread directionality intensifies, Bund gamma would outperform swaption gamma.







