


 Moldova Criticizes Russia Amid Transdniestria Energy Crisis
 Ripple Mints 19.6 Million RLUSD Amid Banking Expansion
 Gold vs Bitcoin: Investors Eye Inflation Hedge as Crypto Adoption Grows
 DeFi Development Adds 22,070 SOL to Solana Treasury
 S&P 500 Relies on Tech for Growth in Q4 2024, Says Barclays
 Global Markets React to Strong U.S. Jobs Data and Rising Yields
 U.S. Stocks vs. Bonds: Are Diverging Valuations Signaling a Shift?
 Crypto Derivatives Dashboard: Bulls Retain Control Amid $488M Liquidation Flush
 Lithium Market Poised for Recovery Amid Supply Cuts and Rising Demand
 Goldman Predicts 50% Odds of 10% U.S. Tariff on Copper by Q1 Close
 Solana Alpenglow Upgrade Set for October 21: What It Means for SOL
 U.S. Banks Report Strong Q4 Profits Amid Investment Banking Surge
 Pi Network Price Eyes $0.10 Ahead of Protocol 28 Upgrade
 Ripple-Backed Evernorth Set for Nasdaq Debut With 473 Million XRP
 U.S. Treasury Yields Expected to Decline Amid Cooling Economic Pressures


 Add as a preferred source on Google
10Y Treasuries yields and US dollar edged lower amid political uncertainties and mixed economic data. On the political front, uncertainty over the capacity of the US administration to implement its policy programme grew. Echoing this, US data were mixed with a disappointing job report, subdued wage growth and soft core inflation print in May. That said, our economists and consensus still expect a 25bp Fed rate hike in June, noting US data would need to deteriorate much more to prevent a hike in June.
While in Europe, The Macron victory at the French presidential elections coupled with better economic data supported risky asset prices in Europe. Inflation, however, remained subdued. Political risks have considerably abated, but others might resurface (uncertainties about the UK general election and the outcome of the Brexit negotiations, the increasing chance of elections in Italy in the autumn). Given these factors, the ECB is expected to leave its monetary policy broadly unchanged at its meeting next Thursday.
Europe-listed ETFs posted $11.3bn creations in May, after $3.7bn in April, almost twice the 3y monthly average of $6bn. Overall, almost all exposures gathered net inflows, in particular IG corporate bonds, EM assets, US government bonds, Eurozone and World equities, all significantly above their long-term average monthly creations. The little redemption came from German and UK equities as well as inflation-linked bond indexations.
EM equities: largest inflows within equity ETFs (+$1.5bn). World: +$1.3bn. Eurozone: significant inflows on large & small caps. US: creations after material outflows in April.
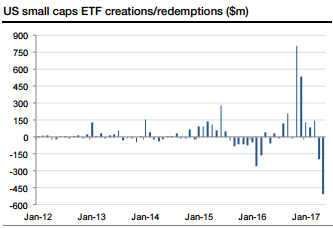
German equities: largest outflows in nine months (- $715m). UK equities: two-year-high outflows (-$345m). US small caps: record outflows (-$507m, see above chart).
EM gov. bonds: continuous inflows (+$1.1bn). US gov. bonds: +$515m, the most in more than one year. European gov. bonds: +$201m after 4 months of outflows.
Gold: $725m creations after a modest $67m inflows in April (see above chart). Silver: +$190m, the highest level in almost 4 years (see above chart). Out of the top 10 monthly inflows, 8 were on gold or silver ETPs. Oil: $78m creations, slightly above the previous month’s level. Industrial metals: +$75m mainly on broad and copper indexations.
Inflation-linked bonds: all-time-high outflows (-$834m), especially on USD indexations (as was the case in April).







