


 Stellar Integrates Chainlink to Unlock $3.54 Billion in Tokenized Assets
 Morgan Stanley Predicts $10 Trillion RWA Market by 2030
 UNCX Network Hack Drains $86K From Ethereum Token Pool
 U.S. Treasury Yields Expected to Decline Amid Cooling Economic Pressures
 Dogecoin Price Rebounds as DOGE Defends $0.08 Support
 Global Markets React to Strong U.S. Jobs Data and Rising Yields
 UBS Projects Mixed Market Outlook for 2025 Amid Trump Policy Uncertainty
 Goldman Predicts 50% Odds of 10% U.S. Tariff on Copper by Q1 Close
 S&P 500 Relies on Tech for Growth in Q4 2024, Says Barclays
 U.S. Stocks vs. Bonds: Are Diverging Valuations Signaling a Shift?
 Moody's Upgrades Argentina's Credit Rating Amid Economic Reforms
 XRP Price Drops 3% Despite Ripple-Backed Evernorth Nasdaq Debut
 Oil Prices Dip Slightly Amid Focus on Russian Sanctions and U.S. Inflation Data
 2025 Market Outlook: Key January Events to Watch
 Energy Sector Outlook 2025: AI's Role and Market Dynamics


 Add as a preferred source on Google
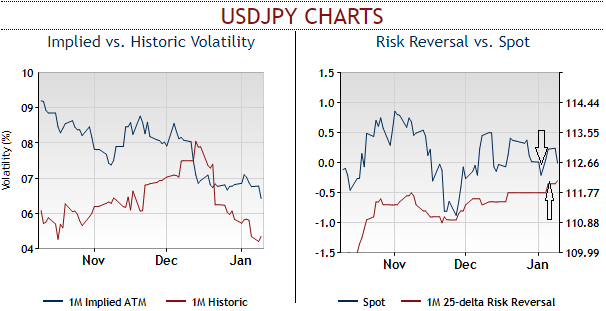
Yen vols (IVs) have been decimated and RVs are not in tandem with this over the past two months. Well, long-end (1Y –5Y) yen vols dropped in near-parallel fashion in December by a full vol across the curve (refer 1st chart), representing a > 1-sigma monthly decline that cannot be explained the softening in realized vols alone (refer above chart).
It is true that USDJPY spot has delivered precious little excitement within a narrow 112 –113.50 range since November, but the magnitude of the vol move is nonetheless surprising for two reasons:
1) Initial levels of vol and flatness of the vol curve were among some of the most depressed in history, and
2) Back-end USDJPY forwards sold-off to a greater degree than shorter-dated as wider US –Japan rate differentials pushed forward points further to the left without an offsetting rally in spot; lower USDJPY forwards is, of course, the direction of higher, not lower volatility according to risk-reversals that are solidly bid for USD puts/JPY calls.
Put spreads: We’ve already advocated this options strategy in the recent past as we could foresee only a small chance of that commitment waning in 2018 because the inflation rate won’t get anywhere near 2%, but the net result is a huge skew in the range of outcomes for the USDJPY.
Buy USDJPY 1y put spread strikes 106/103, global knock-in 116 Indicative offer: 0.33% (vanilla: 0.75%, spot ref: 112.676)
A USDJPY 1y put spread strikes 106/103 would cost 0.75%, thus providing a maximum payoff of 3.9 times the premium. Setting a global KI at 116 more than halves the price to provide leverage reaching 8.8 at 103 in one year.
Selling USDJPY 1y skew: In selling downside strikes, buy USDJPY puts is paying for the negative skew of low strikes. As we don’t foresee USDJPY crumpling below 100, needless to buy the total downside. Accordingly, we also finance our puts by selling the downside skew via put spreads.
In setting a topside knock-in, near-term, USDJPY should be initially mildly supported by mounting US yields. This suggests conditioning medium-term put spreads by a topside knock-in. Such a barrier will cheapen the vanilla trade, as the bearish skew discounts the market implied the probability of bullish moves.
Currency Strength Index: FxWirePro's hourly USD spot index is showing 69 (which is bullish), while hourly JPY spot index was at 147 (bullish) while articulating at 12:08 GMT. For more details on the index, please refer below weblink:
http://www.fxwirepro.com/currencyindex.
FxWirePro launches Absolute Return Managed Program. For more details, visit:







