


 Banking scandal rocks Brazil’s politics and the country’s presidential election in October
 AI is supercharging money scams – here’s what you can do to protect yourself
 Synthetic data could ease people’s concerns about privacy breaches. But who gets to create it?
 Big AI wants to slow down AI research. Is it a safety pause or a strategic retreat?
 Gold Slides to $4,262 as Hawkish Fed Rate Hike Triggers Technical Breakdown
 Europe can’t achieve space sovereignty alone. Here’s why
 1 in 3 uni students experience serious financial hardship. Could concession cards for all help?
 Unsustainable – or manageable? We don’t yet know how data centres will impact Australia’s environment


 Add as a preferred source on Google
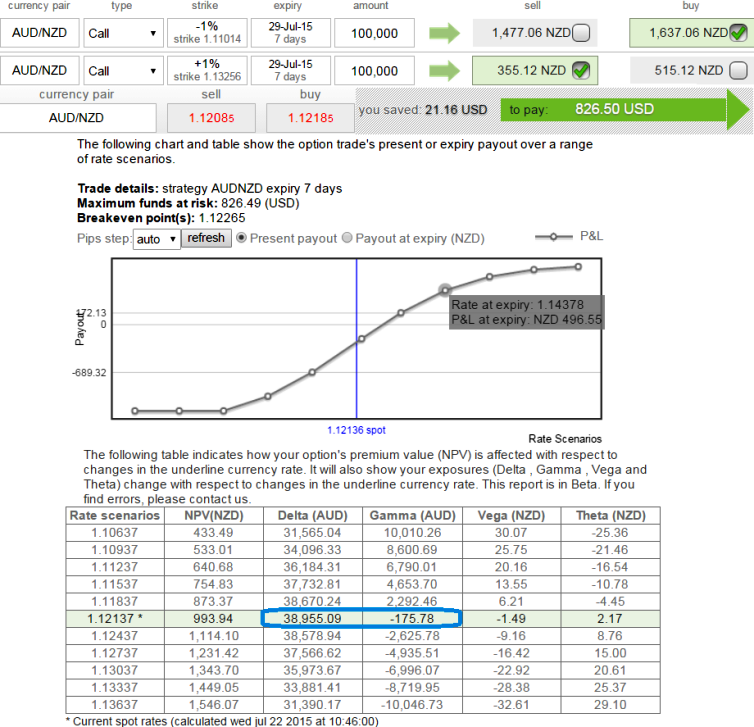
We've been formulating a lot of call spreads on highly volatile currency pairs (AUD/NZD is the one among the pool) and have been drawing up some customized strategies by using P&L tools and techniques to look at the option Greeks.
While doing so it seems like the FX option of this APAC pairs have tons of Gamma. It might be puzzling because on one hand it seems some of these options are highly volatile than any other APAC currency pairs but a tiny shift in the underlying exchange rate would cause instant disaster. This can be arrested by devoting little time on ascertaining an accurate gamma.
As you can observe from the diagrammatic representation, we've constructed call spread by considering gamma closer to zero which would neutralize the implied volatility adverse impact on option prices and this position remains quite firm to achieve our hedging objectives, because we know gamma represents the change in delta, we have healthier delta at 0.38.
This results in desired hedging objective irrespective implied volatility disruptions as we've OTM shorts on side and prevailing bull run will be taken by In-The-Money calls.

- News

- Economy

- Central Banks
- Investing
- Research
- Roundups
- Digital Currency
- Insights
- Technical Analysis
- Technology
- Business
- Law
- Health
- Nature
- Fintech
- Science
- Topic
- Opinions
- ©Econometrics LLC . All Rights Reserved.
FxWirepPro: AUDNZD volatility optimizer through gamma spreads
Wednesday, July 22, 2015 5:49 AM UTC
Editor's Picks



- Market Data
Most Popular




