


 1 in 3 uni students experience serious financial hardship. Could concession cards for all help?
 ‘Buy now, pay later’ doesn’t feel like debt. For young people, that can be a big problem
 Synthetic data could ease people’s concerns about privacy breaches. But who gets to create it?
 Physicists zoom into the birth of cosmic rainstorms with new CERN study
 Gold Slides to $4,262 as Hawkish Fed Rate Hike Triggers Technical Breakdown
 Unsustainable – or manageable? We don’t yet know how data centres will impact Australia’s environment
 What is Zionism? The different meanings of a contested term
 Goldman Sachs Forecasts Fed Rate Hike as Inflation Risks Rise


 Add as a preferred source on Google
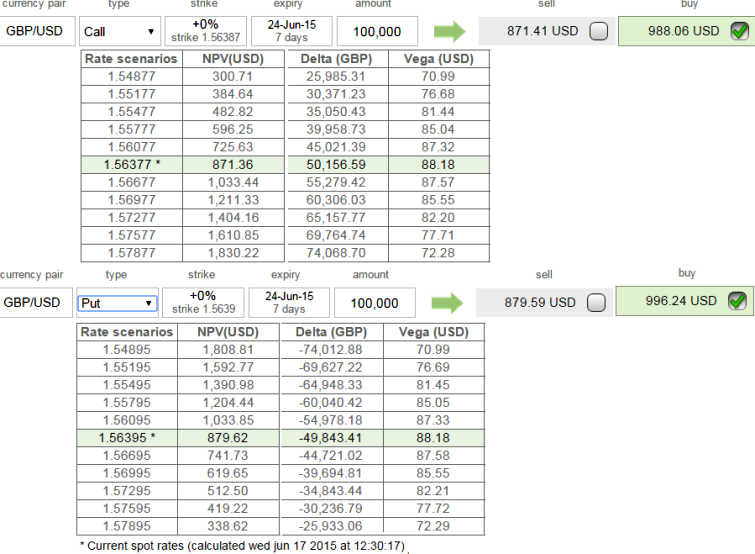
As shown in the diagrammatic representation, Bears participation in put options is equally weighed with calls.
As we can see 7D At-The-Money -0.49 delta bear one touch options are priced in at and carries vega at 88.18 while 0.5 delta calls are available at with vega 88.13.
That means bears in the underlying FX market are holding equal vested interest despite vega denotes 88.13.
This computation hints on put options are also likely to offer similar returns on every corresponding change in implied volatility in the underlying market.
To substantiate in addition NPV of calls are prevailing at 13.38% and puts at 13.28% which is almost closer.
Hence, the rationale will divulge tug of war between bulls & bears is quite tight even though in the uptrend rallies.

- News

- Economy

- Central Banks
- Investing
- Research
- Roundups
- Digital Currency
- Insights
- Technical Analysis
- Technology
- Business
- Law
- Health
- Nature
- Fintech
- Science
- Topic
- Opinions
- ©Econometrics LLC . All Rights Reserved.
NPV of GBP/USD Vega ATM puts raise cautious signs for bulls
Wednesday, June 17, 2015 7:26 AM UTC
Editor's Picks



- Market Data
Most Popular




