


 G20 Divided Over US Push to Curb Industrial Overcapacity
 Russia Strikes Kyiv Bridge as Ukraine Infrastructure Attacks Escalate
 Iran Keeps Strait of Hormuz Closed as War Talks Stall
 Xi Rest Breaks Cut Trump Summit Schedule, WSJ Reports
 Japan Protests to US After Marine Arrested in Okinawa Murder Case
 Iran Faces Rising Pressure as U.S. Builds Military Presence
 India-US Trade Deal Talks Hit Plateau, Sitharaman Says
 Tsai Ing-wen to Visit US for Stanford Security Conference
 US Caribbean Vessel Strike Kills Four
 California Woman Arrested Over Alleged Spying on Taiwan President’s Son
 Merz to Meet ECB Frontrunners Knot and De Cos
 Australia Probes Flydubai Co-Pilot’s Links After FZ1073 Hijack Attempt
 Nicaragua Withdraws From Central American Parliament
 Ukraine to Intensify Strikes on Russian Oil Refineries
 Merz Pledges €1 Billion in Ukraine Aid During Kyiv Visit
 UK Warned Over Growing Reliance on US Cloud Providers
 Flavio Bolsonaro, Lula Head to Brazil Presidential Runoff


 Add as a preferred source on Google
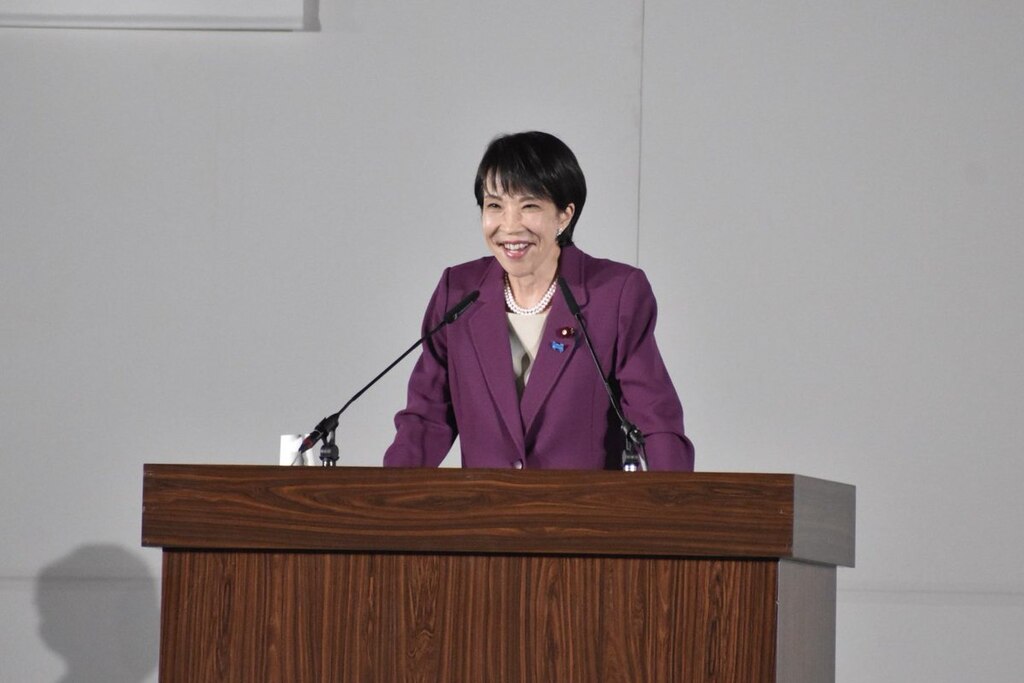
Japanese Prime Minister Sanae Takaichi pledged Monday to control government bond issuance and respond quickly to market volatility as rising yields intensify concerns over Japan’s public finances.
In a policy speech to parliament, Takaichi stressed that fiscal sustainability would remain central to her government’s “responsible and proactive” fiscal policy, even as Tokyo increases spending to strengthen economic growth. The government also plans to review existing tax breaks and subsidies.
Her comments come as Japanese government bond yields climb amid concerns about higher debt issuance, inflation and the economic impact of the Middle East war. The 30-year JGB yield reached a record 4.235% on Monday.
Japan’s public debt stands at roughly twice the size of its economy, the highest level among developed nations. Borrowing costs are also increasing as the Bank of Japan raises interest rates and reduces bond purchases after decades of aggressive monetary stimulus.
Takaichi said the government aims to attract private investment into strategic growth sectors through large-scale, long-term fiscal spending implemented in a predictable manner. However, Tokyo will seek to limit annual bond issuance by considering tax revenue, interest rates, debt-servicing costs and broader economic and financial market conditions.
“If the economy and markets make unexpected moves, we will scrutinise their impact and respond nimbly as needed,” Takaichi said.
Fiscal policy is expected to become a major focus of Japan’s extraordinary parliamentary session. Investors are particularly watching Takaichi’s proposal for a two-year tax cut on food beginning next April. The plan has already pressured bonds because the government has yet to provide details on how it will replace lost tax revenue.
Meanwhile, ministries are seeking record spending levels as the government prepares next year’s budget.
Takaichi also pledged multi-year funding for strategically important economic security initiatives, while promising clearer communication with investors and the public.
“We will implement policies steadily, get things done one by one, and communicate them carefully to the public and markets,” she said.







