


 China’s robots can run faster than Usain Bolt – now they are being prepared for war
 Europe can’t achieve space sovereignty alone. Here’s why
 1 in 3 uni students experience serious financial hardship. Could concession cards for all help?
 Big AI wants to slow down AI research. Is it a safety pause or a strategic retreat?
 Gold Surges Past $4400 on Crude Oil Rally; Bullish Trend Dominates
 Banking scandal rocks Brazil’s politics and the country’s presidential election in October
 What is Zionism? The different meanings of a contested term


 Add as a preferred source on Google
The EM strategies have turned underweight on Asia FX given a combination of higher core yields, the break out of USD/CNY to above 6.70 and multiple idiosyncratic issues.
The capital outflows from China had already picked up before expectations of a Fed hike and despite resilient data.
The additional dynamic of USD strength and expectations of a Fed hike in December suggests that risks to capital flight are skewed to the upside in Q4.
As a result, the expectation is for CNY weakening to accelerate in Q4, with spillover to the rest of the region as well.
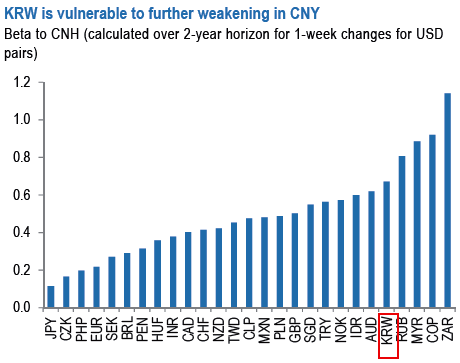
KRW is a notable candidate to short given that it has among the highest sensitivity in Asia to CNY weakness (see above chart).
In South Korea, the September exports drop inflated by temporary factors.
The consumer price inflation surprised on the upside.
The BoK left its base rate steady for the fourth straight month at the record low of 1.25 pct at its October meeting, as anticipated.
In addition, the added uncertainty on corporate earnings has the potential to slowdown equity inflows from offshore investors. So, long USDKRW are encouraged at 1135.43 via 3m NDFs.







